
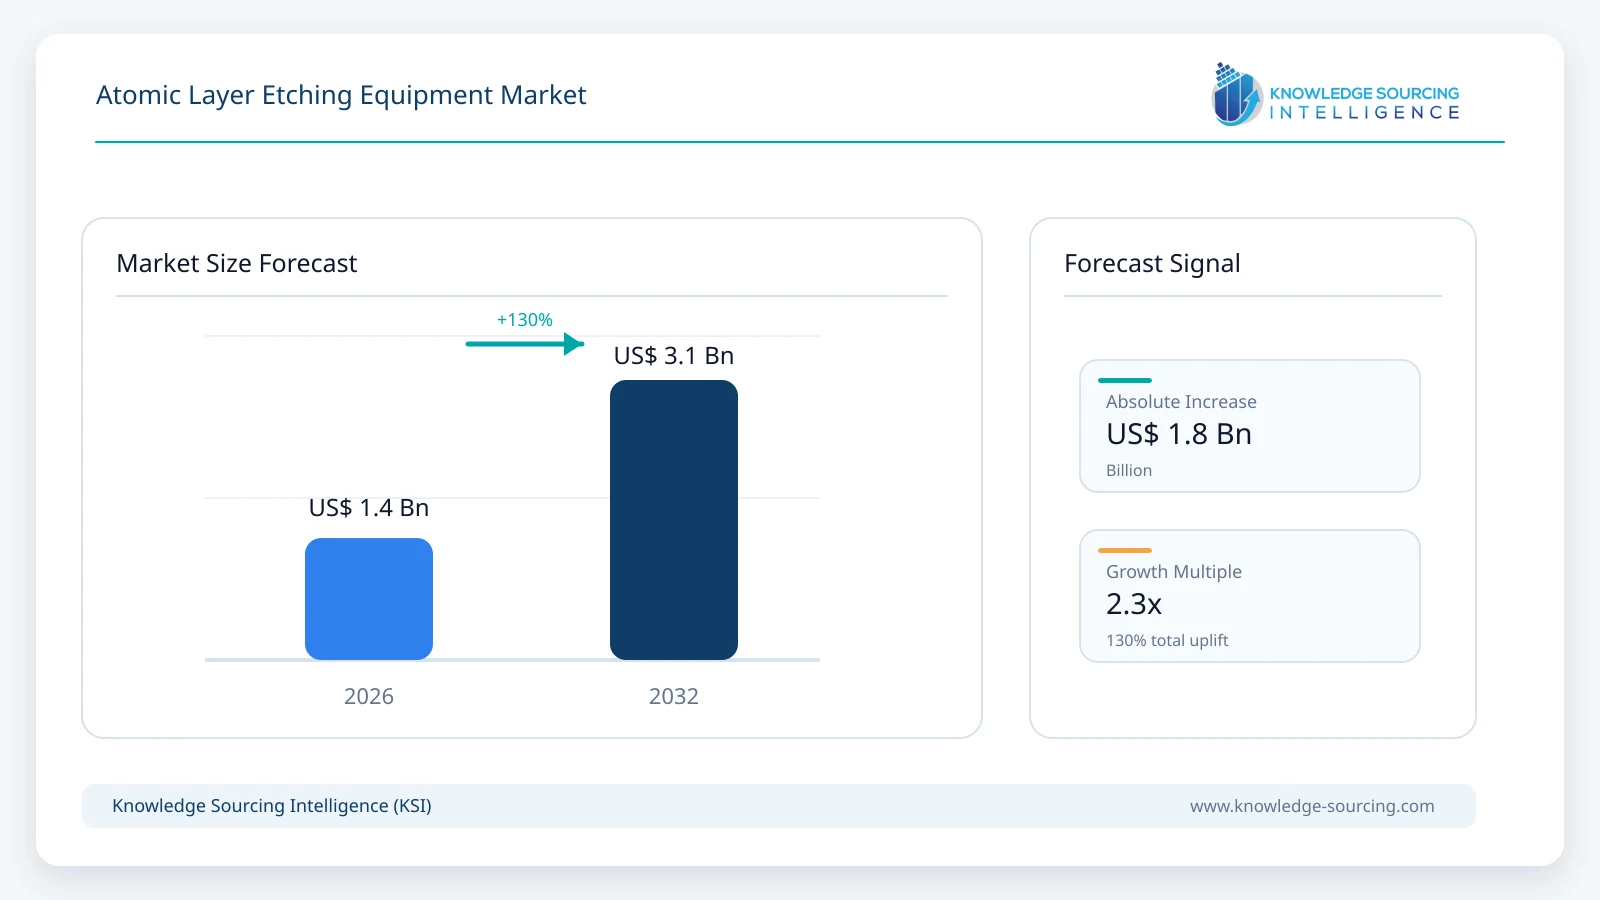
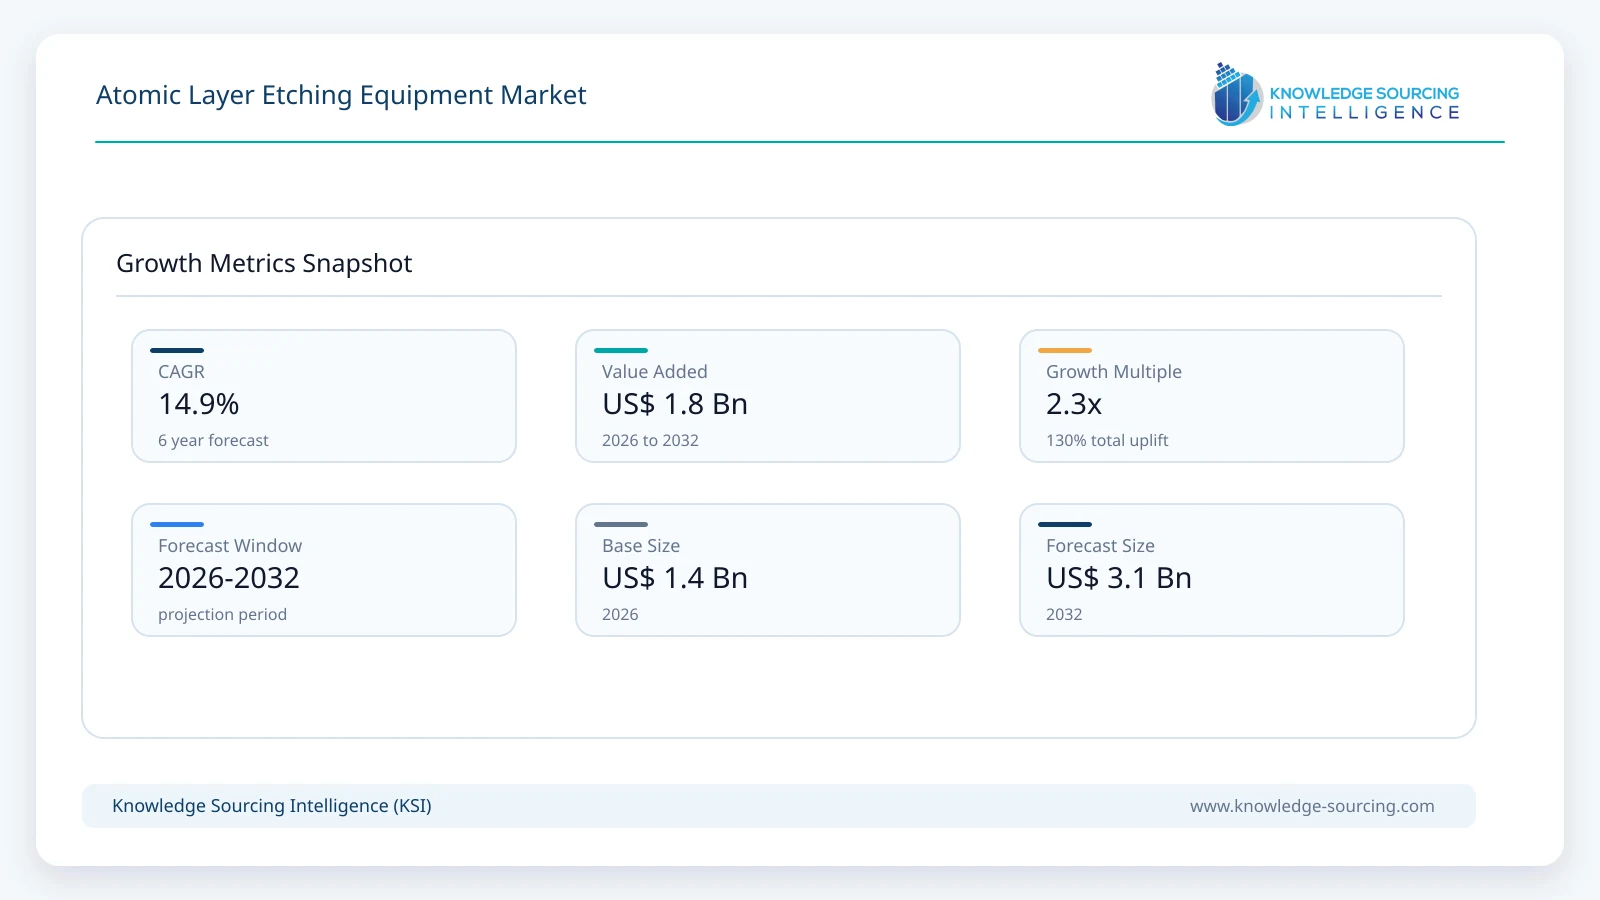
The Atomic Layer Etching Equipment Market is estimated at USD 1.35 billion in 2026 and is projected to reach USD 3.10 billion by 2032, representing a CAGR of 14.9% during the forecast period.
Key Highlights
• Plasma-enhanced ALE remains the principal commercial architecture because it combines atomic-scale depth control with directional etching required in semiconductor pattern transfer.
• GAA logic, low-k interconnects and high-layer-count NAND increase demand for etching with lower ion damage and tighter selectivity than continuous plasma processes can provide.
• Throughput remains the central commercialization challenge, pushing suppliers toward shorter cycles, faster gas switching and hybrid ALE/RIE process sequences.
• Compound semiconductors create an additional adoption path because GaN and AlGaN devices are highly sensitive to plasma-induced surface damage.
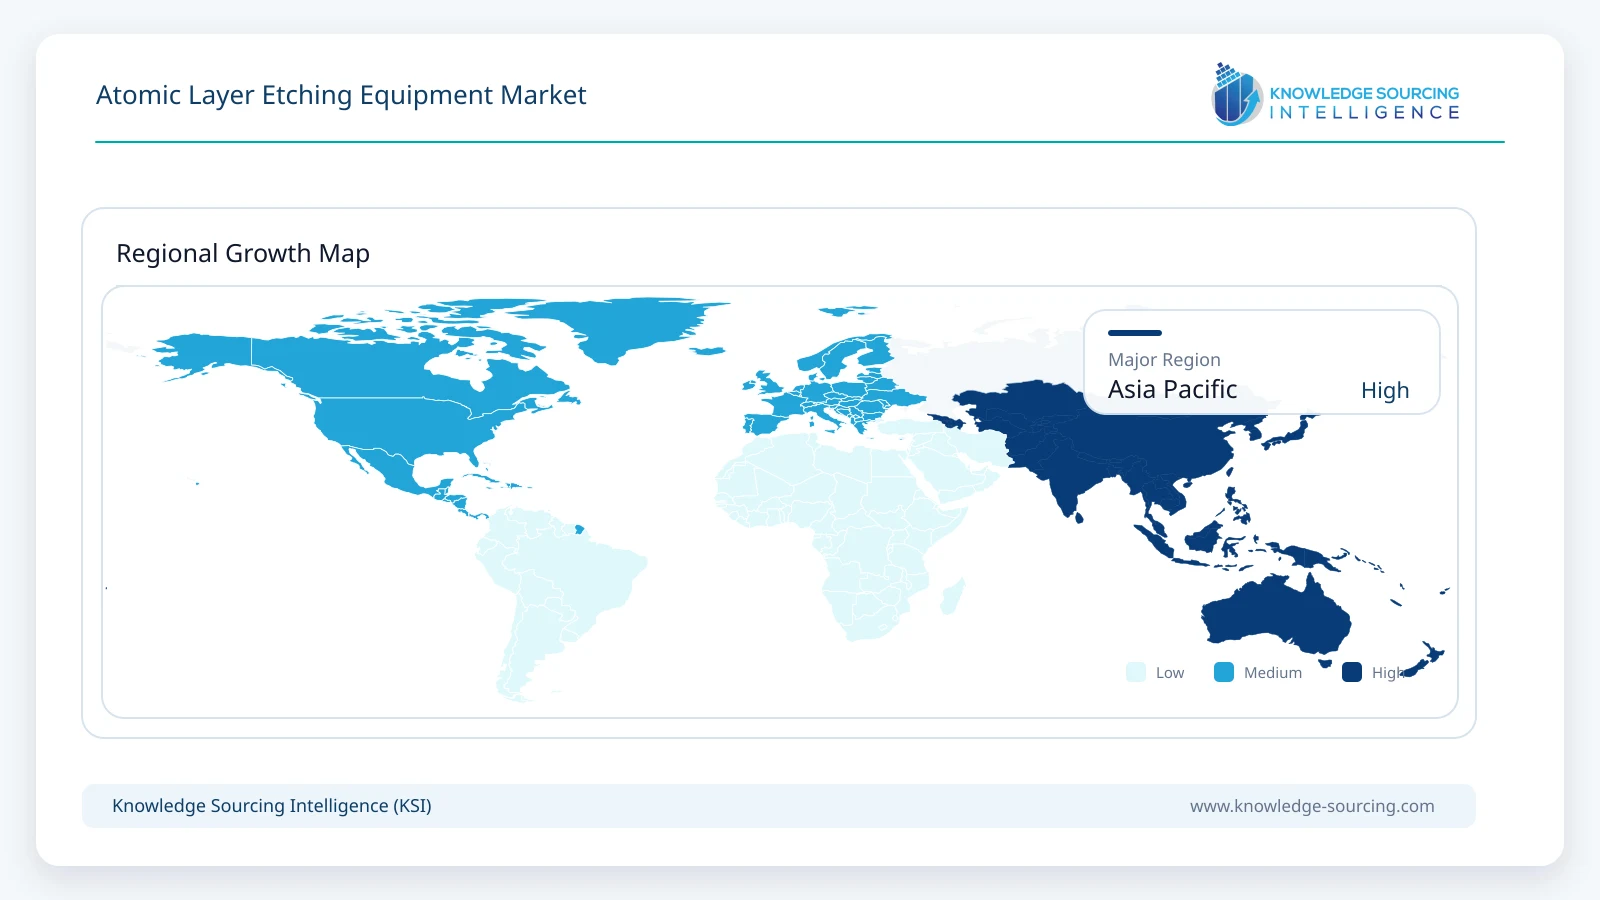
• Asia Pacific remains the largest opportunity because Taiwan, South Korea, Japan and China combine advanced-node manufacturing with major etch-equipment and process-development ecosystems.
Market Overview
ALE equipment creates controlled removal by separating the chemical modification of a surface from the energy step that removes the modified layer. In plasma-enhanced ALE, a reactant modifies only the top surface and a low-energy ion pulse then removes the altered material. Because the reaction is designed to become self-limiting, etch depth is governed more by the number of cycles than by exposure time alone. Thermal ALE uses sequential chemical reactions without ion bombardment, while hybrid and quasi-ALE approaches relax strict self-limiting behavior in exchange for higher throughput or easier integration with existing etch chambers.
The technology is particularly valuable when a conventional continuous plasma process has too little process margin. Gate-all-around nanosheets, low-k dielectric structures and thin functional layers can be damaged by energetic ions or over-etch. ALE can reduce surface modification below the intended depth and improve selectivity between materials with similar conventional etch behavior. In memory, the technology is increasingly relevant to high-aspect-ratio structures, trim steps and sensitive interface formation. In GaN high-electron-mobility transistors, shallow gate recesses require precise depth control while preserving the underlying crystal.
Commercial equipment is evolving in two directions. Large semiconductor equipment companies integrate ALE as an advanced mode within broader etch platforms, allowing customers to alternate continuous high-productivity etch with atomic-precision finishing steps. Specialist suppliers offer dedicated ALE systems for compound semiconductors, research and pilot production. The resulting market is therefore not limited to stand-alone ALE chambers; it includes tools where ALE capability is one of several process modes but generates incremental hardware, process and service value.
Market Drivers
Advanced logic requires atomic-scale profile and damage control
Gate-all-around transistors introduce nanosheets, narrow spacers, inner-spacer cavities and complex material stacks that reduce tolerance for plasma damage and profile variation. ALE can remove material in controlled cycles while reducing excessive ion penetration. The same requirement extends into low-k interconnect patterning, where Samsung researchers in 2026 showed that reduced-ion-energy ALE could improve vertical profile formation and increase available copper volume while limiting dielectric damage.
High-layer-count memory increases selectivity and aspect-ratio requirements
NAND and DRAM structures combine increasingly deep features with thin films and interfaces whose thickness must be controlled precisely. High-aspect-ratio etching remains dominated by high-productivity plasma etch, but ALE is increasingly useful for selected trim, clean-up, interface and profile-control steps. As memory stacks become taller, even small deviations in local dimensions or material selectivity can accumulate across hundreds of layers, raising the value of atomic-precision process control.
Compound semiconductors need low-damage recess etching
GaN and AlGaN power and radio-frequency devices can suffer threshold-voltage variation and degraded surface quality after aggressive plasma exposure. Samco and Oxford Instruments both position ALE for GaN-based high-electron-mobility transistors, where controlled gate recess and low surface damage are more important than maximum etch rate. Growth in GaN power electronics, RF devices and photonics therefore broadens ALE demand beyond leading-edge silicon logic.
High-NA EUV and atomic-scale patterning increase process integration complexity
Lithography can print smaller features, but the pattern must still be transferred through increasingly complex material stacks. Atomic-precision etch becomes more important as High-NA EUV, self-aligned patterning and area-selective processing reduce tolerance for edge roughness and process-induced damage. Tokyo Electron has highlighted atomic-layer precision processes as an enabler of advanced patterning, while ALE is increasingly paired with deposition and surface-treatment steps in integrated process sequences.
Restraints and Adoption Challenges
Low throughput is the most important constraint because ALE requires multiple dosing, purge and activation steps for each small amount of material removed. Perfect self-limiting behavior can also break down in real production chambers because of surface history, reactor-wall conditions, charging, particle generation and local pattern effects. Equipment must switch gases and plasma conditions rapidly without cross-contamination. Process development is therefore more complex than simply slowing a conventional etch recipe. In addition, many high-volume applications use ALE only for the most sensitive portion of a process sequence, limiting the share of wafer time that can economically move to fully cyclic etching.
Segment Analysis
By Etch Architecture
Plasma-enhanced ALE is the most commercially established architecture because low-energy ions provide directional removal while the surface-reaction step limits the amount of material available to etch. Lam Research, Oxford Instruments, Plasma-Therm and Samco all support plasma-based or ion-assisted atomic-precision etch approaches. Hybrid ALE/RIE systems are also important because they let fabs use conventional etch for bulk removal and switch to ALE for a final critical layer, spacer, recess or surface-finishing step.
Thermal ALE remains more selective and potentially gentler for some materials, but its commercial use is narrower because suitable volatile reaction products and process windows are material-specific. Radical-assisted, cryogenic and wet ALE approaches are also advancing for selected applications. The market is therefore expanding through a portfolio of atomic-precision removal mechanisms rather than converging on one universal ALE chemistry.
Equipment Architecture | Core Mechanism | Primary Applications | Commercial Direction |
Plasma-enhanced ALE | Sequential surface modification and low-energy plasma/ion removal | Logic, low-k, memory, compound semiconductors | Largest commercial architecture |
Ion-assisted ALE | Chemically modified surface removed by controlled ion energy | Directional nanoscale etch, recess formation | Growing with tighter ion-energy control |
Thermal ALE | Sequential self-limiting chemical reactions without plasma | Oxides, selected metals and dielectrics | Selective but material-specific |
Hybrid ALE / RIE | Continuous etch combined with cyclic atomic-precision finishing | High-volume logic and memory process integration | Important route to higher productivity |
Cryogenic / radical-assisted ALE | Low-temperature adsorption or radical surface modification | Advanced dielectric etch and sensitive materials | Emerging process window |
Research / compound-semiconductor ALE | Flexible ICP/RIE platforms with ALE recipes | GaN, AlGaN, III-V, 2D materials, photonics | Broadening beyond silicon CMOS |
Market and Technology Indicators
Indicator | Current Evidence | Market Impact |
Industrial low-k evaluation | Samsung published a 2026 industrial perspective showing ALE benefits and identifying throughput, particles and process complexity as key adoption barriers. | Confirms ALE is moving deeper into production-oriented interconnect development. |
Lam Flex ALE capability | Lam markets plasma-enhanced ALE through its Flex dielectric etch family using Advanced Mixed Mode Pulsing. | Demonstrates ALE integration within high-volume logic and memory platforms. |
Tailored waveform biasing | Oxford Instruments and Quantemol are developing tailored-waveform biasing for next-generation ALE under an Innovate UK-supported project. | Improves ion-energy control and may widen low-damage process windows. |
Compound-semiconductor ALE | Samco offers RIE-400iP-ALE and RIE-800iP-ALE systems for GaN, AlGaN, Si and oxide processes. | Expands ALE beyond advanced silicon into power and RF semiconductors. |
Plasma-Therm Takachi | Plasma-Therm continues to commercialize Takachi as a dedicated ALE-capable platform; UChicago scheduled a Takachi ALE tool installation for autumn 2026. | Shows continued research-to-pilot equipment deployment. |
Atomic-precision research momentum | 2026 reviews describe plasma-enhanced ALE as increasingly important for next-generation nanofabrication while emphasizing remaining throughput and chemistry limitations. | Supports sustained tool-development and qualification spending. |
Regional Opportunity
Asia Pacific
Asia Pacific is the largest opportunity for atomic layer etching equipment because Taiwan, South Korea, Japan and China contain the largest concentration of advanced logic, memory and compound-semiconductor manufacturing. ALE demand is closely linked to processes that have the narrowest profile and damage budgets, so the region benefits disproportionately from leading-edge foundry, DRAM, NAND and power-device investment. Taiwan contributes through advanced-node foundry and packaging production, while South Korea combines Samsung logic with large DRAM and NAND capacity.
South Korea is particularly important for industrial process development. Samsung researchers published a 2026 perspective focused on the practical barriers to ALE adoption in low-k fine patterning, highlighting that the technology is no longer confined to academic demonstrations. South Korea also has strong demand for high-layer NAND and high-bandwidth-memory-related process control, which increases the value of selective and low-damage etch steps.
Japan is important on both the demand and supply sides. Tokyo Electron remains deeply involved in atomic-scale process development and has presented ALE research covering dry, cryogenic and wet approaches. Samco supplies dedicated ALE systems for compound semiconductors and advanced materials. Japanese device makers and research organizations also support process development across power electronics, photonics and advanced logic. China adds rapidly expanding domestic wafer capacity and a growing etch-equipment industry, although the most advanced atomic-precision capability remains concentrated among a smaller set of global vendors.
North America remains strategically important because Lam Research and Applied Materials have major etch technology positions, while U.S. logic, memory and R&D facilities drive development of advanced process integration. Europe contributes through Oxford Instruments, SENTECH, research institutes such as imec and CEA-Leti, and compound-semiconductor manufacturing, with particular strength in low-damage plasma and research-scale atomic-precision processing.
Competitive Landscape
The competitive landscape is led by large semiconductor etch companies that can integrate ALE into existing logic and memory process platforms, alongside specialist suppliers serving compound semiconductors, research and pilot production. Lam Research is strongly positioned through the Flex dielectric etch family and plasma-enhanced ALE process capability. Tokyo Electron has a long-running atomic-scale etch development program spanning dry, cryogenic and wet ALE approaches. Applied Materials participates through advanced plasma etch and low-damage atomic-precision process development, while Oxford Instruments, Plasma-Therm and Samco provide explicit ALE-capable platforms for specialist and compound-semiconductor applications.
SENTECH offers an ALE configuration of its SI 500 ICP-RIE platform, while Hitachi High-Tech, ULVAC, AMEC and NAURA participate in adjacent advanced etch ecosystems and atomic-precision process development. Competitive differentiation increasingly depends on ion-energy control, self-limiting chemistry, gas-switching speed, chamber cleanliness, wafer uniformity, throughput and the ability to combine ALE with conventional etch in one process flow. The highest-value positions are likely to remain with suppliers that can qualify atomic-precision recipes directly with advanced device manufacturers rather than selling generic plasma hardware.
Major companies and ecosystem participants covered: Lam Research, Tokyo Electron, Applied Materials, Oxford Instruments, Plasma-Therm, Samco, SENTECH Instruments, Hitachi High-Tech, ULVAC, AMEC, NAURA Technology, KLA / SPTS Technologies, Trion Technology, Applied Angstrom Technology and regional atomic-precision process-equipment suppliers.
Recent Developments
• August 2026: Samsung Electronics researchers published an industrial perspective on ALE for low-k fine patterning, identifying low throughput, imperfect self-limiting behavior, particles and process complexity as the main barriers to broader adoption.
• September 2026: Oxford Instruments highlighted an Innovate UK-supported collaboration with Quantemol on tailored-waveform biasing for next-generation ALE, targeting better ion-energy control, energy efficiency and lower material waste.
• August 2026: AIP Publishing highlighted ALE as a key precision nanofabrication technique while emphasizing the need to improve throughput and process simplicity for wider manufacturing use.
• 2026: Plasma-Therm continued commercial availability of the Takachi ALE platform, while the Pritzker Nanofabrication Facility at the University of Chicago scheduled installation of a Takachi ICP-RIE system with ALE capability for autumn 2026.
• 2026: Samco expanded commercial positioning of its dedicated ALE systems for GaN, AlGaN, silicon, SiO2 and compound-semiconductor applications across research and production stages.
• 2026: Lam Research continued to position plasma-enhanced ALE through the Flex dielectric etch family for advanced memory, patterning, transistor and interconnect applications.
Atomic Layer Etching Equipment Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.35 billion |
| Total Market Size in 2032 | USD 3.10 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 14.9% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Etch Architecture, Material, Semiconductor Application, Wafer / Production Environment, Equipment Configuration, Geography |
| Companies |
|
Market Segmentation
By Etch Architecture
Plasma-Enhanced Atomic Layer Etching
Ion-Assisted Atomic Layer Etching
Thermal Atomic Layer Etching
Hybrid ALE / RIE
Cryogenic and Radical-Assisted ALE
Wet and Emerging Atomic-Precision Etch
By Material
Silicon and Silicon-Based Films
Silicon Oxide and Low-k Dielectrics
Silicon Nitride
High-k and Metal Oxides
Metals and Conductors
GaN, AlGaN and III-V Materials
2D and Emerging Materials
By Semiconductor Application
Advanced Logic and GAA Transistors
Interconnect and Low-k Patterning
DRAM
3D NAND
Compound and Power Semiconductors
Photonics and Optoelectronics
Research and Emerging Devices
By Wafer / Production Environment
300 mm High-Volume Manufacturing
200 mm and Specialty Production
Research and Pilot Production
By Equipment Configuration
Stand-Alone ALE Systems
ALE-Enabled Multi-Mode Etch Platforms
Cluster-Tool Integrated ALE
Research and Development Systems
By Geography
Asia Pacific
Taiwan
South Korea
Japan
China
Southeast Asia
North America
United States
Europe
Rest of World
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Market Opportunity and Key Findings
1.2. Atomic-Precision Etch Outlook
1.3. Principal Equipment and Application Trends
2. MARKET OVERVIEW
2.1. Atomic Layer Etching Process Architecture
2.2. Surface Modification and Removal Cycles
2.3. Plasma-Enhanced, Thermal and Hybrid ALE
2.4. Throughput, Selectivity and Damage Control
2.5. Integration with Conventional Etch and Deposition
3. MARKET SIZE AND FORECAST, 2026-2032
3.1. Global Market Revenue
3.2. Annual Growth Analysis
3.3. Equipment, Chamber and Service Revenue
4. MARKET BY ETCH ARCHITECTURE
4.1. Plasma-Enhanced Atomic Layer Etching
4.2. Ion-Assisted Atomic Layer Etching
4.3. Thermal Atomic Layer Etching
4.4. Hybrid ALE / RIE
4.5. Cryogenic and Radical-Assisted ALE
4.6. Wet and Emerging Atomic-Precision Etch
5. MARKET BY MATERIAL
5.1. Silicon and Silicon-Based Films
5.2. Silicon Oxide and Low-k Dielectrics
5.3. Silicon Nitride
5.4. High-k and Metal Oxides
5.5. Metals and Conductors
5.6. GaN, AlGaN and III-V Materials
5.7. 2D and Emerging Materials
6. MARKET BY SEMICONDUCTOR APPLICATION
6.1. Advanced Logic and GAA Transistors
6.2. Interconnect and Low-k Patterning
6.3. DRAM
6.4. 3D NAND
6.5. Compound and Power Semiconductors
6.6. Photonics and Optoelectronics
6.7. Research and Emerging Devices
7. MARKET BY WAFER / PRODUCTION ENVIRONMENT
7.1. 300 mm High-Volume Manufacturing
7.2. 200 mm and Specialty Production
7.3. Research and Pilot Production
8. MARKET BY EQUIPMENT CONFIGURATION
8.1. Stand-Alone ALE Systems
8.2. ALE-Enabled Multi-Mode Etch Platforms
8.3. Cluster-Tool Integrated ALE
8.4. Research and Development Systems
9. REGIONAL MARKET
9.1. Asia Pacific
9.1.1. Taiwan
9.1.2. South Korea
9.1.3. Japan
9.1.4. China
9.1.5. Southeast Asia
9.2. North America
9.2.1. United States
9.3. Europe
9.4. Rest of World
10. MARKET DYNAMICS
10.1. Drivers
10.1.1. GAA and Advanced Logic Scaling
10.1.2. High-Layer Memory Structures
10.1.3. Low-Damage Compound-Semiconductor Etch
10.1.4. Atomic-Precision Pattern Transfer
10.2. Restraints
10.2.1. Low Throughput
10.2.2. Imperfect Self-Limiting Behavior
10.2.3. Particle and Chamber-Condition Effects
10.2.4. Process and Chemistry Complexity
11. COMPETITIVE LANDSCAPE
11.1. Market Structure and Competitive Intensity
11.2. High-Volume ALE-Enabled Etch Platforms
11.3. Dedicated ALE Equipment Suppliers
11.4. Compound-Semiconductor and Research Platforms
11.5. Process Integration and Customer Qualification
12. COMPANY PROFILES
13. RECENT DEVELOPMENTS
14. APPENDIX
Navigate
Trusted by the world's leading organizations











