
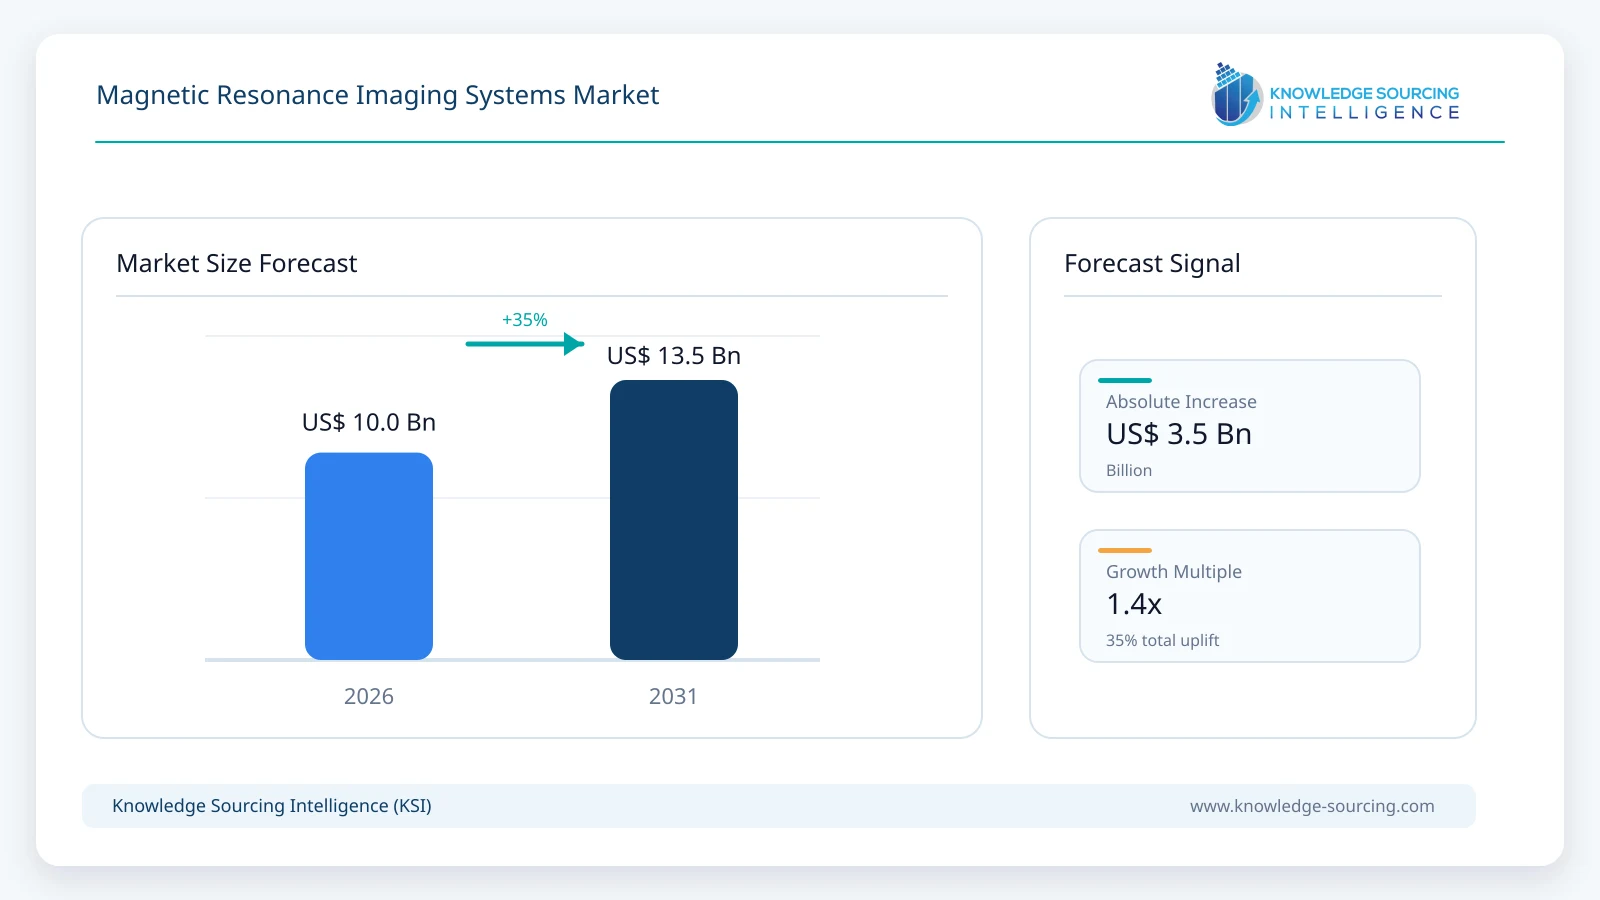
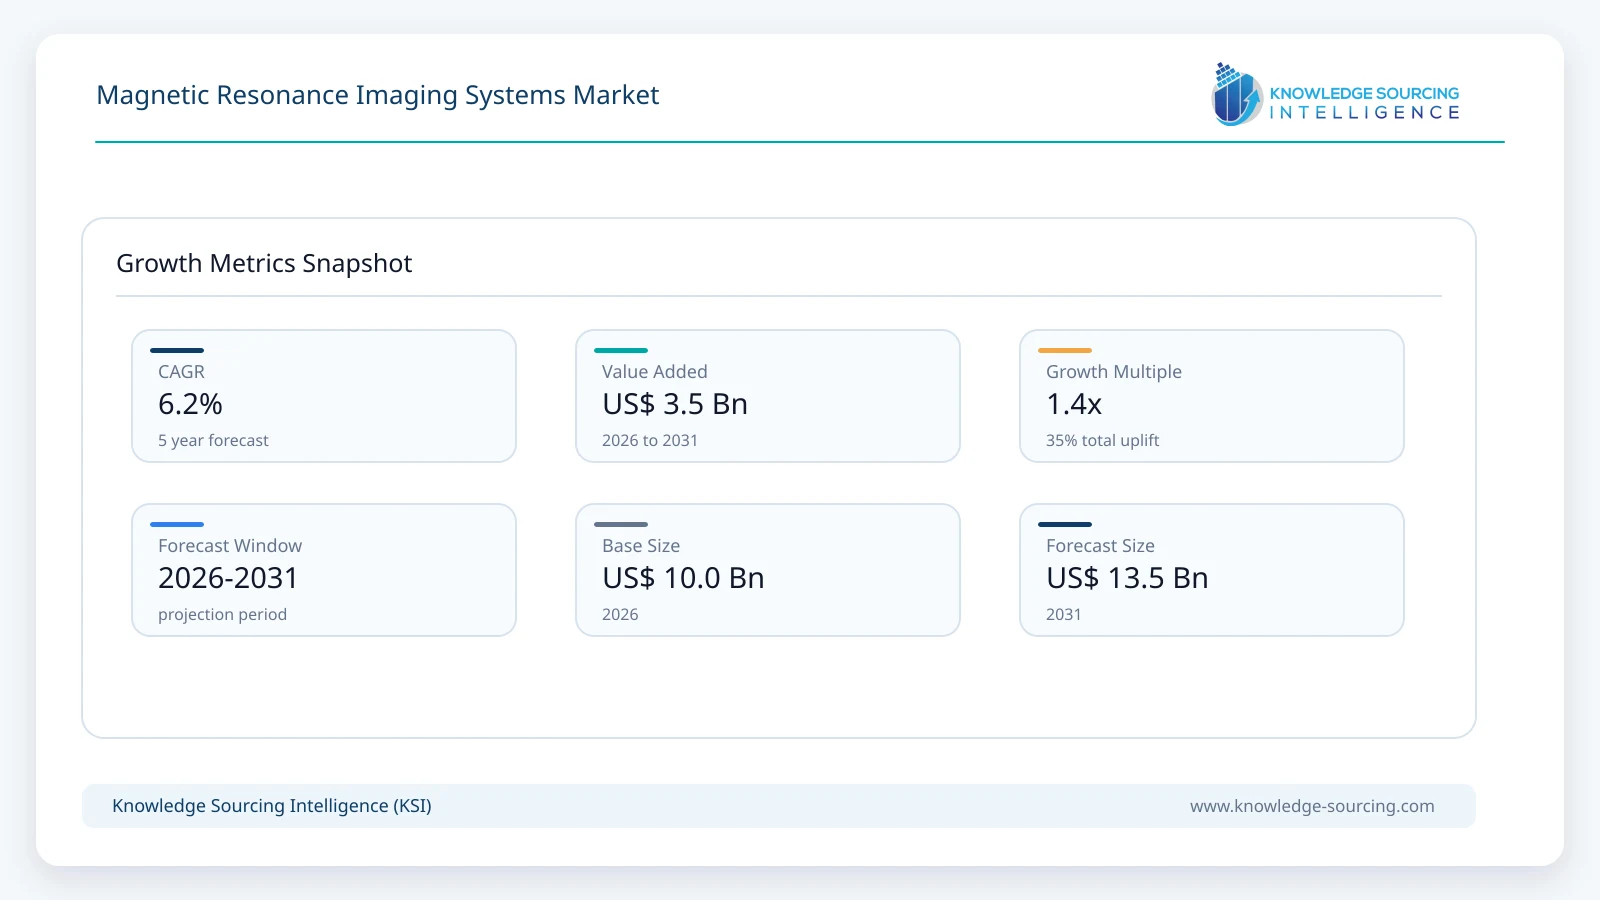
The Magnetic Resonance Imaging Systems Market is forecast to grow at a CAGR of 6.2%, reaching USD 13.5 billion in 2031 from USD 10.0 billion in 2026.
Highlights:
- 1Closed MRI systems account for approximately 81% of global MRI system revenue in 2026.
- 21.5T systems remain the largest field-strength segment because they balance clinical range, cost and throughput.
- 3North America contributes approximately 36% of 2026 market value, supported by replacement demand and advanced imaging intensity.
- 4Philips reports more than 2,220 BlueSeal MRI systems installed globally since 2018.
- 5Siemens received U.S. FDA clearance for the 70 cm helium-independent Magnetom Flow platform in January 2026.
- 6Portable MRI expanded commercially in 2026 through new European launches and clinical deployment in India.
Market Overview
MRI remains a core imaging modality for neurological, musculoskeletal, oncological, cardiovascular and abdominal diagnosis because it provides high soft-tissue contrast without ionizing radiation. The installed base is increasingly segmented between high-throughput 1.5T systems, advanced 3T scanners, specialized open and dedicated systems, and a new class of portable ultra-low-field devices. Conventional performance metrics such as field strength and gradient capability remain important, but hospital procurement decisions are now equally influenced by scan time, siting requirements, helium dependence, energy consumption and staff productivity.
Helium independence is becoming a mainstream system-design criterion. Philips states that more than 2,220 BlueSeal systems had been installed globally by April 2026 and that its sealed magnet architecture uses only 7 liters of helium, avoiding routine refills. Siemens Healthineers received FDA clearance in January 2026 for the 70 cm Magnetom Flow 1.5T platform using 0.7 liters of helium and no quench pipe. GE HealthCare is also developing its SIGNA Sprint with Freelium 1.5T system using less than 1% of the helium required by traditional magnets. Lower-helium designs reduce siting complexity and exposure to helium supply or refill costs, improving the economics of MRI expansion.
AI is simultaneously reshaping image reconstruction and scanner workflow. Siemens uses Deep Resolve for accelerated reconstruction, GE HealthCare integrates AIR Recon DL and related workflow tools, and Philips combines SmartSpeed with automated planning and emerging predictive MRI capabilities. Philips introduced the Titanion ultra-high-gradient 3T platform in May 2026 with 150 mT/m gradient strength and AI-based workflow, while GE used ISMRM 2026 to showcase advanced 3T and helium-free 1.5T systems. These developments shift competition from magnet specifications alone toward whole-exam productivity.
Market Trends
Helium-Free and Sealed-Magnet MRI Is Moving Into the Mainstream
Helium-free or near-helium-free magnet design has moved from a sustainability feature into an operational-resilience strategy. Conventional superconducting MRI systems can require large helium inventories, quench pipes and specialized siting. Philips BlueSeal, Siemens DryCool and GE Freelium architectures reduce this dependency substantially. Siemens states that Magnetom Flow can reduce annual energy use by up to 56% versus previous-generation systems, while Philips reports more than six million liters of helium saved across its BlueSeal installed base. The commercial effect is strongest where hospitals face difficult installation environments, mobile imaging requirements or high service costs.
AI Reconstruction Is Increasing Scanner Throughput Rather Than Replacing Hardware
AI is most commercially important when it improves utilization of the scanner itself. Deep-learning reconstruction can reduce scan times, enhance signal-to-noise performance and support more consistent imaging across patients. Philips' SmartSpeed platform, Siemens Deep Resolve and GE AIR Recon DL are increasingly embedded within system sales and upgrade paths. The next stage is greater automation of patient positioning, protocol planning and quality control. Philips is working with NVIDIA on predictive MRI preview and foundation-model approaches intended to support more autonomous scan planning, indicating that workflow AI is becoming part of the core scanner value proposition.
Portable and Ultra-Low-Field MRI Is Expanding Access to New Care Settings
Portable MRI does not replace conventional 1.5T and 3T scanners across full diagnostic workloads, but it creates new imaging occasions at the bedside, in emergency care and in neurology workflows where moving the patient is difficult. Hyperfine's Swoop system expanded internationally during 2026, including clinical use at AIIMS New Delhi, CE and UKCA approvals and a European commercial launch. In August 2026, the company received FDA clearance for an additional Optive AI software update. The category therefore represents an access-expansion pathway rather than a direct substitute for high-field MRI.
3T MRI Is Moving Toward Quantitative and High-Gradient Imaging
Three-tesla MRI remains the advanced clinical and research tier for detailed neuroimaging, oncology, cardiac and musculoskeletal applications. Product development is shifting toward higher gradient performance, faster diffusion imaging and quantitative biomarkers rather than field strength alone. Philips' Titanion 3T platform targets microstructural and biomarker imaging using 150 mT/m gradients, while GE and Siemens continue to expand advanced 3T portfolios. Higher-performance 3T systems remain more expensive and infrastructure-intensive than 1.5T, so their adoption is concentrated in tertiary hospitals, academic centers and advanced imaging networks.
Market Drivers
Aging Installed Equipment Creates a Recurring Replacement Cycle
MRI systems have long operating lives, but advances in gradient performance, energy efficiency, software and magnet design are increasing the economic case for replacement. Older systems can require higher helium inventory, greater power consumption and more manual workflow. New systems reduce these operating burdens while increasing throughput, which allows hospitals to justify replacement even where scan volumes are already high. Upgradeable platforms and software-driven performance improvements also let manufacturers capture spending from installed customers without requiring complete equipment replacement every time.
Neurology and Musculoskeletal Imaging Sustain High Procedure Demand
Brain, spine and musculoskeletal imaging remain high-volume MRI applications because of the modality's soft-tissue contrast and lack of ionizing radiation. Neurological disease, stroke evaluation, degenerative spine conditions, sports injuries and orthopedic treatment planning create recurring demand across hospitals and diagnostic centers. Portable MRI is extending neurological imaging into additional care environments, while high-gradient and AI-assisted systems improve the speed and detail of complex exams.
Siting and Workflow Improvements Expand Access Beyond Large Academic Centers
Compact footprints, sealed magnets, lower energy requirements and AI-assisted operation make MRI more practical for community hospitals, outpatient centers and mobile imaging. Siemens' 0.7-liter helium platforms and Philips' BlueSeal systems reduce the need for conventional quench infrastructure, while portable ultra-low-field devices remove many siting constraints entirely. These changes broaden the potential installed base in regions where conventional MRI infrastructure or specialist staffing has historically limited access.
Market Restraints
High Capital Cost, Installation Requirements and Workforce Constraints Limit Faster Expansion
MRI remains one of the most capital-intensive diagnostic imaging modalities. Scanner acquisition, shielding, site preparation, coils, maintenance and specialist staffing create substantial total cost of ownership. High-field systems also require more complex infrastructure and trained technologists. AI and sealed-magnet designs reduce some operational burden but do not eliminate the need for radiologists, physicists and service support. Reimbursement pressure can further slow replacement decisions in mature markets, particularly where existing scanners are already highly utilized and clinically adequate.
Segment Analysis
By Architecture - Closed MRI Systems
Closed MRI systems are estimated at approximately USD 8.1 billion in 2026 and remain the dominant architecture. They support the broadest range of 1.5T and 3T applications and offer high image quality, strong gradient performance and established coil ecosystems. Open MRI remains important for claustrophobic, bariatric and selected orthopedic patients, while portable MRI is expected to grow faster from a small base because it creates new point-of-care imaging settings rather than competing directly across full-body diagnostics.
By Field Strength - 1.5T MRI
1.5T systems are estimated at approximately USD 5.5 billion in 2026 and represent the largest field-strength segment. They provide a strong balance between acquisition cost, clinical versatility, image quality, throughput and infrastructure requirements. The latest helium-independent product launches from Siemens and GE are reinforcing the segment. 3T systems command higher average selling values and are growing in advanced clinical and research settings, while ultra-low and low-field platforms gain relevance through portable and specialty imaging.
By Application - Brain and Neurological Imaging
Brain and neurological imaging is estimated at approximately USD 3.1 billion in 2026 and remains the largest application. MRI is central to evaluation of tumors, multiple sclerosis, stroke, neurodegeneration and structural abnormalities, and advanced diffusion and functional techniques further strengthen its role. Musculoskeletal and spine imaging form another large application base, while cardiac MRI is gaining importance as AI-assisted planning and faster sequences reduce workflow complexity.
By End User - Hospitals
Hospitals are estimated to account for approximately USD 7.2 billion of MRI system revenue in 2026. Large hospitals operate the most diverse MRI fleets and account for a high share of 3T and advanced specialty systems because they handle complex neurological, oncological, cardiac and emergency cases. Diagnostic imaging centers remain an important secondary market and can benefit disproportionately from high-throughput 1.5T systems, compact siting and workflow automation because equipment utilization directly affects operating margins.
By Geography - North America
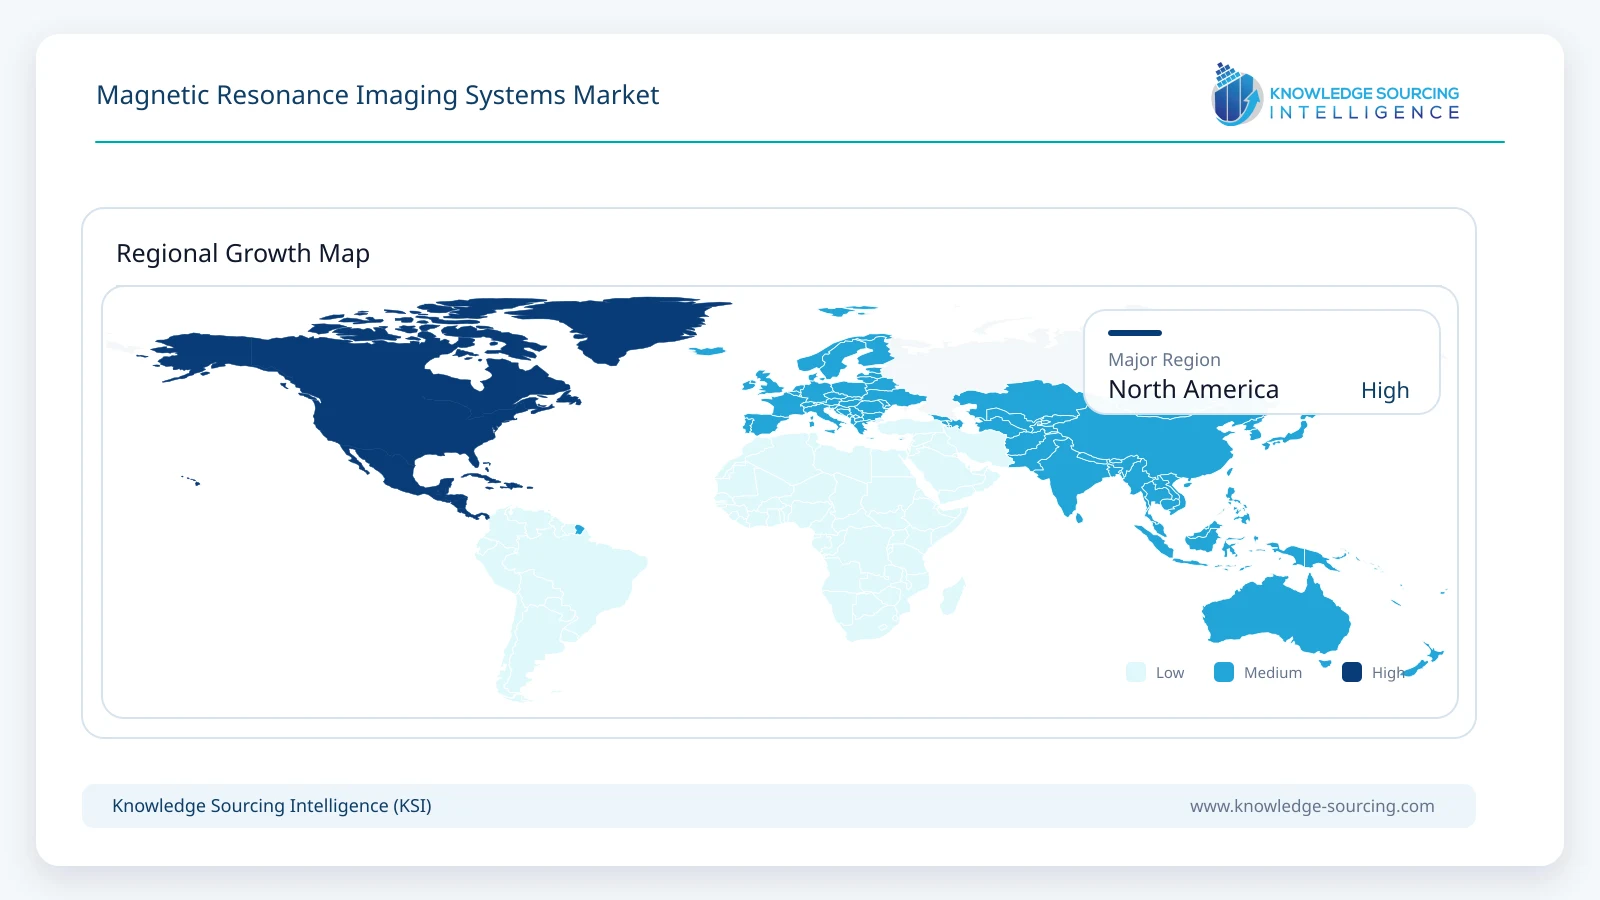
North America is estimated at approximately USD 3.6 billion in 2026 and remains the largest regional market. The United States combines high imaging intensity, a large installed base, strong replacement spending and early adoption of AI-enabled and portable MRI systems. Europe remains a major market for helium-free MRI and advanced 3T platforms, while Asia Pacific is expected to grow faster as China, India and Southeast Asia add imaging capacity and expand local manufacturing. India's first routine bedside use of Hyperfine's portable MRI at AIIMS New Delhi in 2026 illustrates the region's increasing adoption of alternative deployment models.
Competitive Environment
The MRI systems market is led by Siemens Healthineers, GE HealthCare, Philips and Canon Medical, supported by broad service organizations, installed bases and complete radiology portfolios. United Imaging has expanded internationally with high-field MRI and integrated imaging platforms, while Fujifilm Healthcare and Esaote compete across conventional and specialty systems. Competition increasingly centers on magnet design, AI workflow, scan acceleration, siting flexibility and total cost of ownership rather than field strength alone.
A second group of companies is expanding MRI into specialized settings. Hyperfine focuses on portable ultra-low-field brain imaging, Bruker leads in preclinical and research MRI, and MR Solutions and Aspect Imaging serve preclinical, veterinary and specialized imaging niches. FONAR remains active in open and upright MRI, while neuro42 is developing portable neuroimaging systems. The market therefore combines a concentrated full-body clinical segment with smaller specialist categories where portability or dedicated design can overcome the limitations of conventional fixed scanners.
Recent Developments
August 2026: Hyperfine received FDA clearance for its latest Optive AI software update for the next-generation Swoop portable MRI system.
July 2026: Hyperfine launched the next-generation Swoop system commercially in initial European markets following CE and UKCA approval.
May 2026: Philips introduced the Titanion ultra-high-gradient 3T MRI platform with 150 mT/m gradient strength and AI-enabled workflow.
May 2026: GE HealthCare showcased next-generation SIGNA MRI technology including helium-free 1.5T and advanced 3T platforms at ISMRM 2026.
April 2026: AIIMS New Delhi initiated routine clinical use of the Hyperfine Swoop system, becoming the first hospital in India to deploy bedside MRI.
January 2026: Siemens Healthineers received U.S. FDA clearance for the 70 cm Magnetom Flow 1.5T helium-independent MRI platform.
Magnetic Resonance Imaging Systems Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 10.0 billion |
| Total Market Size in 2031 | USD 13.5 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Architecture, Field Strength, Application, End User, Geography |
| Companies |
|
Market Segmentation
By Architecture
Closed MRI Systems
Open MRI Systems
Portable / Point-of-Care MRI
By Field Strength
Ultra-Low and Low Field (Below 1.5T)
1.5T
3T
Ultra-High Field (Above 3T)
By Application
Brain and Neurological Imaging
Spine and Musculoskeletal Imaging
Cardiac Imaging
Pelvic and Abdominal Imaging
Breast Imaging
Vascular Imaging
Others
By End User
Hospitals
Diagnostic Imaging Centers
Research and Other Care Settings
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East & Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Aging Installed Equipment Creates a Recurring Replacement Cycle
3.1.2. Neurology and Musculoskeletal Imaging Sustain High Procedure Demand
3.1.3. Siting and Workflow Improvements Expand Access Beyond Large Academic Centers
3.2. Market Restraints
3.2.1. High Capital Cost, Installation Requirements and Workforce Constraints Limit Faster Expansion
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Helium-Free and Sealed-Magnet MRI
4.2. AI Reconstruction and Workflow Automation
4.3. High-Gradient and Quantitative 3T Imaging
4.4. Portable and Ultra-Low-Field MRI
4.5. Advanced Coils and Patient-Centric System Design
4.6. Functional, Diffusion and Quantitative MRI
5. MAGNETIC RESONANCE IMAGING SYSTEMS MARKET BY ARCHITECTURE
5.1. Introduction
5.2. Closed MRI Systems
5.3. Open MRI Systems
5.4. Portable / Point-of-Care MRI
6. MAGNETIC RESONANCE IMAGING SYSTEMS MARKET BY FIELD STRENGTH
6.1. Introduction
6.2. Ultra-Low and Low Field (Below 1.5T)
6.3. 1.5T
6.4. 3T
6.5. Ultra-High Field (Above 3T)
7. MAGNETIC RESONANCE IMAGING SYSTEMS MARKET BY APPLICATION
7.1. Introduction
7.2. Brain and Neurological Imaging
7.3. Spine and Musculoskeletal Imaging
7.4. Cardiac Imaging
7.5. Pelvic and Abdominal Imaging
7.6. Breast Imaging
7.7. Vascular Imaging
7.8. Others
8. MAGNETIC RESONANCE IMAGING SYSTEMS MARKET BY END USER
8.1. Introduction
8.2. Hospitals
8.3. Diagnostic Imaging Centers
8.4. Research and Other Care Settings
9. MAGNETIC RESONANCE IMAGING SYSTEMS MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. USA
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Italy
9.4.5. Spain
9.4.6. Others
9.5. Middle East & Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Australia
9.6.6. Indonesia
9.6.7. Thailand
9.6.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Magnet, Field-Strength and Workflow Positioning
10.3. AI, Software and Upgrade Strategy
10.4. Product Launches, Regulatory Clearances and Partnerships
10.5. Competitive Dashboard
11. COMPANY PROFILES
11.1. Siemens Healthineers AG
11.2. GE HealthCare Technologies Inc.
11.3. Koninklijke Philips N.V.
11.4. Canon Medical Systems Corporation
11.5. United Imaging Healthcare Co., Ltd.
11.6. FUJIFILM Healthcare Corporation
11.7. Esaote S.p.A.
11.8. Hyperfine, Inc.
11.9. Bruker Corporation
11.10. Neusoft Medical Systems Co., Ltd.
11.11. AllTech Medical Systems Co., Ltd.
11.12. Time Medical Systems
11.13. MR Solutions Ltd.
11.14. FONAR Corporation
11.15. neuro42, Inc.
11.16. Aspect Imaging Ltd.
11.17. Aurora Healthcare US Corp.
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











