
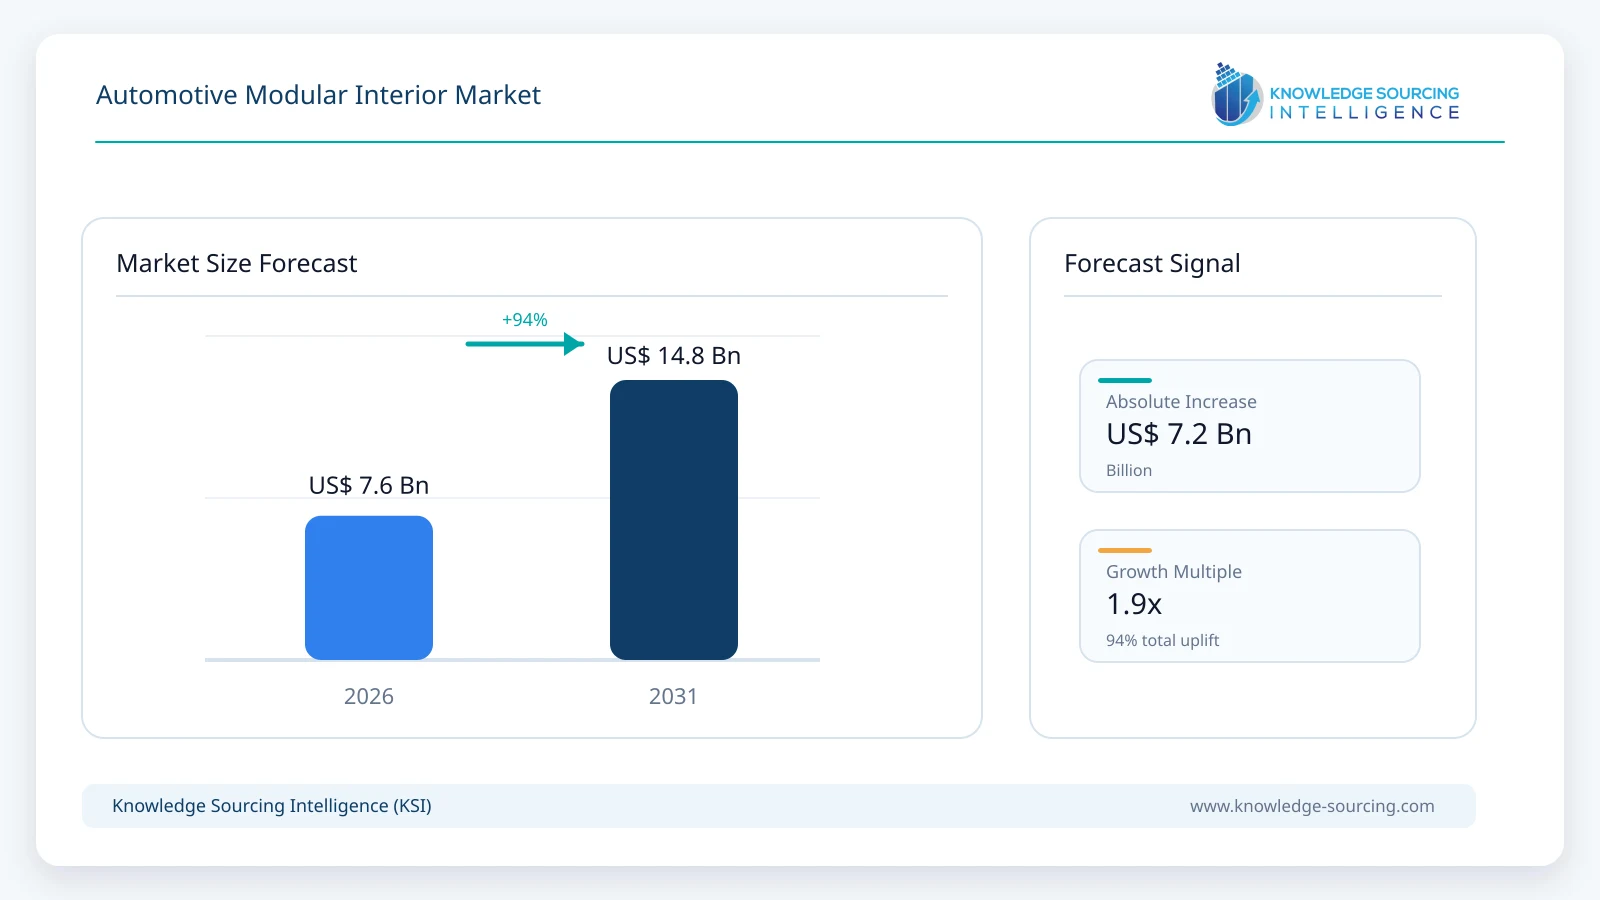
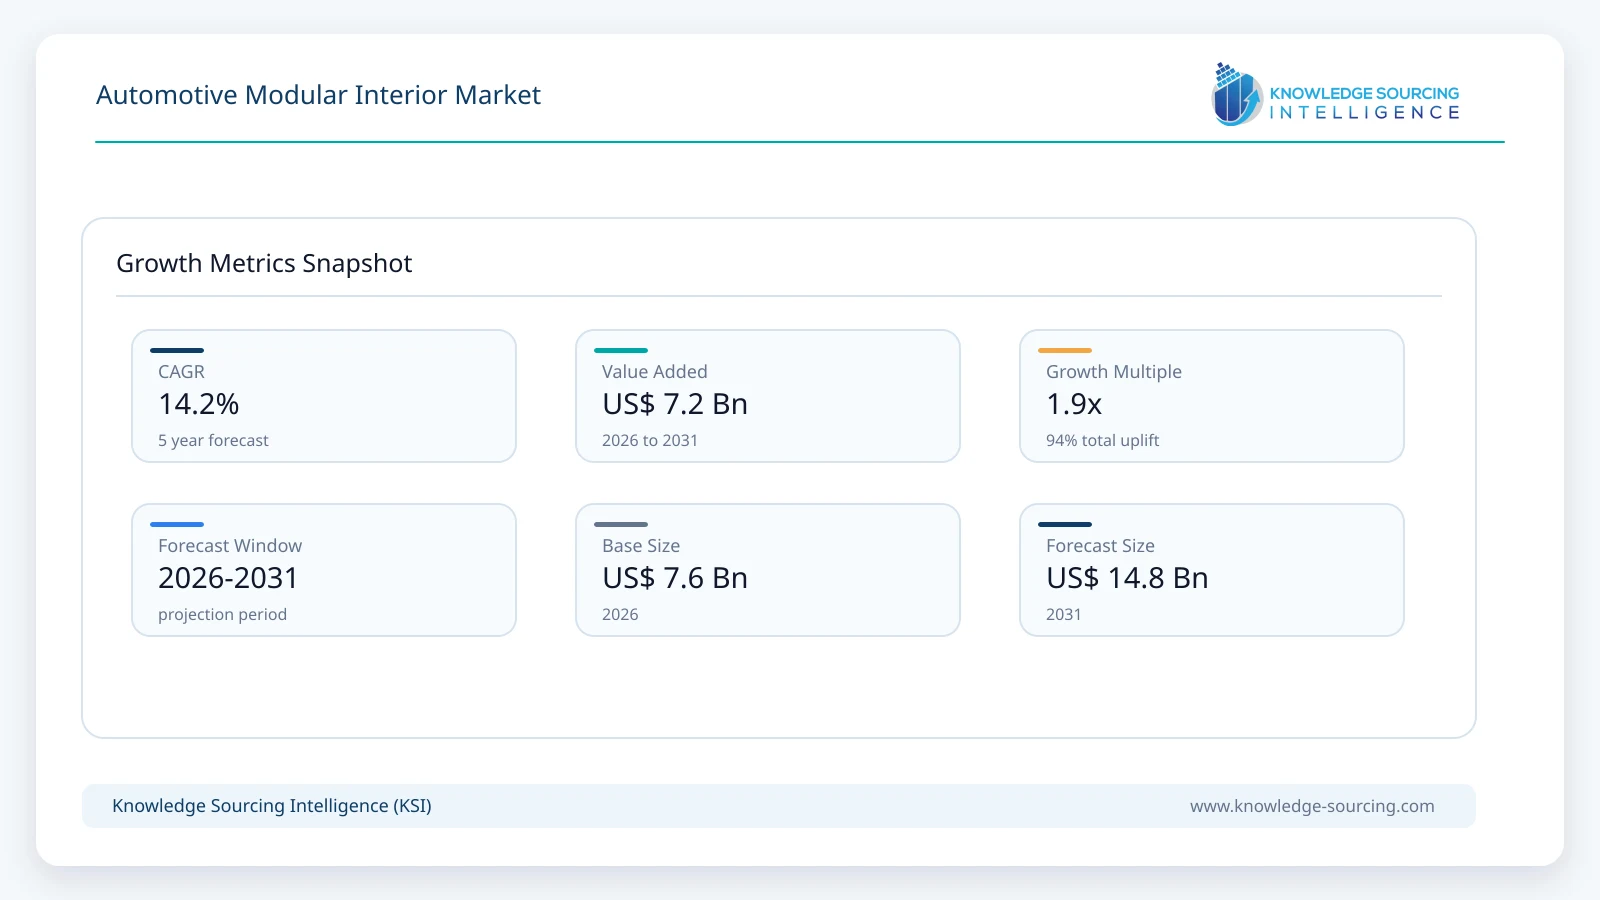
The automotive modular interior market is forecast to grow at a CAGR of 14.2%, reaching approximately USD 14.75 billion in 2031 from USD 7.60 billion in 2026.
Highlights:
- 1Modular seating and rail systems account for approximately 42% of global market value in 2026, reflecting the high value of long rails, swivel mechanisms, modular seat structures and reconfigurable seat platforms.
- 2Front and cockpit-zone modular systems represent approximately 46% of market value in 2026 because consoles, instrument panels, storage modules and front-seat architectures receive modular integration earlier than rear-cabin systems.
- 3Configurable and interchangeable module architectures account for approximately 61% of market value in 2026, supported by plug-and-play consoles, modular seat components and standardized trim or functional interfaces.
- 4Passenger vehicles represent approximately 96% of global market value in 2026, led by SUVs, crossovers, MPVs, premium sedans and electric vehicles with increasingly flexible interiors.
- 5Battery electric vehicles account for approximately 37% of market value in 2026 as flat floors, centralized electronics and flexible packaging increase the value of modular cabin architectures.
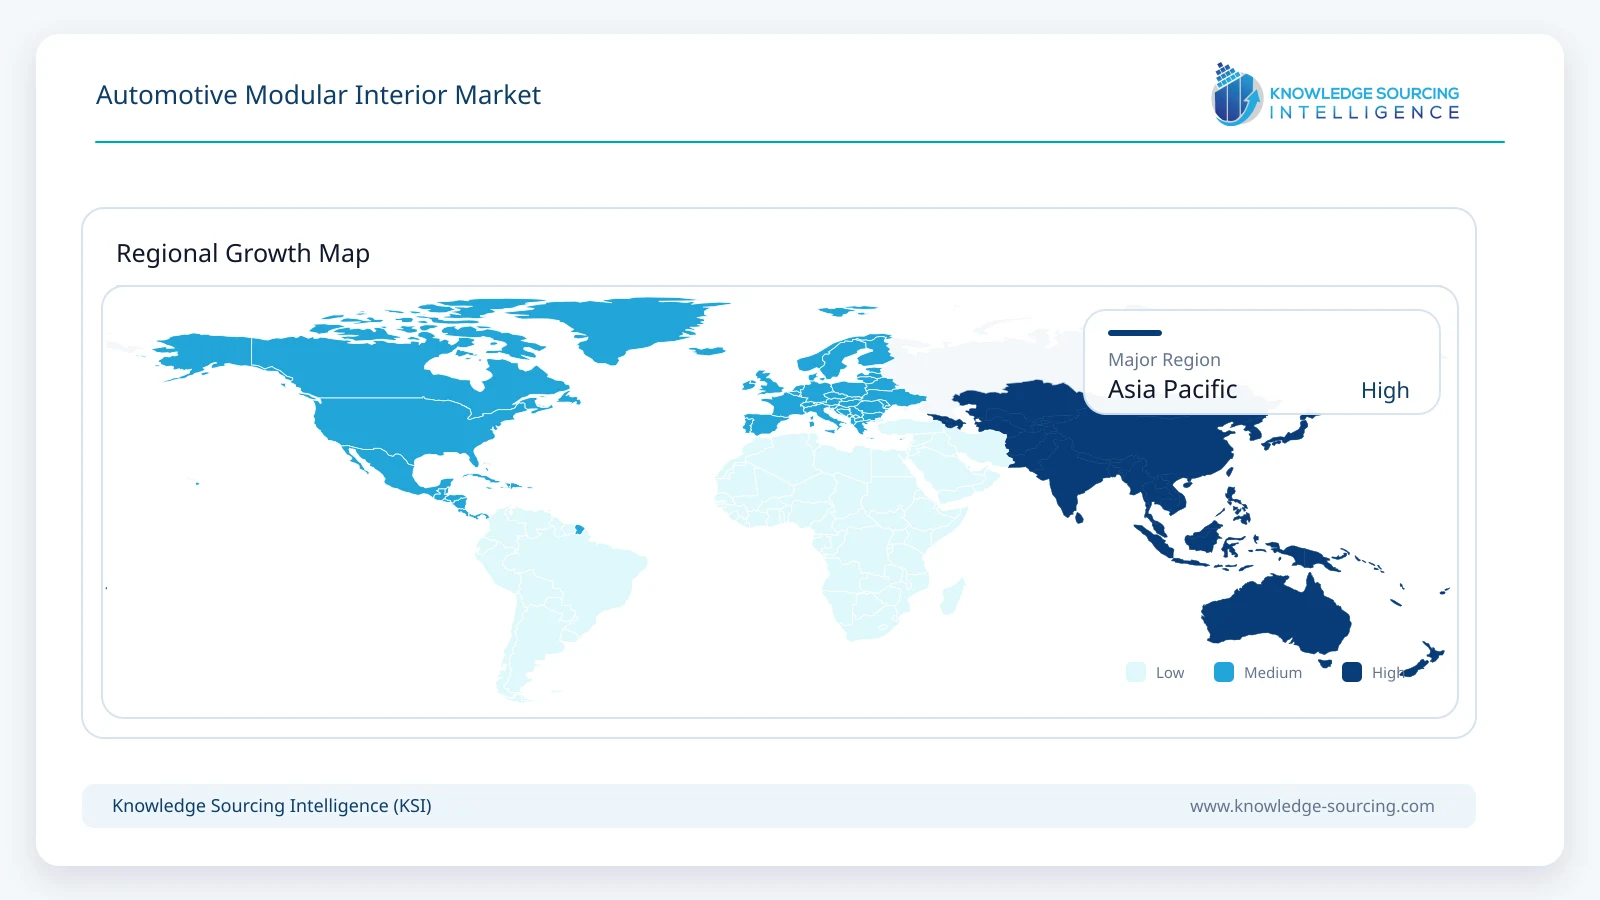
- 6Asia Pacific represents approximately 47% of global market value in 2026, supported by rapid EV growth and strong smart-cabin development in China, Japan and South Korea.
Demand is being driven by vehicle interiors that can be customized, upgraded or reconfigured through common seat, console, cockpit, storage and trim architectures rather than fixed one-purpose cabin layouts.
The strongest commercial activity is occurring in modular seating, long-rail systems and center-console platforms. Magna is applying reusable building blocks across reconfigurable seating, FORVIA has introduced a plug-and-play On-demand center console, and Yanfeng's XiM27 combines modular seating, a mobile floor console and centralized cabin control within a production-ready smart-cabin platform.
Modularity is also expanding into coordinated whole-cabin concepts. Toyota Boshoku's LOUNZE+ links seats, door trims and the center console so the cabin can adapt to different purposes, while Antolin is integrating smart surfaces, door functions and HMI into customizable interior systems. These developments are increasing the strategic value of modularity as both a manufacturing architecture and a customer-experience feature.
Market Overview
Modular automotive interiors are designed around standardized interfaces that allow selected cabin components to be exchanged, repositioned or configured without redesigning the complete interior. The approach can be applied at component level, such as an interchangeable center-console module, or at system level, such as long-rail seating and coordinated interior layouts.
FORVIA's On-demand center console demonstrates component-level modularity. Its MoodPlug interface combines mechanical, electrical, signal, power and data connections in a tool-free architecture, allowing modules such as tray tables, storage, refrigerators and retractable displays to be added without structural modifications.
Yanfeng's XiM27 demonstrates wider system-level modularity. The cabin includes configurable seating, a multifunctional mobile floor console, a large display and centralized electronics that allow rapid switching between driving, lounge, family, rest and cargo scenarios. The platform is designed as a production-ready smart-cabin architecture rather than a static concept.
Toyota Boshoku is developing similar coordinated interior concepts. Its LOUNZE+ system links seats, door trims and the console so interior components can operate together according to the selected scene, while the earlier Future Creation Modular Seat used interchangeable structural configurations to support advanced, relaxed and sporty seating modes.
Market Trends
Modular Interiors Are Shifting from Individual Components to Shared Cabin Architectures
Interior suppliers are increasingly designing common hardware foundations that can support multiple cabin layouts and use cases. Magna's Flexible Seating System uses long-travel rails, rotating bases and support structures as reusable building blocks that can be configured differently across vehicle programs.
This approach allows automakers to reduce the number of unique components while still offering differentiated cabin experiences across trims, body styles and regional vehicle programs.
Plug-and-Play Consoles Are Creating Upgradeable Cabin Features
Center consoles are becoming a major modular-interior platform because they can combine storage, charging, displays, work surfaces, beverage functions and climate-related features in a compact location. FORVIA's On-demand center console allows modules to be changed without redesigning the main console structure.
Upgradeable console systems can support post-sale personalization and reduce the need to replace complete interior assemblies when functions change over the vehicle life cycle.
Electric Vehicles Are Increasing Spatial Modularity
Battery-electric platforms create flatter floors and reduce some drivetrain intrusions, allowing longer seat rails, movable consoles and more dramatic changes in interior layout. This makes modular interior architecture especially attractive for electric SUVs, MPVs and premium vehicles.
The combination of flat-floor packaging and centralized electronics also simplifies coordination between movable hardware and software-controlled cabin modes.
Smart Surfaces Are Becoming Modular Functional Layers
Interior trim is increasingly being used as a functional interface rather than a fixed decorative surface. Antolin is integrating HMI, smart glazing, E-Ink and touch-responsive surfaces into door and cockpit systems, while Yanfeng and FORVIA combine sensing, lighting and display functions with interior components.
This trend allows OEMs to vary digital and interactive content on common physical structures, increasing modularity at the software and functional-surface level.
Circularity Is Increasing the Appeal of Replaceable Modules
Modular interiors can support repair, refurbishment and component upgrades without replacing complete assemblies. FORVIA positions its modular console around reuse and lifecycle extension, while suppliers are also increasing recyclable and lower-carbon materials in seat, console and trim structures.
The ability to separate functional modules from longer-life structural components can support lower material consumption and improve end-of-life recovery.
Segment Analysis
By Modular System Type: Seating and Rail Modules
Modular seating and rail systems are projected to reach approximately USD 5.610 billion by 2031. Growth is being supported by long-rail architectures, swivel mechanisms, interchangeable seat components and reconfigurable platforms that allow a common structure to support passenger, cargo, lounge and work-related cabin modes.
By Interior Zone: Front and Cockpit Zone
Front and cockpit-zone modular systems are projected to reach approximately USD 6.200 billion by 2031. Center consoles, instrument panels, front-seat structures and smart functional surfaces provide strong opportunities for modularity because they combine high feature content with frequent trim and technology differentiation.
By Modularity Approach: Configurable and Interchangeable Modules
Configurable and interchangeable module architectures are projected to reach approximately USD 8.110 billion by 2031. These systems allow automakers or users to change selected features, materials or functions without redesigning the complete interior, supporting faster customization and lower program complexity.
By Vehicle Type: Passenger Vehicles
Passenger vehicles are projected to generate approximately USD 14.010 billion of modular-interior market value by 2031. SUVs, crossovers, MPVs and premium electric vehicles provide the largest demand base because flexible seating, storage and cockpit personalization are increasingly important purchase differentiators.
By Propulsion: Battery Electric Vehicles
Battery electric vehicles are projected to generate approximately USD 6.640 billion of modular-interior market value by 2031. EV platforms support flatter floors, centralized electronics and more flexible cabin packaging, making them the principal architecture for reconfigurable seating, movable consoles and software-linked interior systems.
By Geography: Asia Pacific
Asia Pacific is projected to reach approximately USD 7.520 billion by 2031. China is the principal growth engine through rapid EV and smart-cabin development, while Japan and South Korea contribute established seating, trim and interior-system engineering capabilities.
Market Drivers
Need to Reduce Interior Development Complexity
Automakers are managing more vehicle variants, regional specifications and trim combinations. Modular interior architectures allow common structures and interfaces to be reused while selected features are varied at module level.
Growth of Electric and Flexible Cabin Platforms
Electric vehicles provide greater freedom in floor design and electronic integration, supporting long rails, movable interior components and more flexible seat-console relationships. This expands the commercial value of modular cabin systems.
Increasing Demand for Personalization
Consumers increasingly expect vehicles to adapt to different users and activities. Interchangeable modules, configurable storage, smart surfaces and movable seating allow the cabin to change without requiring a completely different vehicle architecture.
Software-Defined Cabin Development
Centralized vehicle electronics are making it easier to coordinate seating, climate, lighting, displays and movable modules through software. This strengthens modularity by allowing common hardware to support multiple digital experiences.
Sustainability and Lifecycle Extension
Replaceable and upgradeable modules can extend interior component life and reduce waste. Modular designs also support repair and refurbishment strategies that separate damaged or outdated functional units from longer-life structural components.
Market Restraints
Interface Standardization Challenges
Modular components require reliable mechanical, electrical and data interfaces. Differences in packaging, voltage, communication protocols and safety requirements can reduce the degree of interchangeability across vehicle platforms.
Higher Upfront Engineering Cost
Developing a common modular architecture requires substantial early engineering to ensure that the base system can support multiple future configurations. The economic benefit depends on sufficient reuse across vehicle volumes.
Crash and Safety Validation Complexity
Movable seats, consoles and interior modules must remain secure during a crash and must not interfere with airbags, occupant sensing or restraint systems. More configurations increase the number of conditions that require validation.
Packaging and Weight Trade-Offs
Rails, interfaces, attachment systems and movable hardware can increase mass or consume cabin space. Suppliers must balance flexibility with lightweighting and packaging efficiency.
Complex Supply-Chain Coordination
Modular interiors can involve seating, electronics, HMI, trim, storage and climate components from multiple suppliers. Poorly defined interfaces can shift complexity upstream rather than eliminating it.
Regional Outlook
Asia Pacific
Asia Pacific is the largest regional market and is expected to remain the strongest growth centre through 2031. China is driving commercialization through rapid EV development, strong competition around smart-cabin experience and faster adoption of reconfigurable interiors.
Yanfeng's XiM27 combines modular seating, a multifunctional mobile console and centralized cabin control in a production-ready architecture. Toyota Boshoku's LOUNZE+ and Future Creation Modular Seat demonstrate continued investment in coordinated and customizable interior systems, while Magna has already secured Chinese production business for reconfigurable seating.
Europe
Europe is the second major regional market, supported by strong premium-vehicle production, software-defined vehicle development and a major supplier base in modular consoles, smart surfaces and interior structures.
FORVIA's On-demand center console provides a clear European example of plug-and-play modularity, while Antolin is advancing customizable cockpit, door and smart-surface technologies. European OEM focus on sustainability and lifecycle design is also increasing interest in replaceable, repairable and upgradeable interior modules.
Competitive Landscape
The automotive modular interior market is led by suppliers with capabilities across seating, consoles, cockpit systems, door trims, smart surfaces and integrated cabin electronics. Yanfeng, FORVIA, Toyota Boshoku, Magna, Antolin and Adient are directly involved in modular, configurable or reconfigurable interior technologies.
Yanfeng differentiates through complete smart-cabin integration, combining seating, movable consoles and centralized electronics. FORVIA has a strong position in modular console and interior-surface systems, while Toyota Boshoku links seats, trims, consoles and controls within coordinated mobility-space concepts.
Magna focuses on modular reconfigurable seating and long-rail systems, Antolin develops customizable cockpit, door and functional-surface technologies, and Adient uses modular seat platforms such as ModuGo to support common structures with configurable comfort and material options.
Recent Developments
10 July 2026: Yanfeng's XiM27 received the 2026 Red Dot Design Concept Award, recognizing a platform that uses intelligent seat configuration, a multifunctional mobile console and adaptive interior systems for higher-level autonomous mobility.
29 June 2026: Yanfeng unveiled XiM27, a production-ready smart-cabin platform integrating centralized electronics, configurable seating, a mobile floor console and flexible passenger-space layouts.
18 June 2026: Magna detailed its Flexible Seating System, using long-travel rails, rotating bases and common support structures as modular building blocks that can be reused across vehicle programs.
16 April 2026: Toyota Boshoku announced LOUNZE+ for Auto China 2026, integrating seats, door trims and the center console so the cabin can adapt to different purposes and scenes.
30 October 2025: FORVIA introduced its On-demand center console, a furniture-inspired modular interior platform using a standardized tool-free interface for interchangeable storage, tray, refrigerator and display modules.
25 August 2025: Adient announced the ModuGo seat, a modular seating architecture supporting structural customization, materials selection and smart comfort features from a common platform.
Market Outlook
The automotive modular interior market is expected to expand strongly through 2031 as OEMs move from fixed cabin layouts toward common architectures that can support multiple functions, trims and use cases. Modular seating and rail systems will remain the largest value pool, while consoles, cockpit modules and functional surfaces are expected to gain share.
The next stage of development will focus on standardized mechanical and electrical interfaces, software-controlled reconfiguration and upgradeable modules that can be repaired or replaced independently. Interior modularity will increasingly become a platform strategy rather than a collection of isolated components.
Asia Pacific is expected to lead commercialization, while Europe remains a major centre for premium modular interiors, smart surfaces and circular design. Competitive advantage will depend on interface standardization, packaging efficiency, software integration, safety validation and the ability to reuse common interior building blocks across multiple vehicle programs.
Automotive Modular Interior Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 7.60 billion |
| Total Market Size in 2031 | USD 14.75 billion |
| Forecast Unit | Billion |
| Growth Rate | 14.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Modular System Type, Interior Zone, Modularity Approach, Vehicle Type, Propulsion, Geography |
| Companies |
|
Market Segmentation
By Modular System Type
Seating and Rail Modules
Center Console and Storage Modules
Cockpit and Instrument Panel Modules
Door and Trim Modules
Functional and HMI Modules
By Interior Zone
Front and Cockpit Zone
Rear and Passenger Cabin
Whole-Cabin Integrated Systems
By Modularity Approach
Configurable and Interchangeable Modules
Reconfigurable and Movable Systems
By Vehicle Type
Passenger Vehicles
Light Commercial Vehicles
Medium and Heavy Commercial Vehicles
By Propulsion
Internal Combustion Engine Vehicles
Hybrid Electric Vehicles
Battery Electric Vehicles
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
South Korea
India
Indonesia
Thailand
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Research
2.4. Market Estimation
2.5. Segment Modelling
2.6. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Automotive Modular Interior Market Size, 2026-2031
3.3. Modular System Type Outlook
3.4. Interior Zone Outlook
3.5. Modularity Approach Outlook
3.6. Vehicle Type Outlook
3.7. Propulsion Outlook
3.8. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Need to Reduce Interior Development Complexity
4.1.2. Growth of Electric and Flexible Cabin Platforms
4.1.3. Increasing Demand for Personalization
4.1.4. Software-Defined Cabin Development
4.1.5. Sustainability and Lifecycle Extension
4.2. Market Restraints
4.2.1. Interface Standardization Challenges
4.2.2. Higher Upfront Engineering Cost
4.2.3. Crash and Safety Validation Complexity
4.2.4. Packaging and Weight Trade-Offs
4.2.5. Complex Supply-Chain Coordination
4.3. Market Opportunities
4.4. Porter's Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Modular Interior Platform Economics
4.7. Safety and Regulatory Environment
5. TECHNOLOGY OUTLOOK
5.1. Long-Rail and Reconfigurable Seating
5.2. Swivel and Movable Seat Bases
5.3. Modular Center Consoles
5.4. Interchangeable Storage and Lifestyle Modules
5.5. Modular Instrument Panels and Cockpit Structures
5.6. Smart Door and Trim Modules
5.7. Functional and Interactive Surfaces
5.8. Standardized Power and Data Interfaces
5.9. Centralized Cabin Control
5.10. Circular and Upgradeable Interior Architectures
6. AUTOMOTIVE MODULAR INTERIOR MARKET BY MODULAR SYSTEM TYPE
6.1. Introduction
6.2. Seating and Rail Modules
6.3. Center Console and Storage Modules
6.4. Cockpit and Instrument Panel Modules
6.5. Door and Trim Modules
6.6. Functional and HMI Modules
7. AUTOMOTIVE MODULAR INTERIOR MARKET BY INTERIOR ZONE
7.1. Introduction
7.2. Front and Cockpit Zone
7.3. Rear and Passenger Cabin
7.4. Whole-Cabin Integrated Systems
8. AUTOMOTIVE MODULAR INTERIOR MARKET BY MODULARITY APPROACH
8.1. Introduction
8.2. Configurable and Interchangeable Modules
8.3. Reconfigurable and Movable Systems
9. AUTOMOTIVE MODULAR INTERIOR MARKET BY VEHICLE TYPE
9.1. Introduction
9.2. Passenger Vehicles
9.3. Light Commercial Vehicles
9.4. Medium and Heavy Commercial Vehicles
10. AUTOMOTIVE MODULAR INTERIOR MARKET BY PROPULSION
10.1. Introduction
10.2. Internal Combustion Engine Vehicles
10.3. Hybrid Electric Vehicles
10.4. Battery Electric Vehicles
11. AUTOMOTIVE MODULAR INTERIOR MARKET BY GEOGRAPHY
11.1. North America
11.1.1. United States
11.1.2. Canada
11.1.3. Mexico
11.2. South America
11.2.1. Brazil
11.2.2. Argentina
11.2.3. Others
11.3. Europe
11.3.1. Germany
11.3.2. United Kingdom
11.3.3. France
11.3.4. Italy
11.3.5. Spain
11.3.6. Others
11.4. Middle East and Africa
11.4.1. Saudi Arabia
11.4.2. UAE
11.4.3. South Africa
11.4.4. Others
11.5. Asia Pacific
11.5.1. China
11.5.2. Japan
11.5.3. South Korea
11.5.4. India
11.5.5. Indonesia
11.5.6. Thailand
11.5.7. Others
12. COMPETITIVE ENVIRONMENT AND ANALYSIS
12.1. Major Players and Strategy Analysis
12.2. Market Share Analysis
12.3. Product and Technology Benchmarking
12.4. Product Launches and Modular-Architecture Programs
12.5. Competitive Dashboard
13. COMPANY PROFILES
13.1. Yanfeng
13.2. FORVIA
13.3. Toyota Boshoku Corporation
13.4. Magna International Inc.
13.5. Antolin
13.6. Adient plc
14. APPENDIX
14.1. Currency
14.2. Assumptions
14.3. Base and Forecast Years Timeline
14.4. Key Benefits for Stakeholders
14.5. Research Methodology
14.6. Abbreviations
14.7. Data Sources
Navigate
Trusted by the world's leading organizations











