
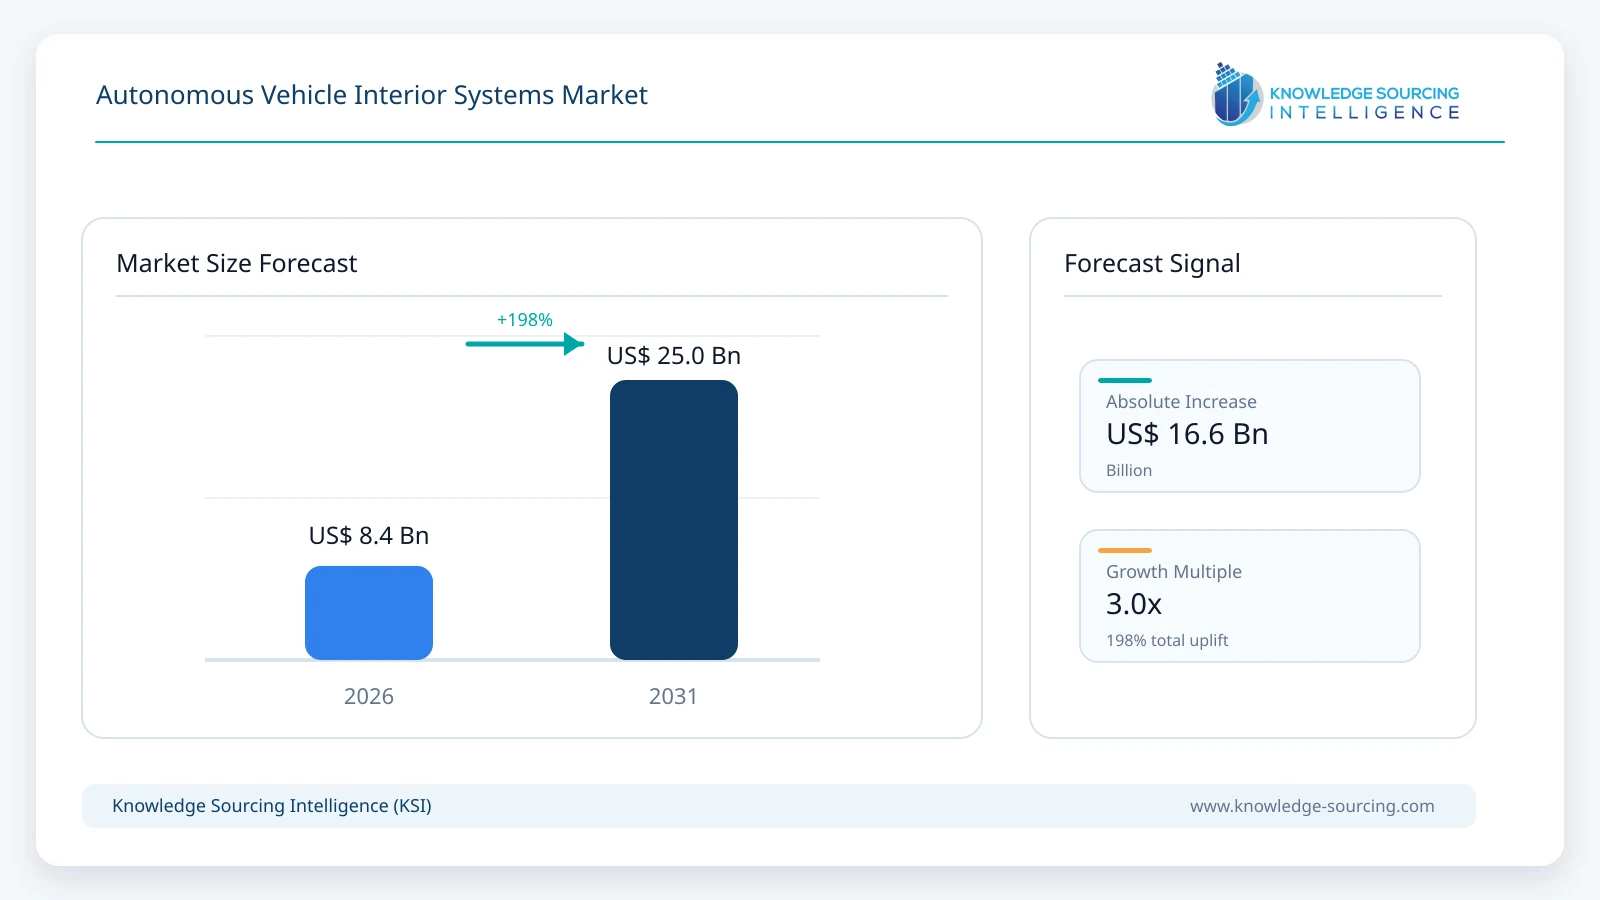
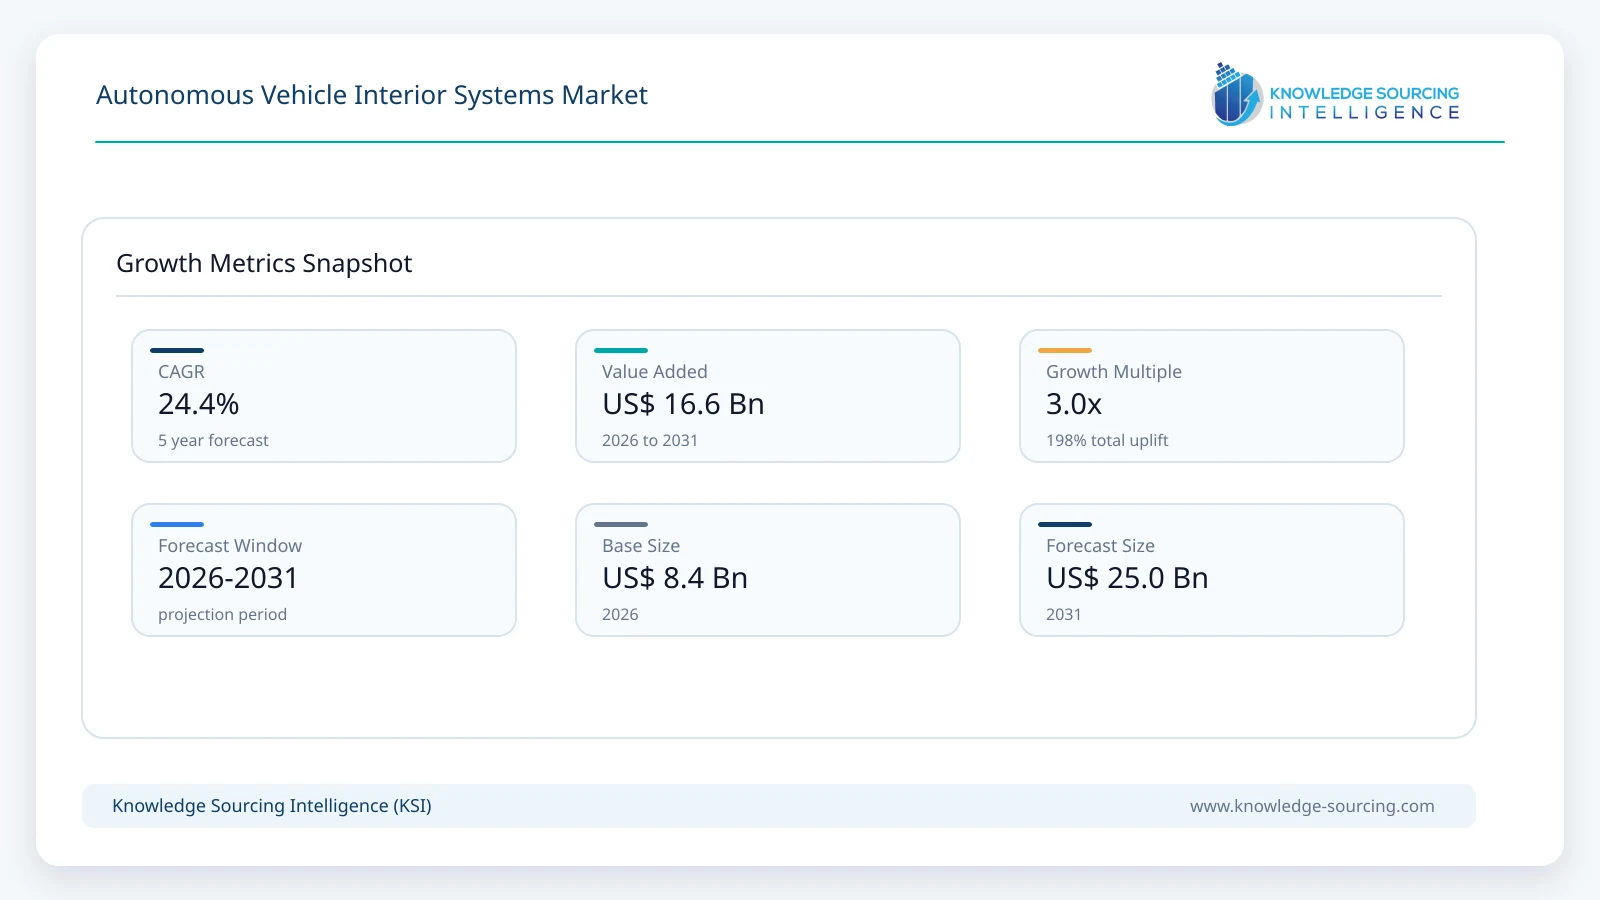
The autonomous vehicle interior systems market is forecast to grow at a CAGR of 24.4%, reaching approximately USD 25.0 billion in 2031 from USD 8.4 billion in 2026.
Highlights:
- 1Seating and reconfiguration systems account for approximately 29% of global market value in 2026, supported by long rails, swivels, powered positioning, integrated restraints and multi-mode seat architectures.
- 2SAE Level 3 applications represent approximately 58% of market value in 2026 as conditional automation provides the first production-scale requirement for interiors that transition between driving and non-driving modes.
- 3Personally owned autonomous passenger vehicles account for approximately 60% of global market value in 2026, while robotaxi and shared autonomous mobility applications are expanding rapidly.
- 4Passenger comfort, wellness and immersive experience applications represent approximately 31% of market value in 2026 as seating, thermal, lighting and acoustic systems become increasingly coordinated.
- 5Battery electric vehicles account for approximately 72% of global market value in 2026 because flat-floor packaging and centralized electronics provide a strong foundation for advanced autonomous interiors.
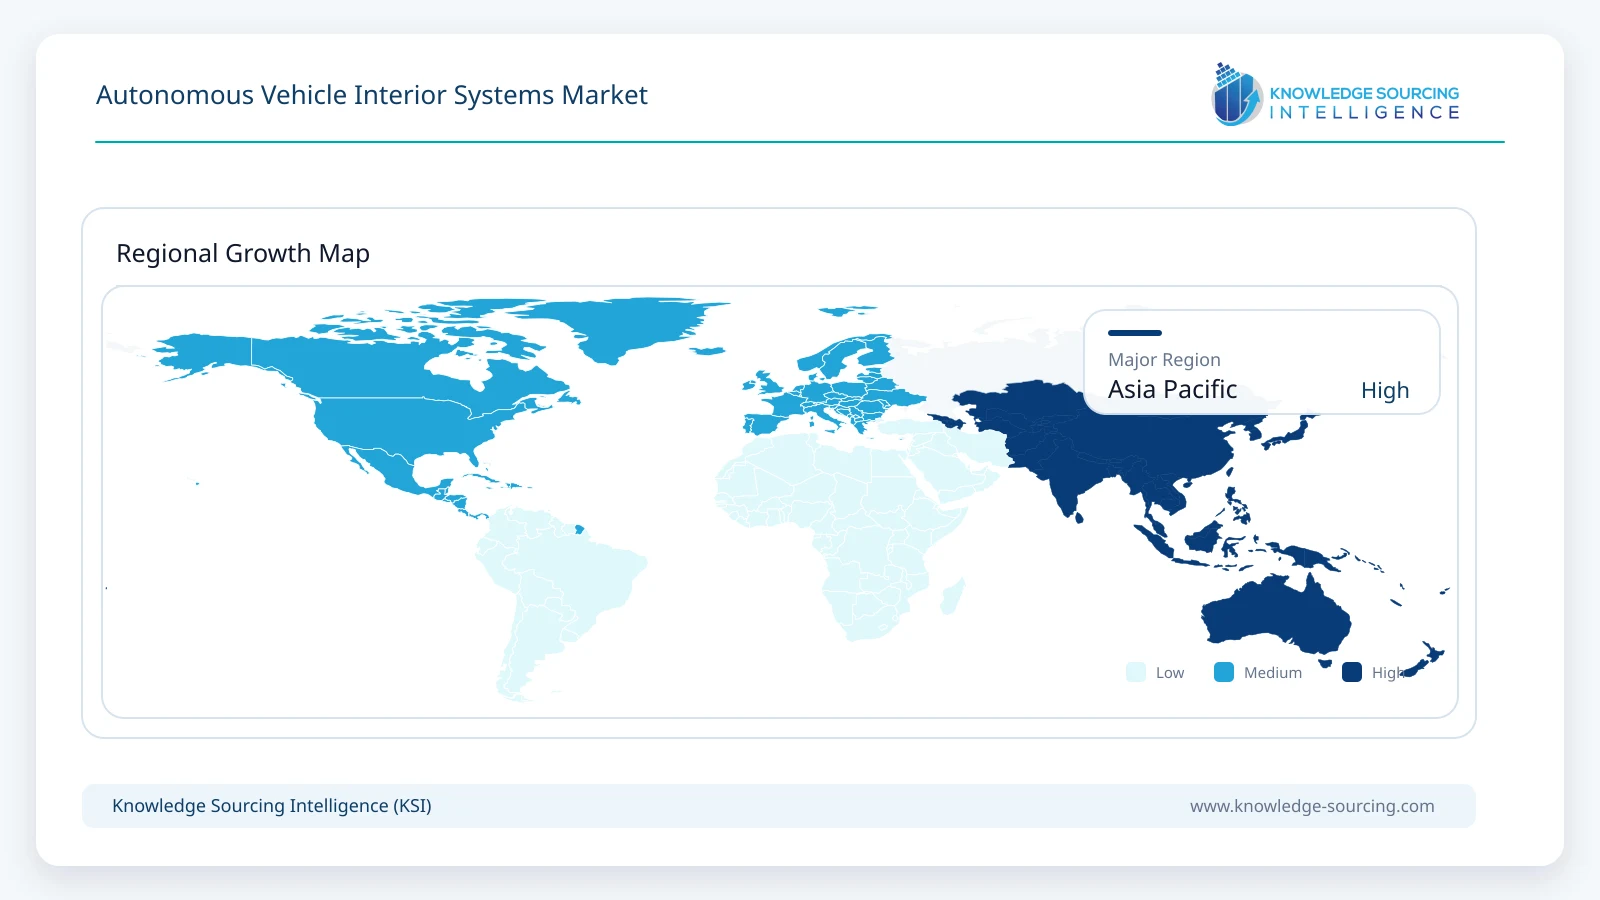
- 6Asia Pacific represents approximately 40% of global market value in 2026, supported by rapid EV, smart-cabin and automated-driving development in China, Japan and South Korea.
Demand is being driven by the transition from driver-centered interiors toward adaptive passenger environments that coordinate physical cabin systems with software, sensing and automated-driving functions.
The interior-system stack increasingly includes reconfigurable seating, cockpit and passenger displays, multimodal HMI, occupant monitoring, integrated restraints, localized thermal comfort, adaptive lighting, spatial audio, movable consoles, storage and intelligent surface technologies. These systems must support conventional travel while also enabling rest, work, social interaction and entertainment during automated-driving periods.
Yanfeng's XiM27 demonstrates full-system integration through centralized electronics connecting seating, interiors, lighting, climate and infotainment in a production-ready Level 3+ smart cabin. Toyota Boshoku's LOUNZE+ coordinates seats, door trims and console functions, while FORVIA, Magna, Hyundai Transys, Adient, Lear and TACHI-S are advancing complementary seating, cockpit, sensing and comfort technologies for automated mobility.
Market Overview
Autonomous vehicle interior systems form the physical and digital environment through which occupants experience automated mobility. At SAE Level 3, the cabin must support periods of reduced driver engagement while maintaining clear takeover communication and safe driving posture. At Level 4, the interior can place greater emphasis on passenger interaction, flexible seating, accessibility, productivity and personalized comfort.
Seating is a central structural system because automated vehicles allow a wider range of occupant positions. Long rails, swivel bases, integrated belts and powered adjustment can create lounge or social layouts while preserving a path back to approved travel positions. Magna, Adient, Lear, Toyota Boshoku, Hyundai Transys and TACHI-S are all developing seating technologies around this shift.
Cockpit electronics and HMI increasingly coordinate the passenger experience. Yanfeng's XiM27 uses a centralized domain controller to link entertainment, seating, lighting and climate, while autonomous mobility platforms such as Waymo's Ojai use rider-focused displays and personalized cabin controls rather than a conventional driver-centered interface.
Occupant sensing, thermal comfort, lighting and smart surfaces are also becoming system-level functions. Cameras, radar, seat sensing and software can identify occupant state; localized heating and ventilation can reduce whole-cabin energy demand; and adaptive lighting or surfaces can communicate vehicle status, warnings and personalized content.
Market Trends
Interior Systems Are Moving Toward Centralized Cabin Architectures
Automotive interiors are increasingly controlled through domain-level electronics rather than independent modules. Centralized architectures allow seating, HMI, climate, lighting and other interior functions to respond together to a selected cabin mode or occupant profile.
Yanfeng's XiM27 provides a production-ready example, using a self-developed domain controller to coordinate entertainment, seating, interiors and lighting while supporting rapid scenario changes.
Flexible Seating Is Becoming a Core Structural Platform
Long rails, swivel mechanisms, integrated restraints and adaptive support are becoming foundational to higher-automation cabins. Magna's Flexible Seating System is built around reusable structural building blocks, while Adient integrates electronics and belt systems directly into autonomous-oriented seat architectures.
The seat increasingly serves as the anchor for comfort, sensing, safety and HMI rather than operating as an isolated mechanical component.
Occupant Sensing Is Expanding Beyond Driver Monitoring
Interior sensing is broadening from driver-attention monitoring toward full-cabin occupant detection, classification, vital-sign monitoring, seatbelt detection and personalization. Magna combines cameras, radar and software to monitor driver and passenger conditions and support highly automated functions.
As seats move into more varied positions, sensing becomes increasingly important for determining occupant location, posture and readiness before automated movement or safety intervention.
Smart Surfaces Are Increasing Functional Interior Area
Door panels, instrument panels, consoles and trim are becoming interactive surfaces that can integrate lighting, controls, displays and haptic feedback. This reduces reliance on fixed switchgear and allows common physical surfaces to support multiple software-defined functions.
Smart surfaces are particularly valuable in autonomous interiors because occupants may use the cabin from different seating positions and require interfaces distributed across a larger area.
Wellness and Immersive Functions Are Gaining Importance
As automated driving creates more non-driving time, interior systems are increasingly designed around relaxation, sensory experience and individualized comfort. TACHI-S's Smart Shell combines sound, scent and vibration around a relaxed seat posture, while Toyota Boshoku and Hyundai Transys are developing living-space-oriented mobility concepts.
Thermal comfort, lighting, acoustics and seat-based functions are therefore becoming more valuable when coordinated as a single passenger-experience system.
Segment Analysis
By Interior System: Seating and Reconfiguration
Seating and reconfiguration systems are projected to reach approximately USD 6.50 billion by 2031. Growth is being supported by long rails, swivel mechanisms, integrated restraints, adaptive support and powered positioning that allow automated vehicles to move between conventional travel, lounge, work and rest configurations.
By Automation Level: SAE Level 4 and Above
SAE Level 4 and above interior systems are projected to reach approximately USD 15.00 billion by 2031. Higher automation allows vehicle cabins to be designed more strongly around passengers, increasing demand for rider-focused HMI, flexible seating, personalized comfort, accessibility and full-cabin sensing.
By Vehicle Application: Personally Owned Autonomous Passenger Vehicles
Personally owned autonomous passenger vehicles are projected to generate approximately USD 11.50 billion of interior-system market value by 2031. Premium and upper-mid passenger vehicles provide a major commercialization path for advanced seating, cockpit, comfort and personalization systems used repeatedly by the same occupants.
By Cabin Use Mode: Comfort, Wellness and Immersive Experience
Comfort, wellness and immersive interior systems are projected to reach approximately USD 7.25 billion by 2031. Reclined seating, localized thermal comfort, massage, adaptive lighting, spatial audio and smart surfaces become more valuable as occupants spend less time actively driving.
By Propulsion: Battery Electric Vehicles
Battery electric vehicles are projected to generate approximately USD 20.50 billion of autonomous interior-system market value by 2031. Flat floors, centralized electronics and close alignment between EV and automated-driving development make battery-electric platforms the principal architecture for advanced interior integration.
By Geography: Asia Pacific
Asia Pacific is projected to reach approximately USD 10.60 billion by 2031. China is the principal growth engine through rapid EV, smart-cabin and automated-driving development, while Japan and South Korea contribute established seating, interior, display and electronics capabilities.
Market Drivers
Expansion of SAE Level 3 and Level 4 Automated Driving
Increasing vehicle automation changes both occupant activity and interior-system requirements. Reduced driving responsibility increases demand for flexible seating, richer HMI, occupant sensing, safety adaptation and passenger-oriented comfort functions.
Growth of Software-Defined Vehicle Architectures
Centralized computing and software-defined electronics allow interior functions to be coordinated as integrated systems. This enables scenario-based cabin modes, software updates and common hardware platforms that can support multiple feature levels.
Electric-Vehicle Packaging Freedom
Battery-electric platforms can provide flatter floors and fewer drivetrain intrusions, creating greater freedom for long rails, movable consoles, thin seats and distributed interfaces. EV electronics also simplify integration of powered and connected cabin systems.
Demand to Reclaim Travel Time
Automated driving allows occupants to use travel time for work, communication, entertainment, rest and social activity. Interior systems that support these activities become a larger source of vehicle differentiation.
Scaling of Autonomous Mobility Services
Robotaxi and autonomous-shuttle deployment is creating a commercial market for durable passenger-focused interiors with accessibility, flexible seating, intuitive HMI and personalized cabin controls. Purpose-built vehicles can allocate interior space entirely around riders.
Market Restraints
Safety Across Non-Traditional Occupant Positions
Rotated, reclined and face-to-face seating changes occupant geometry relative to belts, airbags and vehicle structures. Interior systems therefore require integrated restraints, robust sensing and extensive validation across approved seating positions.
High System Cost and Integration Complexity
Advanced seating, displays, sensing, domain controllers, smart surfaces, thermal systems and premium interior functions add substantial hardware, software and validation cost. Early deployment remains concentrated in premium vehicles and autonomous fleets.
Cybersecurity and Data Privacy
Autonomous interiors increasingly process voice interaction, occupant profiles, biometric signals, location and cloud-connected services. Secure data handling and robust software protection become essential as interior functions are connected to central vehicle networks.
Regulatory and Operational-Domain Constraints
Automated-driving rules and approved operating conditions vary by jurisdiction. Interior features must remain compatible with driver-readiness requirements, occupant restraint rules and approved cabin configurations.
Motion Sickness and Human-Factors Challenges
Reading, screen use and non-forward-facing postures can increase sensitivity to vehicle motion. Interior systems therefore require coordinated design of seating, displays, lighting, airflow and sensory cues to maintain passenger comfort.
Regional Outlook
Asia Pacific
Asia Pacific is the largest regional market and is expected to remain the strongest growth centre through 2031. China is driving rapid commercialization of premium EVs, smart cabins and increasingly automated vehicles, while regional suppliers are moving full-system interior concepts toward production readiness.
Yanfeng's XiM27 integrates seating, interiors, cockpit electronics, passive safety, lighting, climate and AI in a production-ready Level 3+ platform. Toyota Boshoku's LOUNZE+ coordinates seats, door trims and console functions, while Hyundai Transys and TACHI-S are developing autonomous-oriented seating and sensory interior systems.
Europe
Europe is the second major regional market, supported by premium vehicle production, early Level 3 commercialization and a deep supplier base in seating, interiors, lighting and cockpit systems. FORVIA develops smart surfaces, HMI, infotainment, wellness and adaptable cockpit technologies, while Adient and Magna advance autonomous-oriented seating and safety integration.
The region's emphasis on occupant safety, software-defined vehicle development and premium interior experience supports higher-value integrated systems. Modular cockpit architectures, adaptive seating and smart surfaces are expected to gain importance as automated-driving operating domains expand.
Competitive Landscape
The autonomous vehicle interior systems market is led by suppliers with capabilities across seating, cockpit electronics, trim, HMI, comfort, lighting and safety integration. Yanfeng, FORVIA, Toyota Boshoku, Magna, Antolin, Hyundai Transys, Adient and Lear are directly active in interior technologies relevant to increasingly automated vehicles.
Yanfeng differentiates through complete smart-cabin integration across interiors, seating, cockpit electronics and passive safety. FORVIA provides a broad cockpit-of-the-future portfolio spanning seating, interiors, lighting, HMI and software. Toyota Boshoku develops coordinated mobility spaces that link seats, door trims, consoles and comfort systems.
Magna combines reconfigurable seating with interior sensing and complete vehicle-system integration. Antolin focuses on cockpit, door, trim and smart-surface technologies, Hyundai Transys develops total interior systems centered on seating, and Adient and Lear provide advanced seating platforms with comfort, electronics and autonomous-oriented functionality.
Recent Developments
July 2026: Waymo introduced Gemini in Waymo and a redesigned Ojai interface, expanding passenger control, journey information and conversational interaction within its rider-first autonomous interior.
July 2026: Magna highlighted the changing role of seating in autonomous vehicles, emphasizing greater positional freedom, passenger interaction and integrated safety as driver responsibility declines.
July 2026: Yanfeng's XiM27 received the 2026 Red Dot Design Concept Award; the platform integrates intelligent seat configuration, a mobile console, advanced cockpit, adaptive lighting, spatial audio and individualized climate control.
June 2026: Yanfeng unveiled XiM27, a production-ready Level 3+ smart-cabin platform using centralized electronics to coordinate seating, interiors, lighting and entertainment across multiple passenger scenarios.
May 2026: Waymo began welcoming public riders to the Ojai, a purpose-built autonomous vehicle with a flat-floor cabin, three large LED screens and integrated accessibility features.
May 2026: TACHI-S announced its Automotive Engineering Exposition 2026 program featuring Smart Shell, an autonomous-driving-oriented seat experience combining relaxed posture with sound, scent and vibration.
April 2026: Toyota Boshoku presented LOUNZE+ for Auto China 2026, coordinating seats, door trims and the center console so the interior can adapt to different purposes and passenger scenes.
Market Outlook
The autonomous vehicle interior systems market is expected to expand rapidly through 2031 as interiors become increasingly adaptive, passenger-centered and software-coordinated. Seating and reconfiguration will remain a major value pool, while cockpit/HMI, sensing, safety and personalized comfort systems are expected to gain content per vehicle.
The next stage of development will focus on integrated cabin architectures that transition smoothly between driving and non-driving activities, maintain occupant protection across a wider range of postures and coordinate multiple functions through central software. Physical interior design and digital intelligence will increasingly develop as one system.
Asia Pacific is expected to lead global expansion, while Europe remains a major market for premium integrated interiors and safety-focused automation. Competitive advantage will depend on system integration, cabin flexibility, functional safety, software architecture, occupant sensing, HMI quality and scalable manufacturing.
Autonomous Vehicle Interior Systems Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 8.4 billion |
| Total Market Size in 2031 | USD 25.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 24.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Interior System, Automation Level, Vehicle Application, Cabin Use Mode, Propulsion, Geography |
| Companies |
|
Market Segmentation
By Interior System
Seating and Reconfiguration
Cockpit, Displays and HMI
Occupant Sensing, Safety and Restraint Integration
Thermal Comfort and Wellness
Lighting, Acoustics and Smart Surfaces
Consoles, Storage, Door and Trim Systems
By Automation Level
SAE Level 3
SAE Level 4 and Above
By Vehicle Application
Personally Owned Autonomous Passenger Vehicles
Robotaxi and Shared Autonomous Mobility
Autonomous Shuttle and Commercial Mobility
By Cabin Use Mode
Comfort, Wellness and Immersive Experience
Productivity and Entertainment
Safety and Driving-Mode Transition
Cargo, Utility and Accessibility
By Propulsion
Battery Electric Vehicles
Hybrid Electric Vehicles
Internal Combustion Engine Vehicles
Fuel Cell Electric Vehicles
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
South Korea
India
Singapore
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Research
2.4. Market Estimation
2.5. Segment Modelling
2.6. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Autonomous Vehicle Interior Systems Market Size, 2026-2031
3.3. Interior System Outlook
3.4. Automation Level Outlook
3.5. Vehicle Application Outlook
3.6. Cabin Use Mode Outlook
3.7. Propulsion Outlook
3.8. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Expansion of SAE Level 3 and Level 4 Automated Driving
4.1.2. Growth of Software-Defined Vehicle Architectures
4.1.3. Electric-Vehicle Packaging Freedom
4.1.4. Demand to Reclaim Travel Time
4.1.5. Scaling of Autonomous Mobility Services
4.2. Market Restraints
4.2.1. Safety Across Non-Traditional Occupant Positions
4.2.2. High System Cost and Integration Complexity
4.2.3. Cybersecurity and Data Privacy
4.2.4. Regulatory and Operational-Domain Constraints
4.2.5. Motion Sickness and Human-Factors Challenges
4.3. Market Opportunities
4.4. Porter's Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Interior System Economics
4.7. Safety and Regulatory Environment
5. TECHNOLOGY OUTLOOK
5.1. Long-Rail and Reconfigurable Seating
5.2. Integrated Restraints and Predictive Safety
5.3. Cockpit and Passenger Displays
5.4. Multimodal HMI and Conversational AI
5.5. Driver and Occupant Monitoring
5.6. Localized Thermal Comfort and Wellness
5.7. Adaptive Lighting and Spatial Audio
5.8. Smart Surfaces and Functional Trim
5.9. Movable Consoles, Storage and Work Surfaces
5.10. Cabin Domain Controllers and AI Personalization
6. AUTONOMOUS VEHICLE INTERIOR SYSTEMS MARKET BY INTERIOR SYSTEM
6.1. Introduction
6.2. Seating and Reconfiguration
6.3. Cockpit, Displays and HMI
6.4. Occupant Sensing, Safety and Restraint Integration
6.5. Thermal Comfort and Wellness
6.6. Lighting, Acoustics and Smart Surfaces
6.7. Consoles, Storage, Door and Trim Systems
7. AUTONOMOUS VEHICLE INTERIOR SYSTEMS MARKET BY AUTOMATION LEVEL
7.1. Introduction
7.2. SAE Level 3
7.3. SAE Level 4 and Above
8. AUTONOMOUS VEHICLE INTERIOR SYSTEMS MARKET BY VEHICLE APPLICATION
8.1. Introduction
8.2. Personally Owned Autonomous Passenger Vehicles
8.3. Robotaxi and Shared Autonomous Mobility
8.4. Autonomous Shuttle and Commercial Mobility
9. AUTONOMOUS VEHICLE INTERIOR SYSTEMS MARKET BY CABIN USE MODE
9.1. Introduction
9.2. Comfort, Wellness and Immersive Experience
9.3. Productivity and Entertainment
9.4. Safety and Driving-Mode Transition
9.5. Cargo, Utility and Accessibility
10. AUTONOMOUS VEHICLE INTERIOR SYSTEMS MARKET BY PROPULSION
10.1. Introduction
10.2. Battery Electric Vehicles
10.3. Hybrid Electric Vehicles
10.4. Internal Combustion Engine Vehicles
10.5. Fuel Cell Electric Vehicles
11. AUTONOMOUS VEHICLE INTERIOR SYSTEMS MARKET BY GEOGRAPHY
11.1. North America
11.1.1. United States
11.1.2. Canada
11.1.3. Mexico
11.2. South America
11.2.1. Brazil
11.2.2. Argentina
11.2.3. Others
11.3. Europe
11.3.1. Germany
11.3.2. United Kingdom
11.3.3. France
11.3.4. Italy
11.3.5. Spain
11.3.6. Others
11.4. Middle East and Africa
11.4.1. Saudi Arabia
11.4.2. UAE
11.4.3. South Africa
11.4.4. Others
11.5. Asia Pacific
11.5.1. China
11.5.2. Japan
11.5.3. South Korea
11.5.4. India
11.5.5. Singapore
11.5.6. Others
12. COMPETITIVE ENVIRONMENT AND ANALYSIS
12.1. Major Players and Strategy Analysis
12.2. Market Share Analysis
12.3. Interior-System Technology Benchmarking
12.4. Concept-to-Production Development Activity
12.5. Competitive Dashboard
13. COMPANY PROFILES
13.1. Yanfeng
13.2. FORVIA
13.3. Toyota Boshoku Corporation
13.4. Magna International Inc.
13.5. Antolin
13.6. Hyundai Transys Inc.
13.7. Adient plc
13.8. Lear Corporation
14. APPENDIX
14.1. Currency
14.2. Assumptions
14.3. Base and Forecast Years Timeline
14.4. Key Benefits for Stakeholders
14.5. Research Methodology
14.6. Abbreviations
14.7. Data Sources
Navigate
Trusted by the world's leading organizations











