
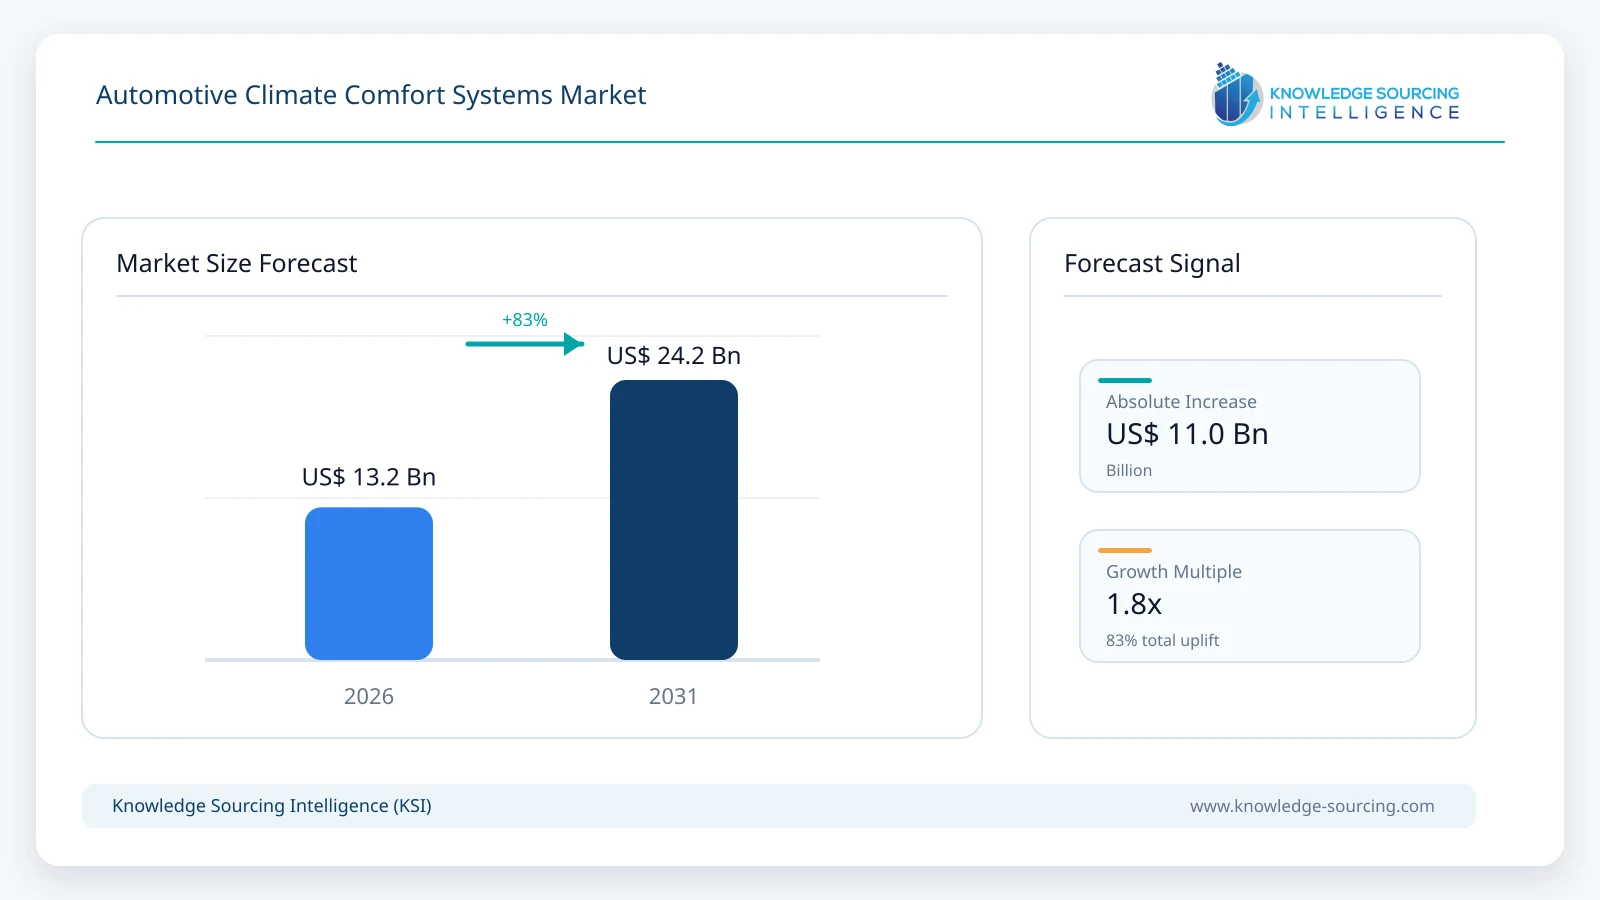
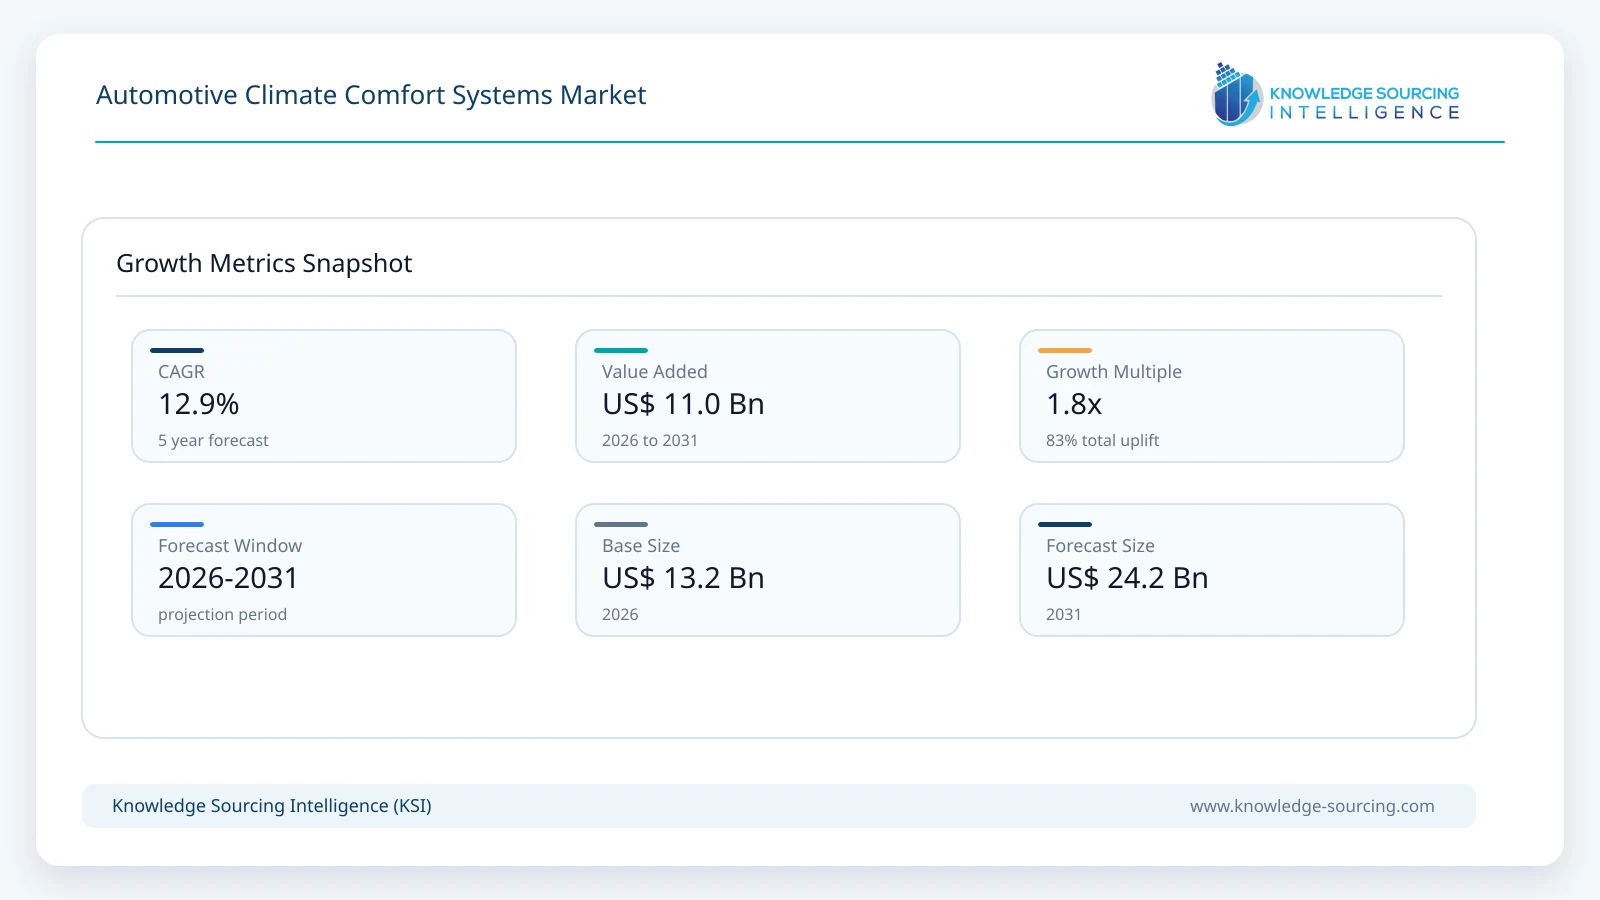
The automotive climate comfort systems market is estimated at approximately USD 13.2 billion in 2026 and is projected to reach about USD 24.2 billion by 2031, representing a CAGR of 12.9%.
Key Highlights
• Cabin HVAC and air-distribution systems account for approximately 44% of global market value in 2026 because compressors, evaporators, heaters, blowers, ducts and multi-zone air-management hardware remain the core infrastructure for passenger thermal comfort.
• Heating, cooling and dehumidification functions represent approximately 47% of market value in 2026, reflecting the central role of temperature regulation, humidity management, defogging and rapid cabin conditioning across all vehicle classes.
• Integrated central-plus-localized comfort architectures account for approximately 56% of 2026 market value as OEMs increasingly combine HVAC with seat heating and ventilation, radiant surfaces, zonal airflow and thermal-control software.
• Premium and upper-mid vehicles represent approximately 41% of global market value in 2026 because multi-zone HVAC, seat climate, heat pumps, radiant comfort and advanced control software are concentrated in higher-content vehicle platforms.
• Battery electric vehicles account for approximately 35% of market value in 2026 because EV platforms require energy-efficient cabin heating and cooling and increasingly combine heat pumps, preconditioning and localized comfort technologies.
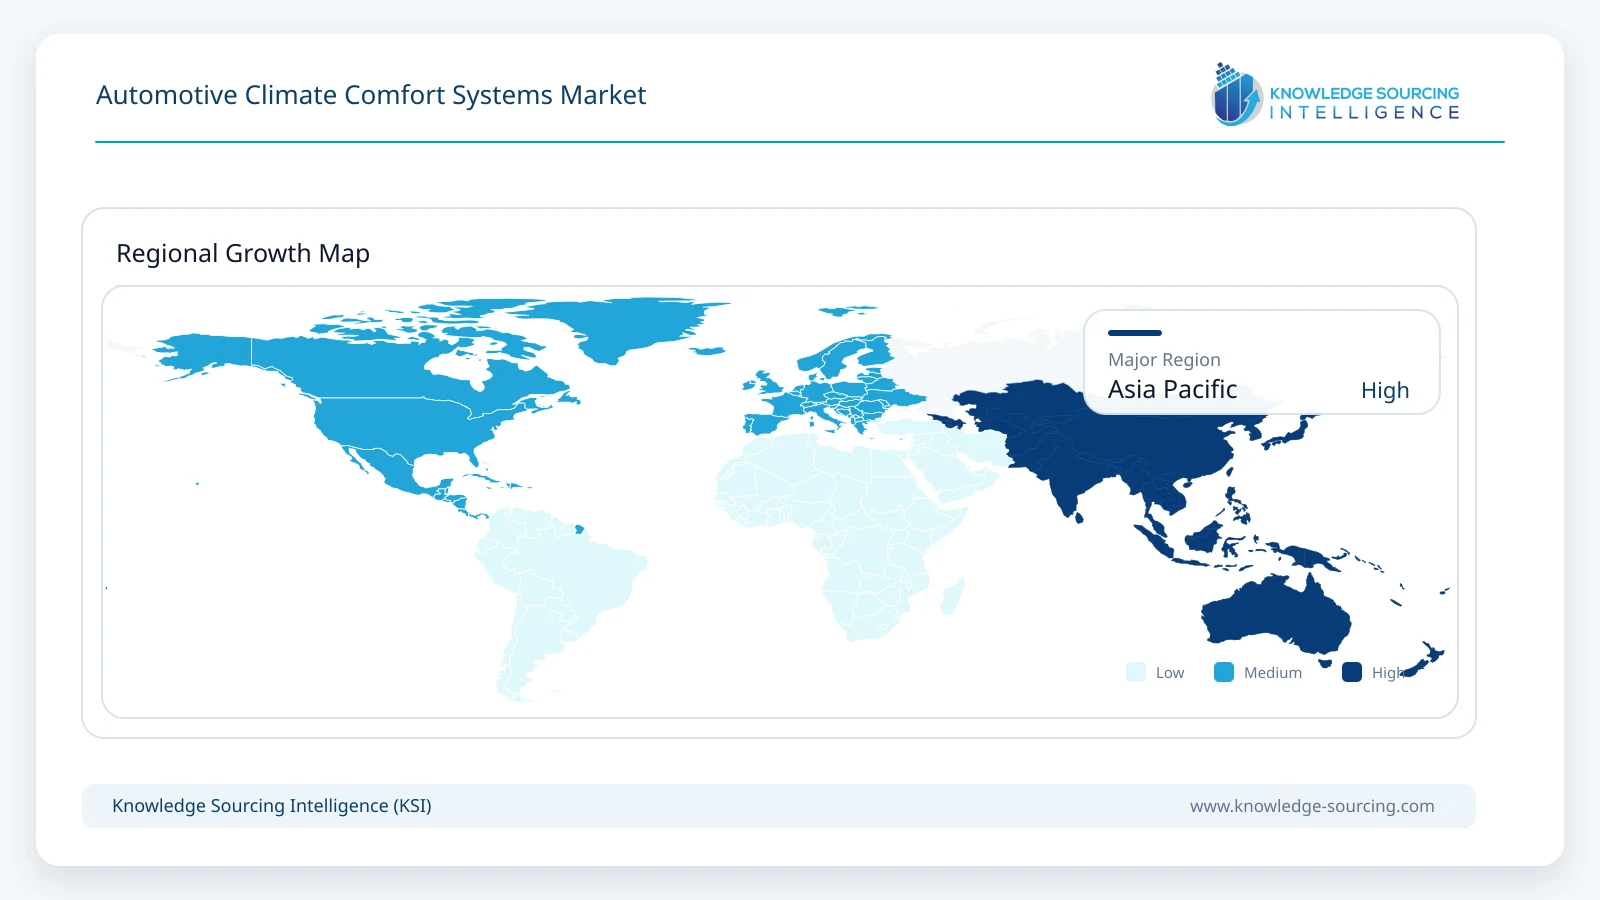
• Asia Pacific represents approximately 43% of global market value in 2026, supported by high vehicle production, rapid EV adoption in China and established thermal-management capabilities in Japan and South Korea.
The market is evolving from standalone heating and cooling hardware toward coordinated thermal-comfort architectures that combine central HVAC, zonal air distribution, seat and surface effectors, heat pumps, sensing and software-based control.
Commercial momentum is broadening across both hardware and software. Gentherm is expanding climate-control seats, ClimateSense and climate-control interiors; Lear is scaling ComfortFlex and ComfortMax thermal comfort systems; Valeo is deploying Dual Layer HVAC with multi-zone and AI-based airflow control; Hanon Systems is strengthening software-defined thermal management; MAHLE is developing heat-recovery and energy-efficient cabin-conditioning systems; and DENSO combines HVAC, heat pumps, air-quality systems and personal heating and cooling devices.
The market is increasingly shaped by the need to balance comfort and energy use. Conventional HVAC remains the largest hardware layer, but localized heating and cooling, radiant surfaces, smarter recirculation, occupant detection and predictive software can reduce the amount of cabin air that must be conditioned. This is particularly important in electric vehicles, where heating and cooling loads directly affect driving range.
Market Overview
Climate comfort is a core part of the in-vehicle experience because occupants continuously perceive temperature, airflow, humidity and surface conditions. Modern systems are expected to deliver rapid comfort after start-up, maintain stable conditions under changing solar and ambient loads, and support different preferences across multiple seating positions.
Automatic and multi-zone HVAC remain the foundation of the market. These systems control air temperature, blower output, air distribution and recirculation, while newer architectures add seat-specific airflow and occupancy logic. Valeo offers one- to six-zone HVAC and is commercializing a Dual Layer system that improves local comfort while reducing unnecessary airflow to unoccupied zones.
Localized thermal comfort is increasingly used to complement central HVAC. Climate-controlled seats, radiant heaters, steering-wheel heating and other near-body effectors can change perceived comfort faster than conditioning the full cabin volume. Gentherm ClimateSense and Lear thermal-comfort systems demonstrate how seat and surface effectors can be coordinated with central HVAC rather than operating as isolated options.
Electrification is reshaping system design. Heat pumps, heat recovery, preconditioning and integrated thermal-management controllers are becoming more important because every kilowatt used for cabin heating or cooling can affect vehicle range. MAHLE HeatX Range+ and Hanon Systems software-defined thermal-management platforms illustrate the shift toward thermal architectures that optimize comfort and energy at the same time.
The longer-term direction is toward predictive climate comfort. Occupant detection, environmental sensing, user profiles and centralized compute allow the vehicle to decide which zones need conditioning, how much thermal effort is required and which combination of HVAC, seat or surface effectors will provide comfort most efficiently.
Market Trends
Heat Pumps and Heat Recovery Are Becoming Central to EV Cabin Comfort
Electric vehicles require efficient heating because resistive heating can draw significant battery energy in cold weather. Heat pumps and heat-recovery systems therefore increasingly serve both vehicle-efficiency and cabin-comfort objectives.
MAHLE HeatX Range+ demonstrates the opportunity by recovering cabin exhaust-air heat and using it to preheat incoming fresh air, while Hanon Systems is integrating heat-pump control into software-defined thermal-management platforms.
Localized Comfort Is Complementing Central HVAC
Climate-controlled seats, radiant surfaces and personal airflow allow thermal energy to be delivered closer to the occupant. This can improve time-to-comfort and reduce the need to heat or cool the complete cabin volume to the same degree.
Gentherm ClimateSense and Lear thermal-comfort technologies are examples of systems that coordinate multiple local effectors around the occupant, increasing comfort content per seat while supporting lower HVAC energy demand.
Multi-Zone Air Distribution Is Becoming More Intelligent
Traditional dual-zone systems mainly provide separate temperature set points. Newer architectures increasingly adjust airflow volume, recirculation and outlet routing according to occupancy, seat position and real-time thermal demand.
Valeo Dual Layer HVAC illustrates this trend through multi-zone air management and AI-based algorithms that adapt temperature and airflow according to driver and passenger position.
Software-Defined Thermal Management Is Expanding Control Value
Centralized electronics allow HVAC, heat pumps, valves, pumps, seat climate and sensors to share data and operate through common software. This reduces the need for isolated controllers and gives OEMs more flexibility to optimize comfort and energy use through calibration and over-the-air updates.
Hanon Systems is explicitly strengthening software capabilities for software-defined vehicles, with modular thermal-control software that can manage components and complete thermal domains.
Climate Comfort Is Converging with Air Quality and Defogging Control
Temperature, humidity, recirculation and air quality are increasingly managed together because occupant comfort depends on more than dry-bulb temperature. Intelligent systems can use humidity and pollution inputs to decide when to recirculate, introduce fresh air, dehumidify or increase windshield clearing.
This convergence creates a broader control problem in which comfort, visibility, air quality and energy efficiency must be balanced rather than optimized independently.
Segment Analysis
By Climate System: Cabin HVAC and Air-Distribution Systems
Cabin HVAC and air-distribution systems are projected to generate approximately USD 9.30 billion of market value by 2031. Growth will be supported by wider adoption of automatic multi-zone systems, compact EV HVAC modules, intelligent air distribution and higher content per vehicle in premium and electric platforms.
The segment will remain the largest because every vehicle requires a central mechanism for cooling, heating, dehumidification and windshield conditioning. Value growth will increasingly come from efficiency, zonal control and software integration rather than simply higher blower or compressor capacity.
By Comfort Function: Heating, Cooling and Dehumidification
Heating, cooling and dehumidification functions are projected to generate approximately USD 11.00 billion of market value by 2031. These functions remain fundamental across all climates and vehicle classes and are increasingly optimized through heat pumps, variable-speed compressors and sensor-based control.
The segment also benefits from growing demand for rapid thermal response and robust defogging in EVs, where efficient conditioning is required without excessive battery-energy consumption.
By Thermal Architecture: Integrated Central and Localized Comfort Systems
Integrated central and localized comfort systems are projected to generate approximately USD 14.20 billion of market value by 2031. These architectures combine cabin HVAC with seat heating and ventilation, radiant surfaces, steering-wheel heating and other local effectors through shared control logic.
The segment is expected to gain share because combined architectures can improve occupant comfort more quickly and selectively while reducing the thermal load placed on the central HVAC system.
By Vehicle Class: Premium and Upper-Mid Vehicles
Premium and upper-mid vehicles are projected to generate approximately USD 9.70 billion of climate-comfort market value by 2031. These vehicle classes provide the strongest commercialization path for multi-zone climate, heat pumps, climate-controlled seats, radiant surfaces and advanced comfort software.
However, modular HVAC units, lower-cost sensors and scalable software are expected to move selected higher-end functions into mass-market vehicles over the forecast period.
By Propulsion: Battery Electric Vehicles
Battery electric vehicles are projected to generate approximately USD 9.20 billion of climate-comfort market value by 2031. EVs provide the strongest efficiency case for heat pumps, cabin preconditioning, localized comfort and occupancy-based climate control because cabin thermal loads directly affect available driving range.
Integration between cabin comfort and battery or powertrain thermal systems will also increase, although the market value here is limited to hardware and software that directly supports occupant climate comfort.
Market Drivers
Electrification and the Need to Reduce Cabin HVAC Energy Consumption
Cabin heating and cooling can materially affect EV range, particularly during winter heating and extreme summer conditions. This creates strong demand for heat pumps, heat recovery, seat climate, radiant surfaces and occupancy-based control that can maintain comfort with lower energy use.
Thermal comfort technologies are therefore becoming part of the vehicle-efficiency strategy rather than being treated only as convenience features.
Vehicle Premiumization and Rising Expectations for Multi-Zone Comfort
Consumers increasingly expect independent temperature control, rear-seat climate, ventilated seats and rapid comfort response in premium and upper-mid vehicles. These expectations are pushing OEMs to add more zones, actuators and sensors to cabin climate systems.
Competition among premium EV brands is accelerating this trend because cabin experience is a major differentiator when powertrain performance becomes less distinctive.
Advances in Heat Pumps, Variable-Speed Compressors and Thermal Hardware
More efficient compressors, compact heat-pump modules, electronic expansion valves and integrated heat exchangers are improving the performance of cabin climate systems across a wider range of temperatures.
These technologies support faster heating and cooling while reducing the energy penalty associated with conventional resistive or fixed-speed systems.
Growth of Software-Defined and Zonal Vehicle Architectures
Centralized and zonal electronics make it easier to coordinate HVAC, valves, pumps, seat climate and sensors through common software. This supports predictive control, adaptive calibration and over-the-air improvements throughout the vehicle lifecycle.
Software-defined architectures also reduce controller duplication and allow climate functionality to be differentiated across trims using common hardware platforms.
Demand for Faster, More Personalized Time-to-Comfort
Occupants increasingly expect the cabin to reach a comfortable state quickly after entering the vehicle. Localized seat and surface effectors can deliver thermal sensation faster than changing the temperature of the complete cabin air mass.
Combining fast local comfort with central HVAC allows automakers to improve perceived quality while using energy more selectively.
Market Restraints
Higher Cost and Complexity of Integrated Thermal Architectures
Heat pumps, multi-zone HVAC, seat climate, radiant surfaces and additional sensors increase component count, software complexity and validation requirements. The cost remains difficult to justify in lower-price vehicle segments.
Broader adoption depends on modular hardware and software that can be shared across multiple vehicle platforms and trim levels.
Performance Trade-Offs under Extreme Ambient Conditions
Heat pumps and localized effectors improve efficiency, but severe cold or extreme heat can still require high central HVAC output. Maintaining rapid comfort under these conditions can reduce the expected energy benefit.
System design must therefore balance efficiency with robust heating, cooling, dehumidification and defogging performance across global climates.
Packaging Constraints for Ducts, Heat Exchangers and Local Effectors
Multi-zone systems require ducts, vents, valves and thermal components that compete for limited instrument-panel, seat and console space. Electric-vehicle platforms may provide new packaging opportunities but also introduce battery, electronics and structural constraints.
Compact integrated modules and surface-based comfort technologies are important for reducing packaging pressure.
Calibration Complexity across Occupants, Climates and Vehicle Types
Thermal comfort depends on ambient temperature, solar load, humidity, clothing, body size and personal preference. A control strategy that works in one market may not produce the same comfort response in another.
OEMs therefore require extensive climatic testing and human-factors calibration, increasing development cost and time.
Refrigerant and Environmental Compliance Requirements
Climate systems must adapt to evolving refrigerant regulations and decarbonization targets while maintaining safety, cost and performance. Alternative refrigerants can require new compressors, heat exchangers, controls and service procedures.
Suppliers need flexible architectures that can support regulatory change without forcing complete redesigns of the cabin climate system.
Regional Outlook
Asia Pacific
Asia Pacific is the largest regional market and is expected to remain the strongest growth centre through 2031. China is rapidly expanding advanced HVAC, heat-pump and multi-zone climate content across electric vehicles, while Japan and South Korea contribute established expertise in compressors, air-conditioning systems and integrated thermal management.
Valeo has secured multiple Dual Layer HVAC contracts in China, while Hanon Systems is expanding software-defined and AI-integrated thermal-management capabilities. DENSO provides heat-pump HVAC, air-quality systems and personal heating and cooling devices across global and regional vehicle platforms.
Growth will be supported by high vehicle production, rapid EV penetration and strong competition around smart-cabin experience. Suppliers that can combine climate comfort with low energy demand and competitive system cost are positioned to capture the largest regional opportunity.
Europe
Europe is a major high-value market because premium automakers and thermal-management suppliers continue to emphasize efficient cabin heating, heat pumps, climate-controlled seating and advanced thermal-control software. The region also faces strong pressure to reduce EV energy consumption and adopt lower-impact refrigerant solutions.
Gentherm and Lear are expanding thermal-comfort content across European OEM programs, while MAHLE HeatX Range+ targets lower cabin-heating energy demand through heat recovery. Valeo and Hanon Systems also maintain significant European thermal-management capabilities and customer relationships.
Growth through 2031 will depend on combining rapid time-to-comfort with stringent efficiency and emissions requirements. Heat recovery, software-defined control and localized thermal effectors are expected to gain importance as European EV penetration rises.
Competitive Landscape
The automotive climate comfort systems market includes HVAC, thermal-management, seating and cabin-control suppliers that directly influence occupant temperature, airflow and thermal sensation. Gentherm, Lear, Valeo, Hanon Systems, MAHLE and DENSO are directly active across climate-controlled seating, multi-zone HVAC, heat pumps, heat recovery, localized comfort and software-defined thermal control.
Gentherm is differentiated by ClimateSense, climate-control seats and climate-control interiors, while Lear combines complete-seat integration with ComfortFlex, ComfortMax and related thermal technologies. Valeo provides one- to six-zone HVAC and Dual Layer architectures that improve local comfort and energy efficiency.
Hanon Systems and MAHLE contribute full-vehicle thermal-management expertise that increasingly supports cabin comfort through software control, heat pumps and heat recovery. DENSO combines HVAC, heat pumps, air-quality systems and personal heating and cooling devices. Competition is shifting toward suppliers that can deliver comfort and efficiency through coordinated hardware and software rather than isolated components.
Recent Developments
• 12 August 2026: Hanon Systems was named a finalist for the 2026 Automotive News PACE Awards for its Highly Integrated Cooling Entity, which combines key refrigerant-system functions in a compact module for next-generation electrified-vehicle thermal management.
• 31 July 2026: Lear reported new and conquest awards with Audi for complete seats, ComfortFlex and FlexAir in Europe and North America, expanding commercial adoption of modular occupant thermal-comfort technologies.
• 23 July 2026: Gentherm reported USD 690 million of automotive new-business awards in the second quarter and 14.1% year-over-year growth in Automotive Climate and Comfort Solutions revenue.
• 26 May 2026: Hanon Systems announced its 2030 growth strategy and said it would further strengthen software capabilities for the software-defined vehicle era alongside next-generation thermal-management development.
• 30 April 2026: Hanon Systems reported expansion of AI-based integrated thermal-management capabilities with an increasing focus on software beyond its full-vehicle thermal hardware portfolio.
• 19 February 2026: Gentherm reported record 2025 revenue and continued growth in Automotive Climate and Comfort Solutions, with new-business awards across climate-control seats, lumbar and massage technologies and other comfort systems.
• 9 February 2026: MAHLE introduced HeatX Range+, a heat-recovery system designed to reduce energy demand for EV cabin air conditioning by approximately 20% while maintaining cabin comfort and air quality.
• 24 September 2025: Valeo announced additional contracts for its Dual Layer HVAC system in China, bringing the technology to 10 contracts with five customers and supporting serial production from 2026.
Market Outlook
The automotive climate comfort systems market is expected to expand steadily through 2031 as thermal comfort becomes more energy-efficient, more localized and more software-controlled. Central HVAC will remain the largest hardware value pool, while faster growth is expected in heat pumps, heat recovery, climate-controlled seating, radiant comfort and predictive control software.
The market will increasingly move from fixed cabin set points toward adaptive thermal management. Vehicles will combine ambient conditions, occupancy, solar load and user preference to decide how much central HVAC output is required and when local effectors can provide comfort more efficiently.
Asia Pacific is expected to retain the largest regional share, while Europe remains a major premium engineering and commercialization market. Competitive advantage will depend on rapid time-to-comfort, measurable energy savings, compact system packaging, refrigerant flexibility and software that coordinates central and localized climate technologies without compromising defogging or extreme-weather performance.
Automotive Climate Comfort Systems Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 13.2 billion |
| Total Market Size in 2031 | USD 24.2 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 12.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Climate System, Comfort Function, Thermal Architecture, Vehicle Class, Propulsion, Geography |
| Companies |
|
Market Segmentation
By Climate System
Cabin HVAC and Air-Distribution Systems
Seat and Surface Thermal Comfort Systems
Heat Pump and Heat-Recovery Systems
Climate Sensors, Controllers and Software
By Comfort Function
Heating, Cooling and Dehumidification
Localized Thermal Comfort
Airflow and Ventilation Comfort
Defogging and Visibility Comfort
Energy-Optimized Climate Comfort
By Thermal Architecture
Integrated Central and Localized Comfort Systems
Central Automatic and Multi-Zone HVAC Systems
Predominantly Localized Thermal Comfort Systems
By Vehicle Class
Premium and Upper-Mid Vehicles
Mass-Market Passenger Vehicles
Light Commercial and Other Vehicles
By Propulsion
Battery Electric Vehicles
Hybrid and Plug-in Hybrid Electric Vehicles
Internal Combustion Engine Vehicles
Fuel Cell Electric Vehicles
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
South Korea
India
Singapore
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Research
2.4. Market Estimation
2.5. Segment Modelling
2.6. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Automotive Climate Comfort Systems Market Size, 2026-2031
3.3. Climate System Outlook
3.4. Comfort Function Outlook
3.5. Thermal Architecture Outlook
3.6. Vehicle Class Outlook
3.7. Propulsion Outlook
3.8. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Electrification and the Need to Reduce Cabin HVAC Energy Consumption
4.1.2. Vehicle Premiumization and Rising Expectations for Multi-Zone Comfort
4.1.3. Advances in Heat Pumps, Variable-Speed Compressors and Thermal Hardware
4.1.4. Growth of Software-Defined and Zonal Vehicle Architectures
4.1.5. Demand for Faster, More Personalized Time-to-Comfort
4.2. Market Restraints
4.2.1. Higher Cost and Complexity of Integrated Thermal Architectures
4.2.2. Performance Trade-Offs under Extreme Ambient Conditions
4.2.3. Packaging Constraints for Ducts, Heat Exchangers and Local Effectors
4.2.4. Calibration Complexity across Occupants, Climates and Vehicle Types
4.2.5. Refrigerant and Environmental Compliance Requirements
4.3. Market Opportunities
4.4. Porter's Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Climate Comfort System Economics
4.7. Thermal Comfort, Refrigerant and Energy-Efficiency Environment
5. TECHNOLOGY OUTLOOK
5.1. Automatic and Multi-Zone HVAC Systems
5.2. Variable-Speed Compressors and Electronic Expansion Valves
5.3. Heat Pump Cabin Conditioning
5.4. Heat Recovery and Fresh-Air Preconditioning
5.5. Climate-Controlled Seats and Seat Ventilation
5.6. Radiant Heating and Thermal Interior Surfaces
5.7. Localized Airflow and Personal Ventilation
5.8. Humidity, Defogging and Dew-Point Management
5.9. Occupancy, Solar-Load and Cabin Temperature Sensing
5.10. AI, Predictive Climate and Thermal Comfort Algorithms
5.11. Climate ECUs, Zonal Controllers and Software-Defined Thermal Management
6. AUTOMOTIVE CLIMATE COMFORT SYSTEMS MARKET BY CLIMATE SYSTEM
6.1. Introduction
6.2. Cabin HVAC and Air-Distribution Systems
6.3. Seat and Surface Thermal Comfort Systems
6.4. Heat Pump and Heat-Recovery Systems
6.5. Climate Sensors, Controllers and Software
7. AUTOMOTIVE CLIMATE COMFORT SYSTEMS MARKET BY COMFORT FUNCTION
7.1. Introduction
7.2. Heating, Cooling and Dehumidification
7.3. Localized Thermal Comfort
7.4. Airflow and Ventilation Comfort
7.5. Defogging and Visibility Comfort
7.6. Energy-Optimized Climate Comfort
8. AUTOMOTIVE CLIMATE COMFORT SYSTEMS MARKET BY THERMAL ARCHITECTURE
8.1. Introduction
8.2. Integrated Central and Localized Comfort Systems
8.3. Central Automatic and Multi-Zone HVAC Systems
8.4. Predominantly Localized Thermal Comfort Systems
9. AUTOMOTIVE CLIMATE COMFORT SYSTEMS MARKET BY VEHICLE CLASS
9.1. Introduction
9.2. Premium and Upper-Mid Vehicles
9.3. Mass-Market Passenger Vehicles
9.4. Light Commercial and Other Vehicles
10. AUTOMOTIVE CLIMATE COMFORT SYSTEMS MARKET BY PROPULSION
10.1. Introduction
10.2. Battery Electric Vehicles
10.3. Hybrid and Plug-in Hybrid Electric Vehicles
10.4. Internal Combustion Engine Vehicles
10.5. Fuel Cell Electric Vehicles
11. AUTOMOTIVE CLIMATE COMFORT SYSTEMS MARKET BY GEOGRAPHY
11.1. North America
11.1.1. United States
11.1.2. Canada
11.1.3. Mexico
11.2. South America
11.2.1. Brazil
11.2.2. Argentina
11.2.3. Others
11.3. Europe
11.3.1. Germany
11.3.2. United Kingdom
11.3.3. France
11.3.4. Italy
11.3.5. Spain
11.3.6. Others
11.4. Middle East and Africa
11.4.1. Saudi Arabia
11.4.2. UAE
11.4.3. South Africa
11.4.4. Others
11.5. Asia Pacific
11.5.1. China
11.5.2. Japan
11.5.3. South Korea
11.5.4. India
11.5.5. Singapore
11.5.6. Others
12. COMPETITIVE ENVIRONMENT AND ANALYSIS
12.1. Major Players and Strategy Analysis
12.2. Market Share Analysis
12.3. Climate Comfort Technology Benchmarking
12.4. Product Launches and Development Activity
12.5. Competitive Dashboard
13. COMPANY PROFILES
13.1. Gentherm Incorporated
13.2. Lear Corporation
13.3. Valeo
13.4. Hanon Systems
13.5. MAHLE GmbH
13.6. DENSO Corporation
14. APPENDIX
14.1. Currency
14.2. Assumptions
14.3. Base and Forecast Years Timeline
14.4. Key Benefits for Stakeholders
14.5. Research Methodology
14.6. Abbreviations
14.7. Data Sources
Navigate
Trusted by the world's leading organizations











