
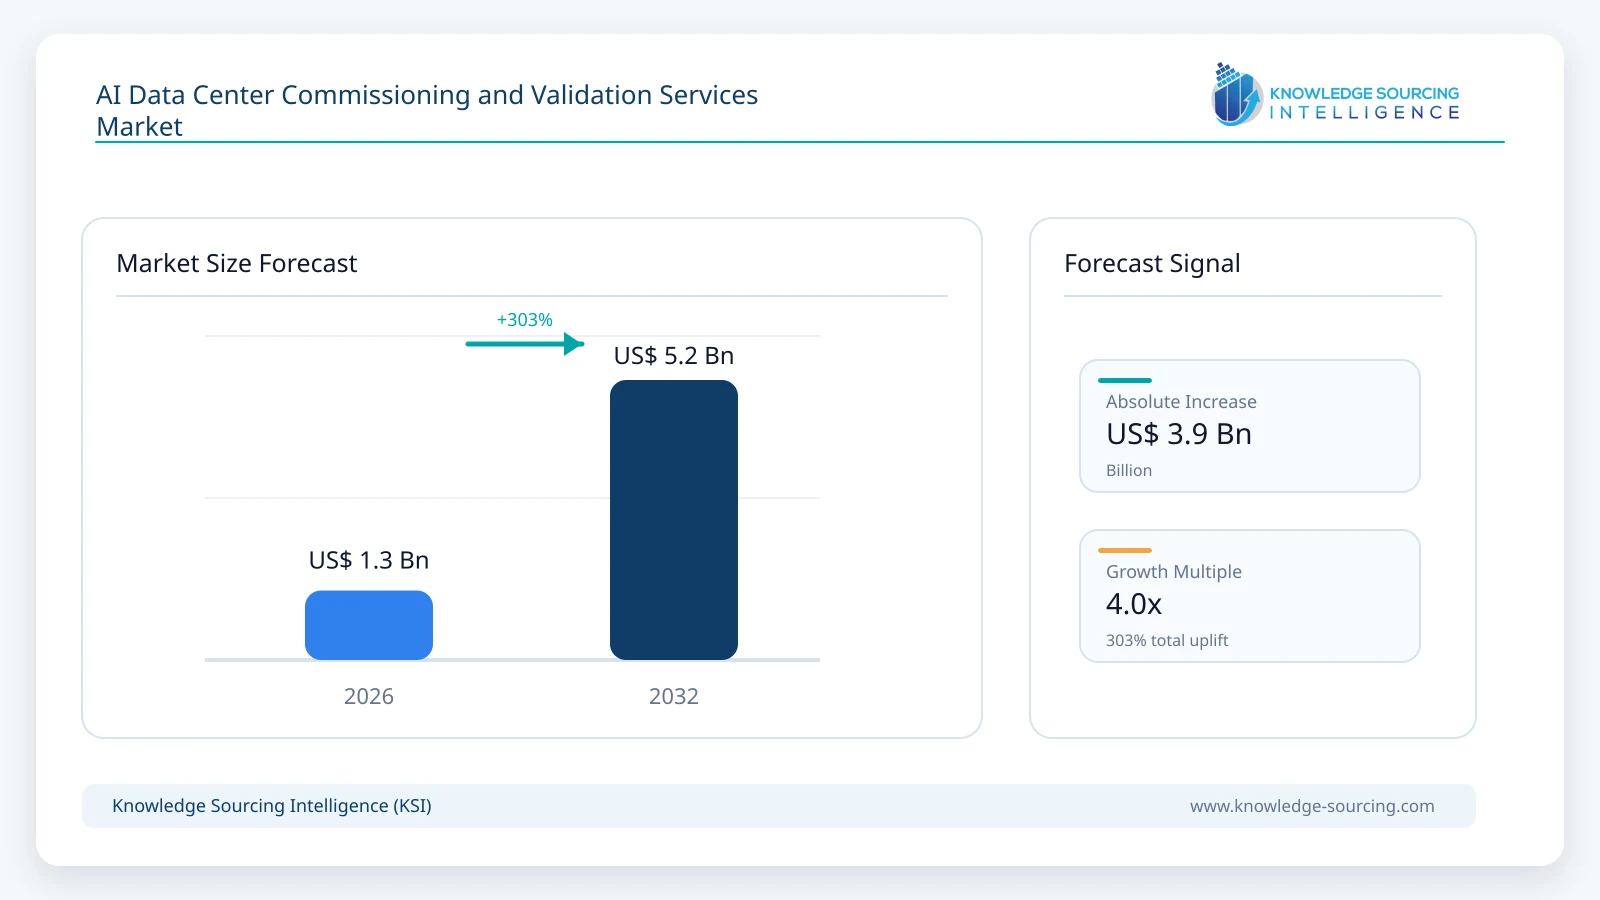
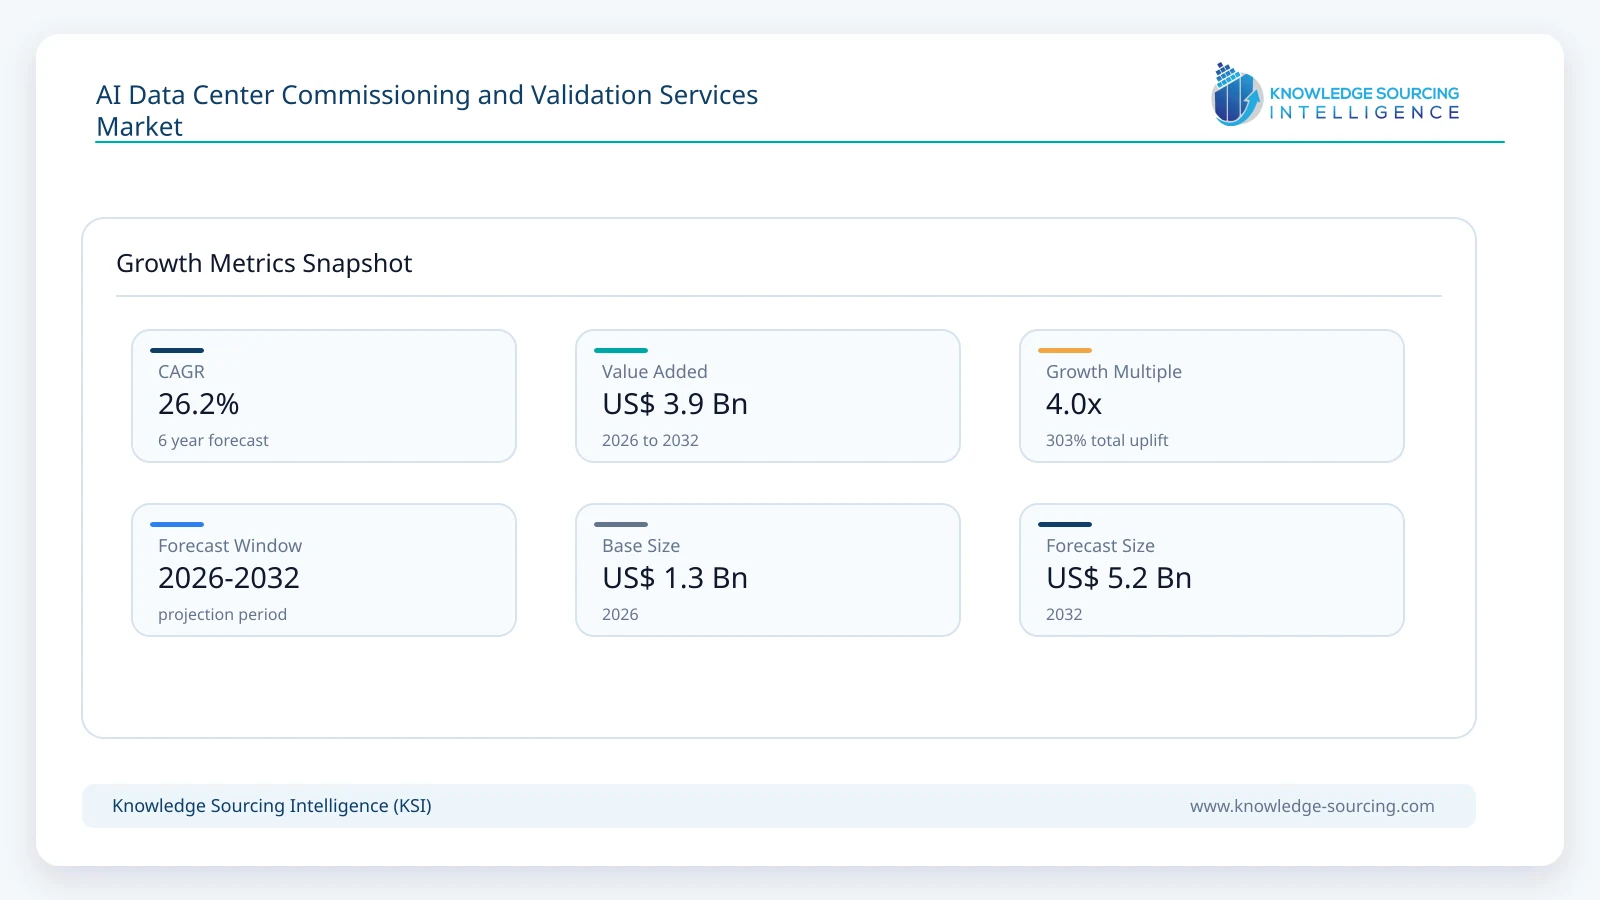
The AI Data Center Commissioning and Validation Services Market is estimated at USD 1.30 billion in 2026 and is projected to reach USD 5.24 billion by 2032, representing a CAGR of 26.2% over the forecast period.
Highlights:
- 1Liquid cooling is expanding commissioning from facility systems into technology cooling loops and rack interfaces.
- 2Integrated systems testing is becoming more important as AI power and thermal systems interact dynamically.
- 3Factory witness testing reduces deployment risk before high-density cooling and power equipment reaches the site.
- 4AI load emulation requires higher-power and increasingly liquid-cooled load-bank validation approaches.
- 5Compressed construction schedules are increasing demand for staged and block-level commissioning workflows.
- 6Prefabricated infrastructure shifts part of commissioning into factories but does not remove site integration testing.
- 7Controls validation now spans building systems, electrical monitoring, cooling controls and AI-factory orchestration layers.
- 8North America leads demand through the scale and complexity of hyperscale and neocloud AI construction.
- 9Retrofit commissioning is growing as existing facilities are converted for liquid-cooled high-density AI clusters.
- 10Specialist commissioning labor remains a limiting factor in fast-growing data-center markets worldwide.
- 11Failure-mode testing is increasingly tied to GPU availability and time-to-token rather than facility uptime alone.
- 12Digital twins and reference designs support validation but do not replace physical commissioning and acceptance testing.
Conventional data-center commissioning already spans equipment inspection, pre-functional checks, functional testing and integrated systems testing. AI infrastructure increases the number and criticality of interfaces that must be validated. A high-density rack can depend simultaneously on multiple power-conversion stages, busway, coolant distribution units (CDUs), facility-water systems, leak detection, controls, networked telemetry and workload-management software. A fault in one layer can propagate quickly into another. Commissioning therefore has to verify not only that individual assets operate correctly, but also that the full chain responds predictably during rapid load changes, equipment failures, utility disturbances and maintenance events.
Direct liquid cooling is one of the clearest sources of incremental commissioning content. Uptime Institute's January 2026 guidance highlights factory witness testing of CDUs, technology-cooling-loop integration and the difficulty of proving performance across equipment supplied by vendors with different levels of data-center experience. ASHRAE similarly warns that inadequate hydronic cleaning, flushing and passivation can foul cold plates or delay deployment. These requirements add fluid sampling, pressure testing, cleanliness verification, pump sequencing, control tuning and failure simulations to a commissioning process that was historically dominated by electrical systems and room-level cooling.
The delivery model is also changing. AI campuses are increasingly built in repeatable multi-megawatt blocks, using prefabricated power and cooling systems and validated reference architectures. This moves selected tests to the factory, but it increases the importance of final site acceptance and integrated validation because modules from different suppliers still have to operate as one system. At the same time, retrofit projects require commissioning teams to validate new high-density equipment against legacy infrastructure whose actual condition may differ from original drawings. These trends expand commissioning across both greenfield and brownfield projects while rewarding firms that can test electrical, mechanical, controls, and IT-facing interfaces under one coordinated program.
Market Drivers
Liquid-cooled AI infrastructure adds new validation steps
The technology cooling system introduces fluid-side commissioning requirements that do not exist in conventional air-cooled facilities. CDUs, manifolds, cold plates, pumps, heat exchangers, and water-treatment interfaces must be cleaned, filled, vented, pressure-tested, and validated as an integrated hydraulic system. Control sequences must also be checked against realistic rack loads and rapid thermal transients. Uptime Institute and ASHRAE both identify these interfaces as areas where commissioning practice is still evolving, which increases the value of specialist engineers with both data-center and liquid-cooling experience.
Speed-to-token raises the financial value of defect discovery before handover
AI infrastructure carries unusually high opportunity cost when commissioned capacity cannot support production workloads. Discovering an electrical protection issue, flow imbalance, controls fault or redundancy gap after GPUs arrive can delay revenue-producing compute and force intrusive rework. Operators therefore have a stronger incentive to move failure discovery earlier through factory tests, staged functional testing and integrated systems testing. Commissioning spend remains small compared with the cost of accelerator hardware and the revenue associated with deployed AI capacity, supporting higher validation intensity on large projects.
Power, cooling and controls increasingly require joint integrated systems testing
AI workloads create synchronized electrical and thermal changes that cross traditional discipline boundaries. Electrical power monitoring, building management systems, cooling controls, leak detection and AI-factory operations software increasingly exchange telemetry and commands. Schneider Electric's 2026 control reference designs and NVIDIA DSX architecture illustrate this tighter information-technology and operational-technology integration. Commissioning therefore needs to validate signal quality, fail-safe behavior, control handoffs and response sequences in addition to traditional equipment performance.
Accelerated modular construction increases staged commissioning demand
Prefabricated power and cooling modules reduce field assembly but do not eliminate acceptance risk. Instead, validation is distributed across factory acceptance, site installation, subsystem start-up and final integrated testing. As AI campuses are delivered in smaller repeatable blocks, commissioning teams increasingly work on rolling turnover schedules rather than waiting for an entire building to be complete. This supports recurring service revenue across multi-phase campuses and creates demand for standardized test scripts, documentation and digital issue management.
Restraints and Adoption Challenges
The largest constraint is specialist labor. Commissioning high-density electrical systems already requires experienced engineers, and liquid cooling adds hydraulic, fluid-quality and controls expertise that is not yet available at the same scale in every market. Compressed construction schedules can also create pressure to shorten testing windows even as system complexity increases. Responsibility can be fragmented among the commissioning agent, general contractor, original equipment manufacturers, controls integrator, cooling vendor and IT supplier, making defect ownership difficult to resolve. In addition, AI-specific load emulation and liquid-cooled load-bank practices are still developing, limiting consistent validation methods across projects. These factors support market growth but also cap the speed at which specialist capacity can expand.
Segment Analysis
By Service Stage
Functional testing and integrated systems testing represent the largest 2026 revenue pool because they require multidisciplinary teams, detailed procedures and extended on-site execution across critical power and cooling systems. Factory witness and factory acceptance testing remains important for large prefabricated power trains, CDUs and modular systems because problems are materially cheaper to correct before shipment. Retro-commissioning and performance revalidation are expected to expand as operators retrofit existing data centers for AI racks and revisit redundancy, controls and cooling assumptions after major capacity changes.
By System Domain
Electrical power remains the largest commissioning domain in 2026 because switchgear, uninterruptible power supplies, generators, batteries, protection systems and distribution paths must be validated under normal and failure conditions. Liquid cooling and technology cooling systems are the fastest-growing domain through 2032 as direct-to-chip architectures become standard in high-density AI deployments. Controls and software-interface validation also grows rapidly as building systems, power telemetry and AI-factory orchestration become more tightly connected.
Table 1. Principal AI Data Center Commissioning and Validation Service Areas
Service Area | 2026 Position | Core Validation Scope | Typical Project Stage |
Functional and integrated systems testing | Largest value pool | Power, cooling, controls, redundancy and failure scenarios | Site commissioning / acceptance |
Liquid cooling and TCS commissioning | Fastest-growing domain | Flushing, pressure tests, fluid quality, CDU and loop performance | Factory, installation and site acceptance |
Factory witness / acceptance testing | High-value risk reduction | Equipment capacity, controls, protection and factory integration | Before shipment |
Load-bank and AI-load emulation | Expanding validation layer | Electrical and thermal response under realistic load profiles | Pre-production / integrated testing |
Controls and telemetry validation | Growing cross-domain service | BMS, EPMS, alarms, sequencing, IT/OT data and fail-safe behavior | Functional and integrated testing |
Retro-commissioning / revalidation | Fast-growing brownfield service | Validate upgraded power, cooling and controls against existing infrastructure | Retrofit and capacity expansion |
Market and Adoption Indicators
Table 2. Indicators Supporting AI Data Center Commissioning Demand
Indicator | Recent Evidence | Market Relevance |
Liquid-cooling commissioning complexity | Uptime Institute reported in January 2026 that CDUs and technology cooling loops complicate commissioning and require rigorous factory witness testing. | Adds specialist mechanical, controls and fluid-quality work to conventional commissioning. |
AI-specific commissioning guidance | ASHRAE highlights cleaning, flushing, passivation and granular turnover milestones for liquid-cooled AI factories. | Raises validation content and documentation requirements per MW. |
Specialist labor constraint | Schneider Electric described liquid-cooling commissioning capability as one of the hardest resources to secure in rapidly expanding markets. | Supports pricing and demand for qualified commissioning teams while constraining supply. |
Lifecycle services expansion | Vertiv offers AI and liquid-cooling lifecycle services spanning deployment, commissioning and maintenance, including L1-L5 commissioning. | Shows infrastructure OEMs expanding into recurring commissioning and validation services. |
Validated AI reference designs | NVIDIA DSX and Schneider Electric AI reference designs integrate power, cooling, controls and lifecycle software at multi-megawatt scale. | Increases need to verify complete system behavior rather than isolated equipment. |
AI load emulation | Uptime Institute is highlighting liquid-cooled load banks for commissioning AI workloads and validating power and cooling systems. | Creates new test equipment and procedures for realistic high-density acceptance testing. |
Regional Opportunity
North America
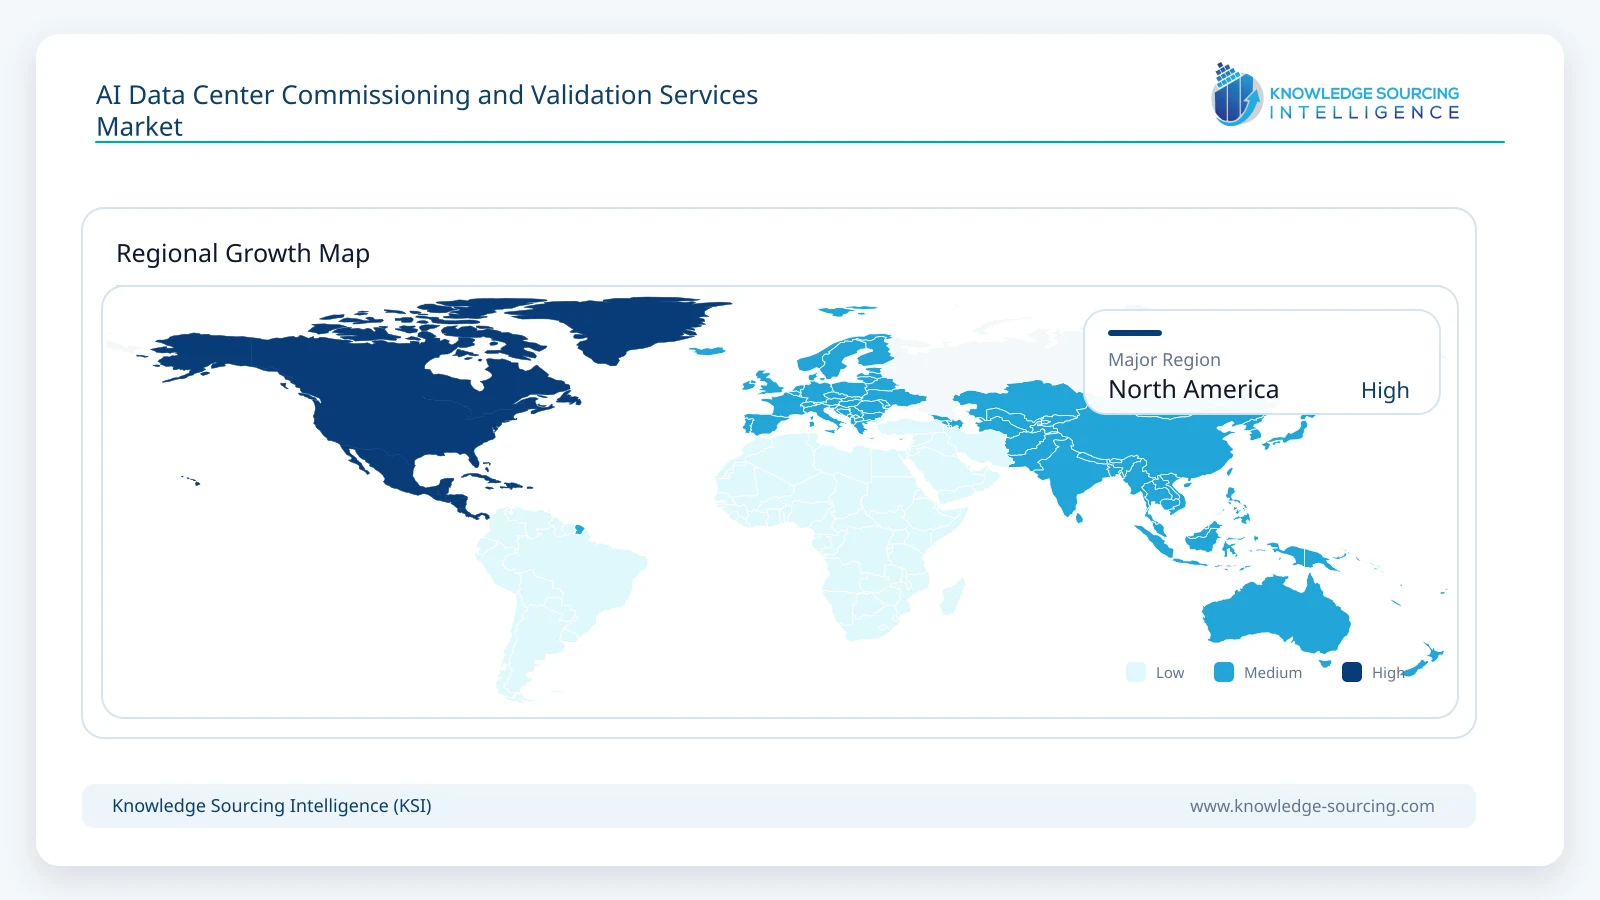
North America is the largest market for AI data-center commissioning and validation services because the United States combines the largest concentration of hyperscale and neocloud AI construction with rapid adoption of liquid cooling, modular infrastructure and high-density electrical systems. Large campuses are increasingly delivered in phased blocks, creating repeated commissioning events as each power, cooling and white-space increment reaches mechanical completion. The financial value of avoiding delayed GPU deployment also supports more rigorous integrated testing and earlier factory validation than would be justified in lower-value computing environments.
The region has a deep ecosystem of commissioning agents, engineering firms, project managers and infrastructure original equipment manufacturers, but specialist resources remain constrained in the fastest-growing markets. Liquid cooling intensifies that pressure because teams must understand technology cooling loops, fluid cleanliness, CDU controls, redundancy behavior and interactions with facility water systems. Vertiv, Schneider Electric, Eaton, Trane Technologies and Johnson Controls participate from the equipment and lifecycle-services side, while engineering and project-services firms such as Jacobs, AECOM, CBRE, JLL, Burns & McDonnell, HDR, Salas O'Brien and Syska Hennessy provide broader project and commissioning capabilities.
Retrofit demand is also significant. Many existing facilities were designed for rack densities far below current AI requirements, so introducing liquid-cooled clusters can require new power trains, CDUs, piping, controls and heat rejection while the rest of the site remains operational. These projects require tightly staged commissioning because testing cannot compromise existing critical loads. Through 2032, North American demand is therefore expected to remain split between large greenfield AI factories, phased hyperscale expansions and brownfield AI-readiness retrofits rather than one dominant project type.
Europe, Asia Pacific and Middle East
Europe combines established commissioning practice with growing liquid-cooling adoption and stricter energy and environmental requirements, while project scale varies by market. Asia Pacific is expanding rapidly across Japan, Singapore, Malaysia, India, Australia and South Korea, but availability of experienced commissioning personnel differs materially by country. Middle Eastern AI campuses are often large greenfield developments where commissioning programs can be embedded early in the project, although local specialist capacity is still being built. Across all three regions, multinational engineering firms and infrastructure vendors increasingly supplement local teams with standardized test procedures and cross-border expertise.
Competitive Landscape
The competitive landscape spans independent commissioning specialists, engineering consultants, project-management firms, data-center infrastructure vendors and building-automation companies. Independent and engineering-led providers are strongest where owners want vendor-neutral verification across electrical, mechanical and controls systems. Original equipment manufacturers are increasingly relevant where commissioning requires deep knowledge of liquid cooling, power electronics, controls or proprietary software interfaces. This creates a mixed delivery model in which an independent commissioning authority may lead the program while OEM engineers execute specialist tests and corrective work.
Differentiation is moving toward high-density liquid-cooling expertise, integrated systems testing, repeatable multi-site procedures and the ability to coordinate digital models with physical test results. Firms that can mobilize qualified personnel globally are advantaged as hyperscalers and neocloud operators repeat similar AI designs across regions. Software-assisted documentation and issue management are also becoming important because accelerated schedules generate large volumes of test data and punch-list items that must be closed before production handover.
Major companies and ecosystem participants covered: Vertiv, Schneider Electric, Siemens, Eaton, Trane Technologies, Johnson Controls, Jacobs, AECOM, CBRE, JLL, Burns & McDonnell, HDR, Salas O'Brien, Cundall, DLB Associates, Syska Hennessy Group, NV5 and Exyte.
Recent Developments
September 2026: Schneider Electric published updated Vera Rubin AI data-center reference designs integrating multi-megawatt liquid-cooled power, cooling and lifecycle systems.
August 2026: Schneider Electric highlighted commissioning capability as a critical supply-chain consideration for liquid-cooled data centers in India, including factory and site acceptance, flushing, fluid-quality validation and integrated testing.
July 2026: Schneider Electric released first liquid-cooled AI reference designs for AMD rack-scale infrastructure, expanding validated greenfield and retrofit architectures.
May 2026: Schneider Electric and Motivair progressed phased delivery of more than USD 290 million in power and liquid-cooling infrastructure at TeraWulf's 750 MW Lake Mariner campus.
March 2026: NVIDIA released the Vera Rubin DSX AI Factory reference design and Omniverse DSX Blueprint, expanding system-level design and validation across power, cooling, networking and operations.
January 2026: Uptime Institute published guidance on commissioning coolant distribution units and technology cooling loops, emphasizing factory witness testing and integrated validation.
AI Data Center Commissioning and Validation Services Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.30 billion |
| Total Market Size in 2032 | USD 5.24 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 26.2% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Service Stage, System Domain, Validation Method, Project Type, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Service Stage
Factory Witness and Factory Acceptance Testing
Pre-Functional and Functional Commissioning
Startup and Performance Testing
Integrated Systems Testing
Acceptance, Documentation and Handover
Retro-Commissioning and Revalidation
By System Domain
Electrical Power Systems
Liquid Cooling and Technology Cooling Systems
Mechanical Cooling and Heat Rejection
Controls, BMS and EPMS
IT/OT Interfaces and AI Factory Orchestration
Safety, Fire and Ancillary Systems
By Validation Method
Factory Testing
Load-Bank and AI-Load Emulation
Failure-Mode and Redundancy Testing
Fluid Quality and Hydraulic Validation
Controls and Telemetry Validation
Digital / Model-Assisted Validation
By Project Type
Greenfield AI Factories
Hyperscale Expansion Blocks
AI-Readiness Retrofits
Prefabricated and Modular AI Infrastructure
Sovereign and Enterprise AI Facilities
By Geography
North America
United States
Canada
Europe
Asia Pacific
Middle East and Rest of World
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Market Opportunity and Key Findings
1.2. Commissioning Demand Timeline
1.3. Principal Revenue Pools
2. MARKET OVERVIEW
2.1. Evolution of Data Center Commissioning
2.2. AI Factory Power and Thermal Complexity
2.3. Liquid Cooling and Technology Cooling Systems
2.4. IT and OT Integration
2.5. Factory, Site and Integrated Validation
3. MARKET SIZE AND FORECAST, 2026-2032
3.1. Global Market Revenue
3.2. Annual Growth Analysis
3.3. Commissioning Revenue per MW
3.4. Greenfield versus Retrofit Demand
4. MARKET BY SERVICE STAGE
4.1. Factory Witness and Factory Acceptance Testing
4.2. Pre-Functional and Functional Commissioning
4.3. Startup and Performance Testing
4.4. Integrated Systems Testing
4.5. Acceptance, Documentation and Handover
4.6. Retro-Commissioning and Revalidation
5. MARKET BY SYSTEM DOMAIN
5.1. Electrical Power Systems
5.2. Liquid Cooling and Technology Cooling Systems
5.3. Mechanical Cooling and Heat Rejection
5.4. Controls, BMS and EPMS
5.5. IT/OT Interfaces and AI Factory Orchestration
5.6. Safety, Fire and Ancillary Systems
6. MARKET BY VALIDATION METHOD
6.1. Factory Testing
6.2. Load-Bank and AI-Load Emulation
6.3. Failure-Mode and Redundancy Testing
6.4. Fluid Quality and Hydraulic Validation
6.5. Controls and Telemetry Validation
6.6. Digital / Model-Assisted Validation
7. MARKET BY PROJECT TYPE
7.1. Greenfield AI Factories
7.2. Hyperscale Expansion Blocks
7.3. AI-Readiness Retrofits
7.4. Prefabricated and Modular AI Infrastructure
7.5. Sovereign and Enterprise AI Facilities
8. REGIONAL MARKET
8.1. North America
8.1.1. United States
8.1.2. Canada
8.2. Europe
8.3. Asia Pacific
8.4. Middle East and Rest of World
9. MARKET DYNAMICS
9.1. Drivers
9.1.1. Liquid-Cooling Commissioning Complexity
9.1.2. Cost of Delayed AI Capacity
9.1.3. Integrated IT/OT Validation
9.1.4. Modular and Phased Construction
9.2. Restraints
9.2.1. Specialist Labor Availability
9.2.2. Compressed Testing Windows
9.2.3. Fragmented Vendor Responsibility
9.2.4. Immature AI Load-Emulation Practices
10. COMPETITIVE LANDSCAPE
10.1. Value Chain
10.2. Independent Commissioning Providers
10.3. Engineering and Project-Service Firms
10.4. Infrastructure OEM Service Organizations
10.5. Controls and Automation Providers
10.6. Multi-Site and Global Delivery Models
11. COMPANY PROFILES
11.1. Vertiv
11.2. Schneider Electric
11.3. Siemens
11.4. Eaton
11.5. Trane Technologies
11.6. Johnson Controls
11.7. Jacobs
11.8. AECOM
11.9. CBRE
11.10. JLL
11.11. Burns & McDonnell
11.12. HDR
11.13. Salas O'Brien
11.14. Cundall
11.15. DLB Associates
11.16. Syska Hennessy Group
11.17. NV5
11.18. Exyte
12. RECENT DEVELOPMENTS
13. APPENDIX
13.1. Definitions and Abbreviations
13.2. Commissioning Level and Test Classification
13.3. AI Data Center Validation Framework
13.4. Source and Data Notes





Frequently asked questions
What is the projected market size for AI Data Center Commissioning Services by 2032?
The AI Data Center Commissioning and Validation Services Market is projected to reach USD 5.24 billion by 2032.
What is the CAGR for the AI Data Center Commissioning Services Market?
The AI Data Center Commissioning and Validation Services Market is projected to grow at a 26.2% CAGR from 2026 to 2032.
Which region currently leads the demand for these services?
North America leads demand due to hyperscale and neocloud AI construction.
What are key drivers of growth in this commissioning market?
Liquid cooling, integrated testing, compressed schedules, and retrofit commissioning drive growth.
How does liquid cooling impact commissioning services for AI data centers?
Liquid cooling expands commissioning into technology cooling loops and rack interfaces.
What is a limiting factor for this market's growth worldwide?
Specialist commissioning labor remains a limiting factor globally.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). AI Data Center Commissioning and Validation Services Market Size, Share & Growth Forecast (2026-2032). https://www.knowledge-sourcing.com/report/ai-data-center-commissioning-and-validation-services-market