
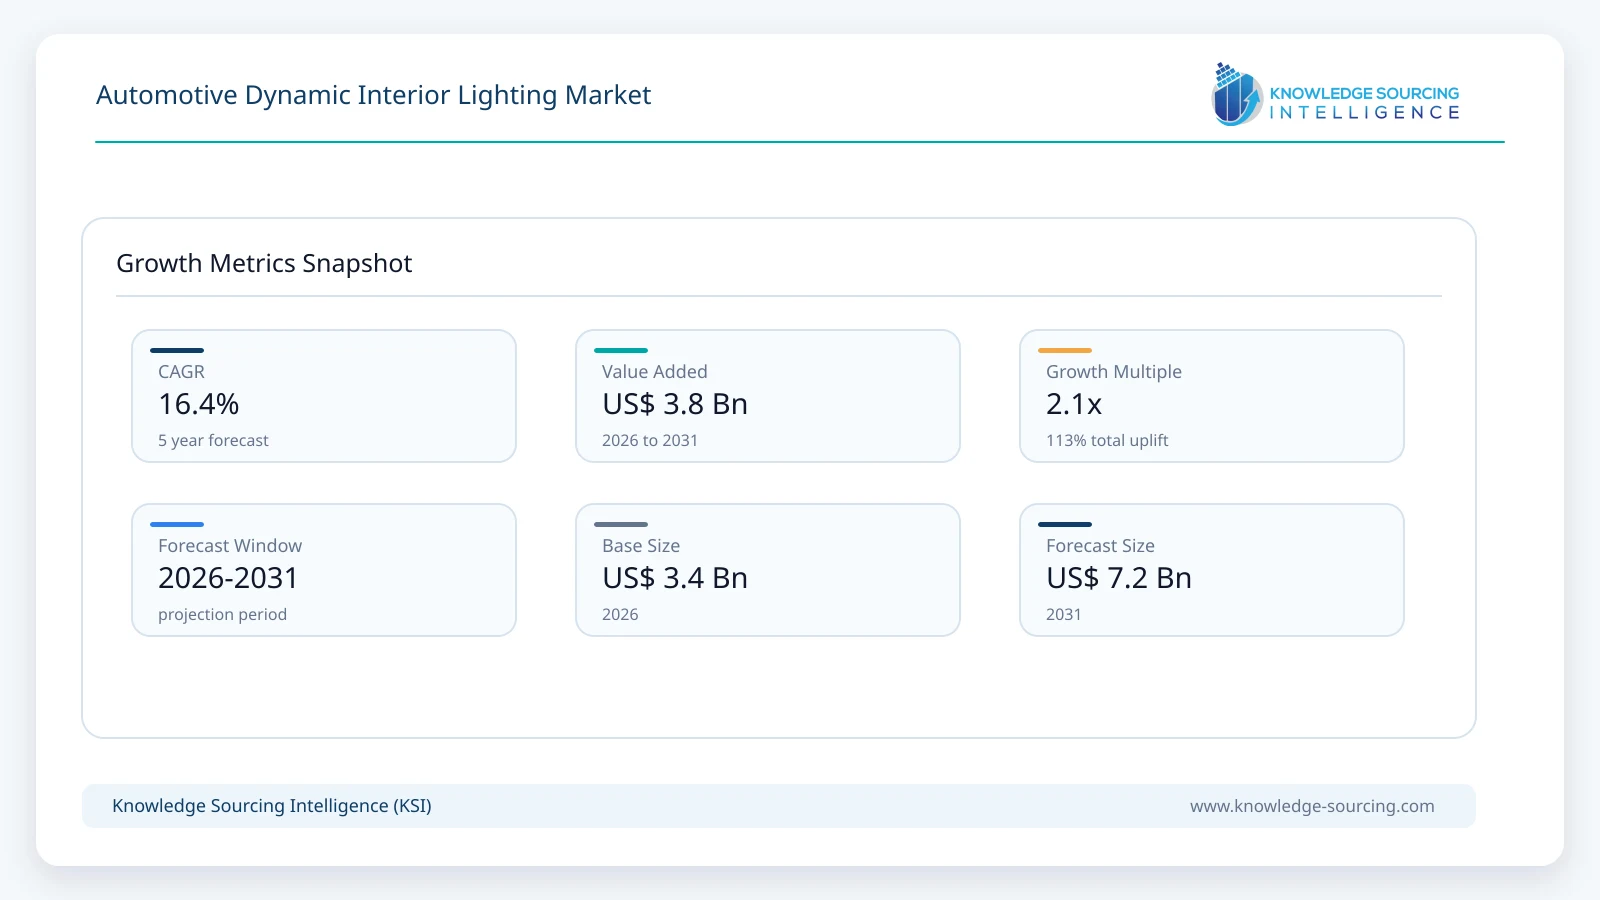
The Automotive Dynamic Interior Lighting Market is projected to expand at a CAGR of 16.4%, increasing from USD 3.35 billion in 2026 to USD 7.15 billion by 2031.
Highlights:
- 1Dynamic RGB ambient and contour lighting accounts for approximately 57% of global market value in 2026 because it remains the main route for animated cabin personalization and real-time visual feedback.
- 2Distributed intelligent LED networks represent approximately 36% of 2026 control-architecture value and are gaining share as embedded drivers and serial communication reduce wiring and calibration complexity.
- 3User-selectable and profile-driven lighting represents approximately 39% of 2026 trigger logic, while vehicle-state, ADAS and sensor-responsive activation is growing faster.
- 4Door panels and instrument-panel/console zones together account for approximately 56% of 2026 demand because these locations provide long visible surfaces for continuous animation and contextual light effects.
- 5Passenger vehicles represent approximately 95% of global market value in 2026, led by premium cars, EVs and technology-focused SUVs with high lighting content per vehicle.
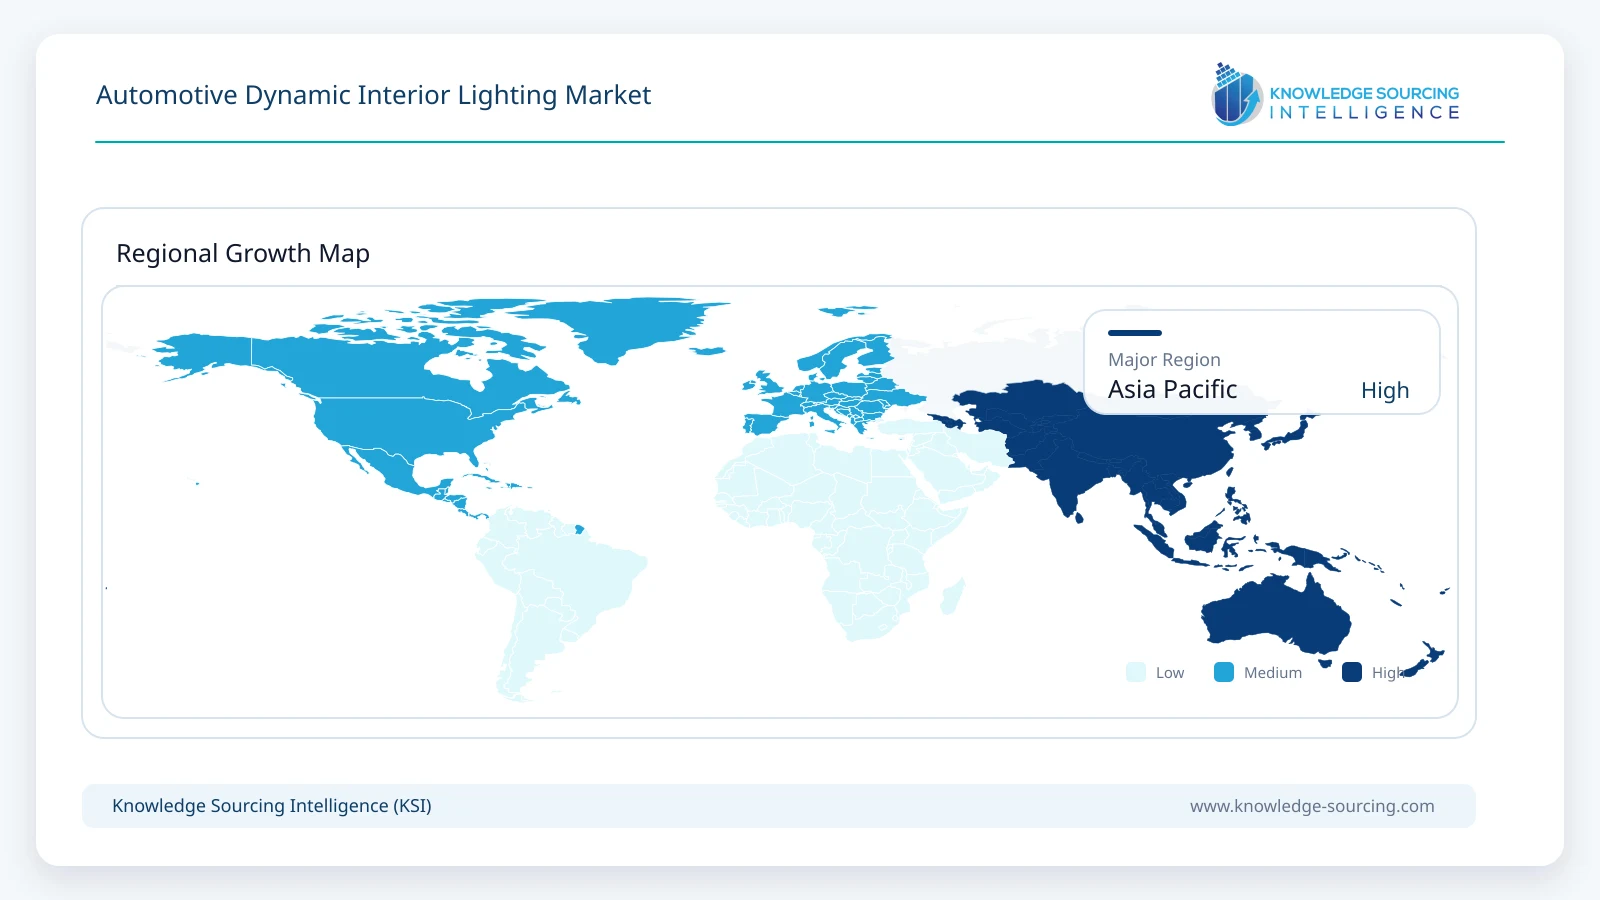
- 6Asia Pacific represents approximately 47% of global market value in 2026, supported by fast smart-cabin development in China and strong regional LED, electronics and interior-systems supply chains.
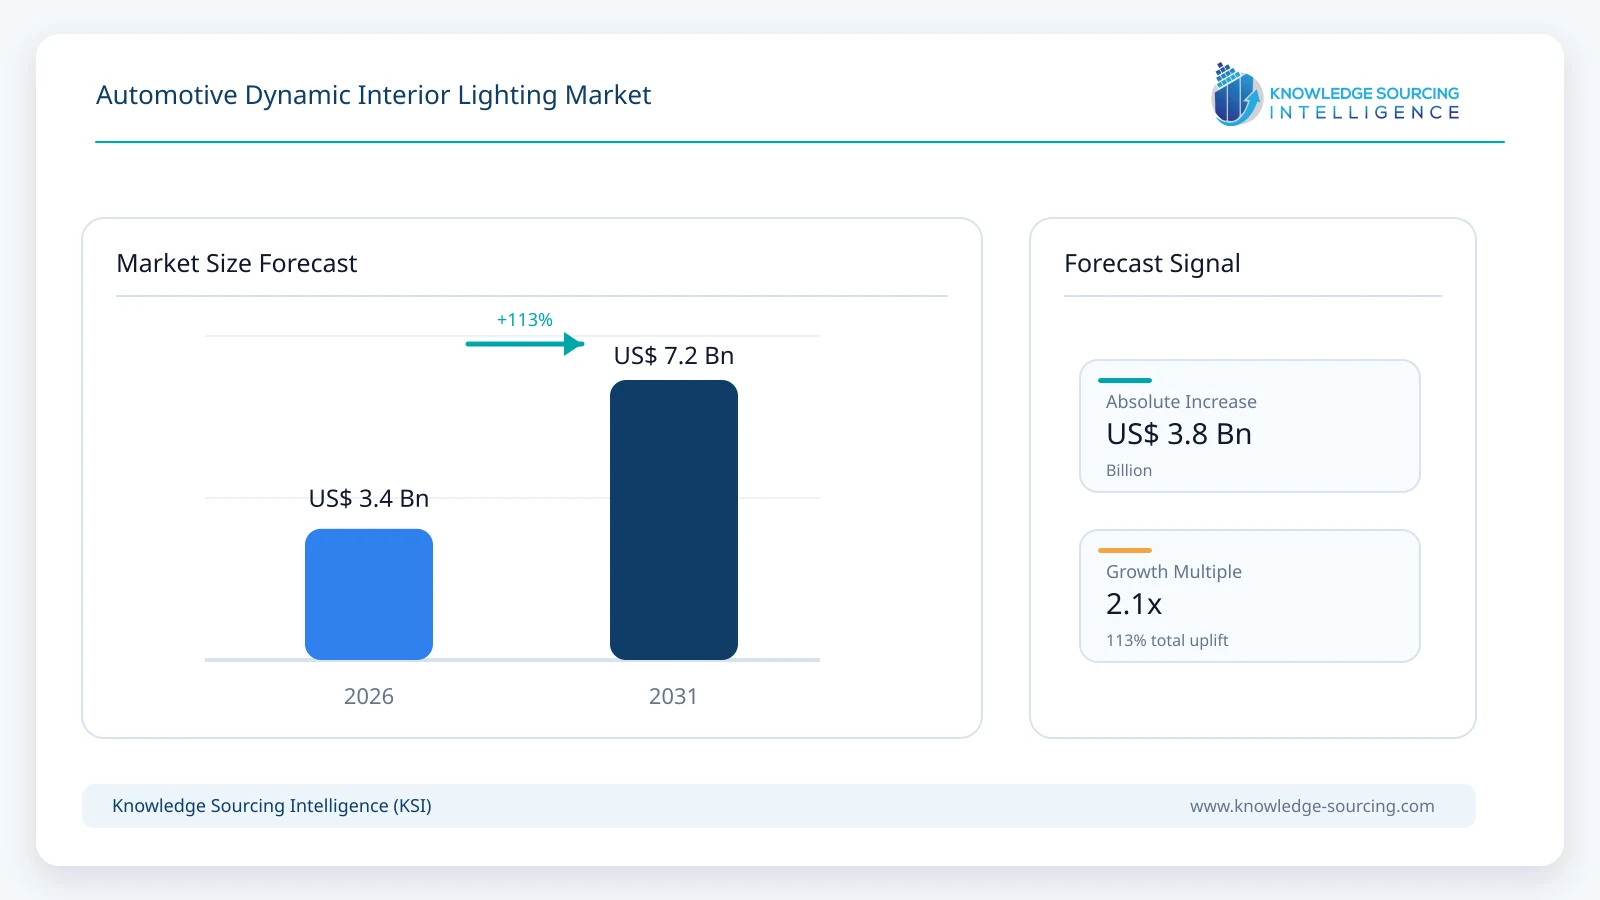
Increasing use of addressable LEDs, software-controlled cabin modes, and distributed lighting networks is moving interior illumination away from fixed lamps toward systems that can change continuously with the vehicle and occupant context.
Dynamic RGB ambient and contour lighting currently forms the largest value pool because it gives OEMs a visible way to personalize the cabin while also supporting welcome sequences, drive-mode feedback, navigation cues and localized alerts. Adaptive functional lighting, animated warning patterns and synchronized light effects are expanding the market beyond ambience as the same hardware begins to serve comfort, communication and HMI functions.
The market counts lighting hardware, optical elements, distributed drivers, local control electronics and software directly required to create dynamic behavior. Static dome, map and vanity lamps, fixed-color decorative strips and display backlighting are excluded unless they form part of a programmable lighting architecture, while the full value of trim panels or smart surfaces is counted only to the extent attributable to the dynamic lighting system.
Market Overview
Real-time control is the defining characteristic of dynamic interior lighting, allowing the cabin to change visually according to a selected profile, driving mode, media input, assistance-system event or sensor signal. Individually addressable RGB and white-light points can create gradients, moving light patterns and localized cues across doors, instrument panels, consoles, roof areas and footwells without requiring a separate display in every location.
Higher light-point density is changing the underlying electrical architecture. Smart LEDs can incorporate drivers, calibration data and communication capability at the device level, while centralized or zonal controllers coordinate larger networks through serial protocols. This reduces the number of discrete driver components and makes it easier to synchronize lighting across several cabin zones with consistent color and timing.
Dynamic lighting is also moving closer to the HMI layer as animation, color and spatial position are used to reinforce alerts, navigation guidance, charging status, incoming calls and selected driver-assistance functions. The commercial value therefore depends increasingly on software logic, calibration and cross-domain integration rather than on LED hardware alone.
Market Trends
Individually Addressable RGB Networks Are Becoming the Main Dynamic-Lighting Architecture
Dense networks of individually controlled RGB LEDs are replacing simpler zone-based systems in premium and technology-focused vehicles because each light point can be calibrated, animated, and synchronized independently. ams OSRAM's 2026 deployment of the OSIRE E3731i intelligent RGB LED in the NIO ES9 shows how serially connected smart emitters are moving into production vehicles with high-content ambient-lighting systems.
Greater addressability allows OEMs to create smooth movement, local color changes, and fine-grained transitions without adding a dedicated controller for each illuminated feature. The architecture also supports future software features because the behavior of installed light points can be changed after the hardware platform is fixed.
Dynamic Lighting Is Expanding from Atmosphere into Vehicle Communication
Color, intensity, and animation are increasingly used to communicate vehicle and assistance-system states in addition to creating ambience. FORVIA HELLA's 2026 adaptive RGB concept for commercial vehicles demonstrates how the same integrated lighting surface can support distance warnings, battery status, incoming calls, assistance-system feedback and rest-phase ambience.
Using one lighting network for both comfort and information improves hardware utilization, although the communication logic must remain simple enough that occupants can distinguish a safety cue from a decorative animation without hesitation.
Content-Synchronized Lighting Is Strengthening the Immersive Cabin Experience
Music, video and infotainment synchronization is giving dynamic lighting a larger role in the entertainment experience, particularly in EVs and premium rear-seat environments where the cabin is increasingly designed for stationary and lounge use. Toyota Boshoku's LOUNZE+ concept at Auto China 2026 used illumination synchronized with visual content to increase immersion within a coordinated interior space.
The feature raises demand for low-latency control and consistent color across several cabin zones because poorly synchronized lighting can reduce rather than improve perceived quality. Integration with audio and display software is therefore becoming an important part of lighting-system design.
Smart Surfaces Are Increasing the Area Available for Dynamic Light Effects
Hidden-until-lit trim, in-mold electronics and thin optical structures are extending dynamic illumination beyond conventional light guides into broader door, console and dashboard surfaces. Valeo's 2026 high-volume interior program using TactoTek IMSE technology illustrates the shift toward surfaces in which lighting and electronics are integrated into one ready-to-use structure.
Larger illuminated areas allow dynamic effects to become part of the trim design rather than appearing as separate lamp features, but they also increase the need for optical uniformity, thermal control and tight coordination between lighting and material suppliers.
Adaptive White and Wellness-Oriented Modes Are Broadening the Dynamic Use Case
Tunable-white and calibrated RGB systems are being used for more than visual personalization as OEMs add relaxation, alertness and time-of-day lighting modes. Dynamic control allows the same hardware to shift from brighter, cooler light during active driving to warmer, lower-intensity settings during evening or rest phases.
These functions remain smaller than RGB ambience but improve the business case for advanced lighting because a single network can support personalization, task lighting, communication, and wellness rather than serving only decorative purposes.
Segment Analysis
By Lighting Type: Dynamic RGB Ambient and Contour Lighting
Programmable RGB lighting leads the market because it combines high visual impact with flexible software control across doors, dashboards, consoles, footwells and roof structures. Individually addressable devices can produce gradients, moving patterns, localized cues and profile-specific color themes from one common hardware architecture.
Dynamic RGB ambient and contour lighting accounts for approximately USD 1.91 billion in 2026 and could reach about USD 3.91 billion by 2031. Its share is expected to ease slightly as adaptive functional lighting, projection and wellness-oriented dynamic modes expand faster from smaller bases.
By Control Architecture: Distributed Intelligent LED Networks
Embedding communication, drivers, and calibration data closer to the light source makes distributed intelligent LED networks well suited to cabins with dozens or hundreds of addressable light points. Serial architectures simplify wiring and make it easier to preserve color consistency across several lighting zones.
Distributed intelligent LED networks represent approximately USD 1.21 billion in 2026 and are projected to exceed USD 2.95 billion by 2031 as OEMs move from simple centrally driven strips toward scalable smart-LED architectures.
By Trigger Logic: User-Selectable and Profile-Driven Lighting
User-selected themes, welcome sequences, drive-mode colors and profile-linked settings remain the largest trigger category because they are easy for occupants to understand and provide immediate perceived value. These functions are also straightforward to implement across different trim levels once the lighting network is installed.
User-selectable and profile-driven control accounts for approximately USD 1.31 billion in 2026. Vehicle-state, ADAS, occupant-sensor and media-synchronized triggers are expected to gain share through 2031 as dynamic lighting becomes more closely connected to centralized cockpit software.
By Application Location: Door Panels
Long illuminated contours, broad decorative surfaces and close proximity to handles, speakers and side-warning functions make door panels the largest location for dynamic interior lighting. Door lighting can move seamlessly between ambience, welcome effects and contextual cues without adding a separate display.
Door-panel applications are estimated at approximately USD 0.97 billion in 2026 and could approach USD 2.00 billion by 2031 as dynamic lighting extends into rear doors and broader surface areas across mainstream vehicle classes.
By Vehicle Type: Passenger Vehicles
Passenger cars, SUVs and MPVs dominate the market because dynamic cabin lighting is increasingly used as a premium and technology differentiator, particularly in EVs where interior experience carries more brand value. Chinese manufacturers are also pushing dense animated lighting into price segments that previously relied on simple ambient strips.
Passenger vehicles account for approximately USD 3.18 billion in 2026 and are projected to reach about USD 6.72 billion by 2031. Commercial-vehicle demand remains smaller but is increasing as driver cabins add dynamic alerts, customizable ambience and rest-phase lighting.
Market Drivers
Software-Defined Cockpits Are Turning Lighting into a Programmable Feature Layer
Centralized cockpit software and zonal electrical architectures allow interior lighting to use the same vehicle-state, profile, infotainment and ADAS information as displays and audio systems. This makes lighting behavior easier to coordinate across the cabin and allows one hardware platform to support several software-defined functions.
Feature updates can also extend the useful value of installed light points after vehicle launch, improving the commercial case for addressable systems compared with fixed-function decorative lighting.
Consumer Demand for Personalization Is Increasing Light-Point Density
Animated welcome sequences, selectable color themes and profile-linked cabin settings have become visible indicators of digital sophistication, encouraging OEMs to install more individually controlled light points. Premium EVs have accelerated this trend because the cabin is a major area for product differentiation.
Higher point density raises demand not only for LEDs but also for calibration, communication ICs, optical guides and software that keep several zones visually consistent throughout the vehicle life.
Lighting-Based HMI Is Adding Functional Value beyond Decoration
Dynamic light can direct attention toward a hazard, reinforce an assistance-system state or provide spatial guidance without requiring another screen. These functions make interior lighting relevant to HMI and safety teams rather than leaving investment decisions entirely within styling or comfort programs.
The strongest systems use light as a supporting channel alongside displays and sound, allowing color and movement to improve recognition while avoiding an excessive number of new visual symbols.
Smart LEDs and Serial Lighting Protocols Are Improving Scalability
Integrated drivers, embedded calibration and serial communication reduce the number of separate electronics required for complex lighting networks. The 2026 NIO ES9 deployment of an intelligent RGB LED based on an open-system protocol demonstrates how suppliers are simplifying high-density architectures for production vehicles.
Lower wiring complexity and easier color calibration support broader adoption because the incremental cost of adding more dynamic light points can fall as the network becomes standardized across several applications.
Flexible Light Guides and Smart Surfaces Are Removing Packaging Constraints
Thin optical structures, conformal light guides and embedded electronics allow dynamic effects to follow curved doors, consoles and roof structures where rigid conventional modules are difficult to package. This increases the usable illuminated area without demanding large cavities behind the trim.
Greater design freedom is especially important in compact EV cabins, where interior differentiation must be achieved without giving up passenger space or adding unnecessary component mass.
Market Restraints
Color Consistency Becomes More Difficult as Networks Add Light Points
Small differences in LED output, temperature and aging are easier to notice when many light points operate together in a continuous animation. Premium systems therefore require calibration data, thermal compensation and optical tuning so a moving effect does not reveal visible color or brightness steps between zones.
The validation burden increases further when different materials, light guides and surface finishes are used across doors, consoles and dashboards within the same visual sequence.
Driver Distraction Limits the Use of Aggressive Animation
Fast movement, high brightness or frequent color changes can compete with the road scene for driver attention, particularly at night. Dynamic lighting also risks losing meaning if decorative effects use the same colors or motion patterns as safety-related cues.
OEMs need clear priority rules, automatic dimming and driving-state restrictions so expressive lighting remains available without creating unnecessary visual workload.
Complex Electronics and Software Increase Validation Requirements
Addressable lighting networks add communication, diagnostics, calibration and software dependencies to what was previously a relatively simple body-electronics function. A fault in timing or network communication can affect several cabin zones even when the LEDs themselves remain operational.
Platform-level validation and diagnostic coverage therefore become more important as lighting is connected to ADAS, infotainment and occupant-sensing data.
Cost Pressure Remains Significant in Mainstream Vehicle Programs
Smart LEDs, additional control channels, optical guides and embedded electronics cost more than static ambient strips, while high point counts can increase assembly and testing time. The value proposition weakens when dynamic effects are added only for decoration and do not replace other content.
Common modules, shared software and scalable lighting networks are therefore essential for bringing dynamic systems into higher-volume vehicles without increasing interior cost disproportionately.
Durability and Material Integration Can Affect Long-Term Visual Quality
Heat, UV exposure, abrasion and material aging can change the transmission and color of light through decorative surfaces over time. Embedded lighting behind films, skins or molded parts also introduces interfaces that must remain stable through temperature cycling and vibration.
Reliable production requires close coordination between lighting, trim and material suppliers because a small surface variation can become visible once animated light passes through the component.
Regional Outlook
Asia Pacific
China's fast smart-cabin development cycle and high adoption of animated RGB lighting in new energy vehicles make Asia Pacific the largest regional market in 2026. NIO's adoption of an intelligent RGB LED network in the ES9 and the broader use of highly configurable lighting by regional EV manufacturers show how quickly dynamic features are moving from flagship models into wider product portfolios.
Japan and South Korea add strong lighting, semiconductor and interior-systems capabilities, while China provides scale and rapid commercialization. Growth through 2031 will be driven more by rising content per vehicle and wider penetration into mid-range models than by vehicle-production growth alone.
Europe
Premium OEM programs and a strong lighting-supplier base keep Europe a high-value market for dynamic interior lighting, particularly in adaptive ambient, safety communication and surface-integrated applications. FORVIA HELLA and Valeo are industrializing modular RGB and embedded lighting architectures that can support several cabin functions from a common platform.
European adoption is expected to emphasize controlled functional use alongside personalization, with strong attention to driver-distraction management, consistent color quality, and integration with sustainable interior materials. Slower production growth should be offset by high system value per vehicle in premium and electrified platforms.
Competitive Landscape
FORVIA HELLA, Valeo, ams OSRAM, Toyoda Gosei and other lighting specialists are competing on the ability to deliver scalable dynamic architectures rather than individual lamps. Their portfolios increasingly combine intelligent RGB devices, serial communication, optical design and software-controlled functions that can be reused across several cabin zones.
Interior suppliers and smart-surface specialists such as Antolin, Yanfeng and TactoTek expand the competitive boundary by embedding dynamic light into trim panels and molded electronic structures. This shifts more value toward integration, where surface materials, optical performance, touch functions and lighting behavior must be validated together.
Competitive advantage will depend on network scalability, color calibration, low wiring complexity, packaging depth and the ability to support both expressive personalization and clear functional communication. Suppliers that can reuse common electronics and software across multiple vehicle programs should be better positioned as OEMs push dynamic lighting into higher-volume platforms.
Recent Developments
3 September 2026: FORVIA HELLA presented adaptive RGB interior lighting for commercial vehicles, combining dynamic animations, full-color personalization and lighting-based communication in integrated cabin surfaces.
5 August 2026: FORVIA HELLA highlighted scalable interior-lighting concepts using bendable and modular lighting approaches to extend dynamic illumination across different cabin geometries and vehicle programs.
29 May 2026: Toyoda Gosei announced that its LIN-supported interior full-color illumination unit was adopted on the new Mazda CX-5, adding networked color control and greater installation flexibility.
12 May 2026: ams OSRAM announced integration of its OSIRE E3731i intelligent RGB LED and Open System Protocol architecture in the NIO ES9 for personalized and dynamic cabin lighting.
23 April 2026: Toyota Boshoku presented the LOUNZE+ concept at Auto China 2026 with an illumination system synchronized to visual content to strengthen immersion within a coordinated interior environment.
20 January 2026: Valeo secured a major premium-automaker interior-lighting program using TactoTek IMSE technology, integrating lighting and electronics into a single production-ready smart structure.
Market Outlook
Broader adoption of addressable RGB networks, adaptive functional lighting and software-controlled cabin modes is strengthening demand for the automotive dynamic interior lighting market. Dynamic RGB ambient and contour lighting will remain the largest category, while sensor-responsive, HMI-oriented and surface-integrated functions gain traction as cockpit architectures become more centralized. Automakers are increasingly integrating customizable lighting features to enhance cabin aesthetics, improve driver interaction and support personalized in-vehicle experiences.
Advances in LED technology, lighting control software and electronic integration are expanding design flexibility across vehicle segments. Additionally, the growing emphasis on intelligent cockpits, user-centric interfaces and differentiated interior designs is creating opportunities for suppliers to develop more sophisticated lighting solutions. These developments are reinforcing the role of dynamic interior lighting as an important component of next-generation automotive cabin design.
The strongest structural shift will be from a small number of independently controlled light zones toward coordinated networks with many individually addressable points. This increases the value of communication electronics, calibration, and software relative to basic LED hardware and makes common platform architecture increasingly important to program economics.
Asia Pacific is expected to retain the largest regional position, while Europe continues to generate high value per vehicle through premium integration and functional lighting. Supplier success will depend on clear human-factors design, consistent optical quality, scalable electronics and simple software behavior that occupants can understand without learning a complex visual language.
Automotive Dynamic Interior Lighting Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 3.35 billion |
| Total Market Size in 2031 | USD 7.15 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 16.4% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Lighting Type, Control Architecture, Trigger Logic, Application Location |
| Companies |
|
Market Segmentation
By Lighting Type
Dynamic RGB Ambient and Contour Lighting
Adaptive Functional and Task Lighting
Dynamic HMI and Warning Lighting
Interior Projection and Pattern Lighting
Tunable-White and Wellness-Oriented Dynamic Lighting
By Control Architecture
Distributed Intelligent LED Networks
Centralized Lighting Controller Architectures
Zonal and Domain-Integrated Lighting
Local Smart-Surface Controllers
By Trigger Logic
User-Selectable and Profile-Driven Lighting
Vehicle-State and Drive-Mode Responsive Lighting
ADAS and Safety-Event Responsive Lighting
Occupant and Sensor-Responsive Lighting
Media and Content-Synchronized Lighting
By Application Location
Door Panels
Instrument Panel and Dashboard
Center Console and Storage Areas
Roof, Headliner and Overhead Modules
Footwell, Seats and Rear-Passenger Areas
By Vehicle Type
Passenger Vehicles
Light Commercial Vehicles
Medium and Heavy Commercial Vehicles and Buses
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
South Korea
India
Indonesia
Thailand
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Research
2.4. Market Estimation
2.5. Segment Modelling
2.6. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Automotive Dynamic Interior Lighting Market Size, 2026-2031
3.3. Lighting Type Outlook
3.4. Control Architecture Outlook
3.5. Trigger Logic Outlook
3.6. Application Location Outlook
3.7. Vehicle Type Outlook
3.8. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Software-Defined Cockpits Are Turning Lighting into a Programmable Feature Layer
4.1.2. Consumer Demand for Personalization Is Increasing Light-Point Density
4.1.3. Lighting-Based HMI Is Adding Functional Value beyond Decoration
4.1.4. Smart LEDs and Serial Lighting Protocols Are Improving Scalability
4.1.5. Flexible Light Guides and Smart Surfaces Are Removing Packaging Constraints
4.2. Market Restraints
4.2.1. Color Consistency Becomes More Difficult as Networks Add Light Points
4.2.2. Driver Distraction Limits the Use of Aggressive Animation
4.2.3. Complex Electronics and Software Increase Validation Requirements
4.2.4. Cost Pressure Remains Significant in Mainstream Vehicle Programs
4.2.5. Durability and Material Integration Can Affect Long-Term Visual Quality
4.3. Market Opportunities
4.4. Porter's Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Dynamic Lighting Hardware, Software and Integration Economics
4.7. Human-Factors, Driver-Distraction and Interior Material Requirements
5. TECHNOLOGY OUTLOOK
5.1. Intelligent RGB LEDs
5.2. Distributed Serial Lighting Networks
5.3. Centralized and Zonal Lighting Control
5.4. Dynamic Light Guides and Diffusers
5.5. Flexible and Conformal Lighting
5.6. In-Mold and Surface-Integrated Dynamic Lighting
5.7. Interior Projection and Pattern Lighting
5.8. Tunable-White and Adaptive White Lighting
5.9. Vehicle-State and ADAS-Responsive Lighting
5.10. Content- and Audio-Synchronized Lighting
5.11. Color Calibration and Thermal Compensation
5.12. Lighting Software and Animation Management
6. AUTOMOTIVE DYNAMIC INTERIOR LIGHTING MARKET BY LIGHTING TYPE
6.1. Introduction
6.2. Dynamic RGB Ambient and Contour Lighting
6.3. Adaptive Functional and Task Lighting
6.4. Dynamic HMI and Warning Lighting
6.5. Interior Projection and Pattern Lighting
6.6. Tunable-White and Wellness-Oriented Dynamic Lighting
7. AUTOMOTIVE DYNAMIC INTERIOR LIGHTING MARKET BY CONTROL ARCHITECTURE
7.1. Introduction
7.2. Distributed Intelligent LED Networks
7.3. Centralized Lighting Controller Architectures
7.4. Zonal and Domain-Integrated Lighting
7.5. Local Smart-Surface Controllers
8. AUTOMOTIVE DYNAMIC INTERIOR LIGHTING MARKET BY TRIGGER LOGIC
8.1. Introduction
8.2. User-Selectable and Profile-Driven Lighting
8.3. Vehicle-State and Drive-Mode Responsive Lighting
8.4. ADAS and Safety-Event Responsive Lighting
8.5. Occupant and Sensor-Responsive Lighting
8.6. Media and Content-Synchronized Lighting
9. AUTOMOTIVE DYNAMIC INTERIOR LIGHTING MARKET BY APPLICATION LOCATION
9.1. Introduction
9.2. Door Panels
9.3. Instrument Panel and Dashboard
9.4. Center Console and Storage Areas
9.5. Roof, Headliner and Overhead Modules
9.6. Footwell, Seats and Rear-Passenger Areas
10. AUTOMOTIVE DYNAMIC INTERIOR LIGHTING MARKET BY VEHICLE TYPE
10.1. Introduction
10.2. Passenger Vehicles
10.3. Light Commercial Vehicles
10.4. Medium and Heavy Commercial Vehicles and Buses
11. AUTOMOTIVE DYNAMIC INTERIOR LIGHTING MARKET BY GEOGRAPHY
11.1. North America
11.1.1. United States
11.1.2. Canada
11.1.3. Mexico
11.2. South America
11.2.1. Brazil
11.2.2. Argentina
11.2.3. Others
11.3. Europe
11.3.1. Germany
11.3.2. United Kingdom
11.3.3. France
11.3.4. Italy
11.3.5. Spain
11.3.6. Others
11.4. Middle East and Africa
11.4.1. Saudi Arabia
11.4.2. UAE
11.4.3. South Africa
11.4.4. Others
11.5. Asia Pacific
11.5.1. China
11.5.2. Japan
11.5.3. South Korea
11.5.4. India
11.5.5. Indonesia
11.5.6. Thailand
11.5.7. Others
12. COMPETITIVE ENVIRONMENT AND ANALYSIS
12.1. Major Players and Strategy Analysis
12.2. Market Share Analysis
12.3. Intelligent RGB and Dynamic Light-Point Benchmarking
12.4. Control Architecture and Serial Network Benchmarking
12.5. Animation, HMI and Functional Lighting Benchmarking
12.6. Smart-Surface and Flexible Lighting Integration Benchmarking
12.7. OEM Programs and Series-Production Readiness
12.8. Competitive Dashboard
13. COMPANY PROFILES
13.1. FORVIA HELLA
13.2. ams OSRAM
13.3. Valeo
13.4. Toyoda Gosei Co., Ltd.
13.5. Antolin
13.6. Yanfeng Automotive Interiors
13.7. TactoTek Oy
13.8. Marelli
13.9. Hyundai Mobis
13.10. Toyota Boshoku Corporation
14. APPENDIX
14.1. Currency
14.2. Assumptions
14.3. Base and Forecast Years Timeline
14.4. Key Benefits for Stakeholders
14.5. Research Methodology
14.6. Abbreviations
14.7. Data Sources
Navigate
Trusted by the world's leading organizations











